Thursday, April 23, 2020

Money Supply Charts Through March 2020

For reference purposes, below are two sets of charts depicting growth in the money supply.
The first shows the MZM (Money Zero Maturity), defined in FRED as the following:
M2 less small-denomination time deposits plus institutional money funds.
Money Zero Maturity is calculated by the Federal Reserve Bank of St. Louis.
Here is the “MZM Money Stock” (seasonally adjusted) chart, updated on April 16, 2020 depicting data through March 2020, with a value of $18,021.3 Billion:
MZMSL
Here is the “MZM Money Stock” chart on a “Percent Change From Year Ago” basis, with a current value of 13.7%:
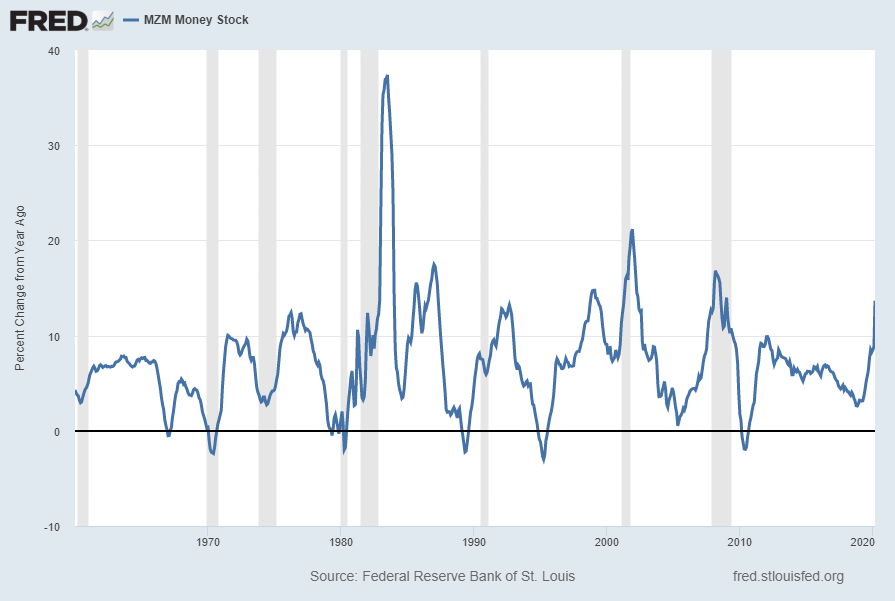
MZMSL Percent Change From Year Ago
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis; accessed April 23, 2020;
https://research.stlouisfed.org/fred2/series/MZMSL
The second set shows M2, defined in FRED as the following:
M2 includes a broader set of financial assets held principally by households. M2 consists of M1 plus: (1) savings deposits (which include money market deposit accounts, or MMDAs); (2) small-denomination time deposits (time deposits in amounts of less than $100,000); and (3) balances in retail money market mutual funds (MMMFs). Seasonally adjusted M2 is computed by summing savings deposits, small-denomination time deposits, and retail MMMFs, each seasonally adjusted separately, and adding this result to seasonally adjusted M1.
Here is the “M2 Money Stock” (seasonally adjusted) chart, updated on April 16, 2020, depicting data through March 2020, with a value of $16,103.9 Billion:
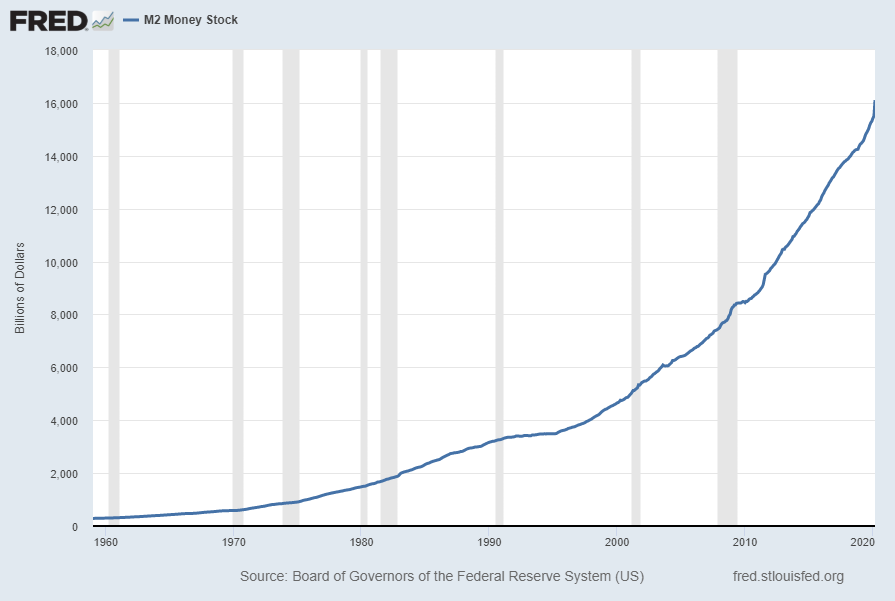
M2SL
Here is the “M2 Money Stock” chart on a “Percent Change From Year Ago” basis, with a current value of 11.0%:
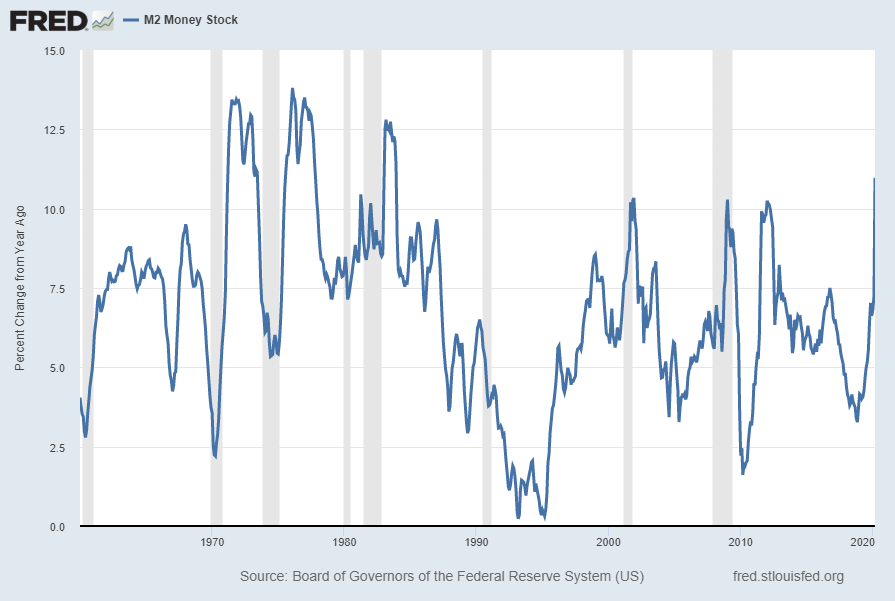
M2SL Percent Change From Year Ago
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis; accessed April 23, 2020;
https://research.stlouisfed.org/fred2/series/M2SL
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 2799.31 as this post is written

The U.S. Economic Situation – April 23, 2020 Update

Perhaps the main reason that I write of our economic situation is that I continue to believe, based upon various analyses, that our economic situation is in many ways misunderstood.  While no one likes to contemplate a future rife with economic adversity, current and future economic problems must be properly recognized and rectified if high-quality, sustainable long-term economic vitality is to be realized.
There are an array of indications and other “warning signs” – many readily apparent – that current economic activity and financial market performance is accompanied by exceedingly perilous dynamics.
I have written extensively about this peril, including in the following:
“Building Financial Danger” (ongoing updates)
My analyses continues to indicate that the growing level of financial danger will lead to the next stock market crash that will also involve (as seen in 2008) various other markets as well.  Key attributes of this next crash is its outsized magnitude (when viewed from an ultra-long term historical perspective) and the resulting economic impact.  This next financial crash is of tremendous concern, as my analyses indicate it will lead to a Super Depression – i.e. an economy characterized by deeply embedded, highly complex, and difficult-to-solve problems.
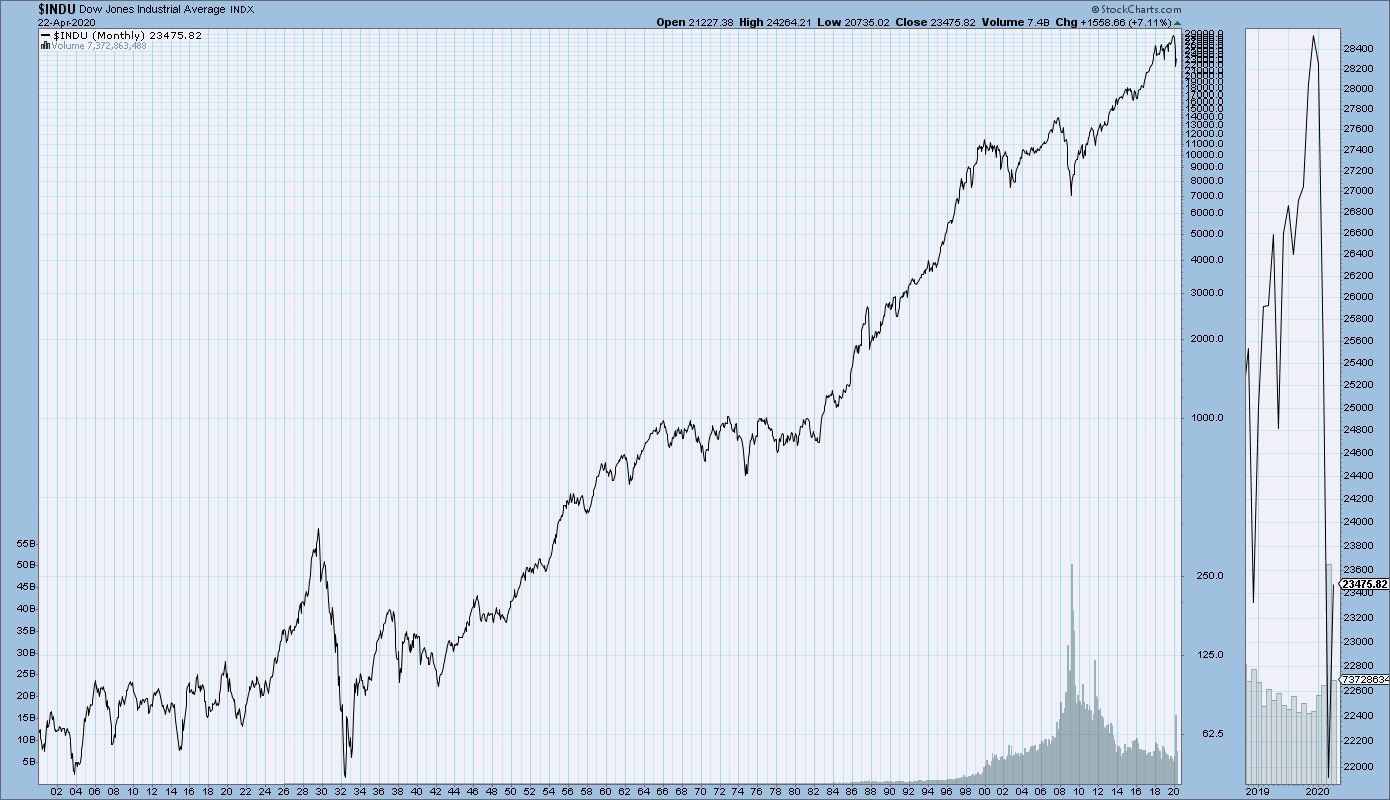
For long-term reference purposes, here is a chart of the Dow Jones Industrial Average since 1900, depicted on a monthly basis using a LOG scale (updated through April 22, 2020, with a last value of 23475.82):
(click on chart to enlarge image)(chart courtesy of StockCharts.com)
DJIA since 1900
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 2799.31 as this post is written
Wednesday, April 22, 2020

Chicago Fed National Financial Conditions Index (NFCI)

The St. Louis Fed’s Financial Stress Index (STLFSI2) is one index that is supposed to measure stress in the financial system.  Its reading as of the April 16, 2020 update (reflecting data through April 10, 2020) is 2.0198.
Of course, there are a variety of other measures and indices that are supposed to measure financial stress and other related issues, both from the Federal Reserve as well as from private sources.
Two other indices that I regularly monitor include the Chicago Fed National Financial Conditions Index (NFCI) as well as the Chicago Fed Adjusted National Financial Conditions Index (ANFCI).
Here are summary descriptions of each, as seen in FRED:
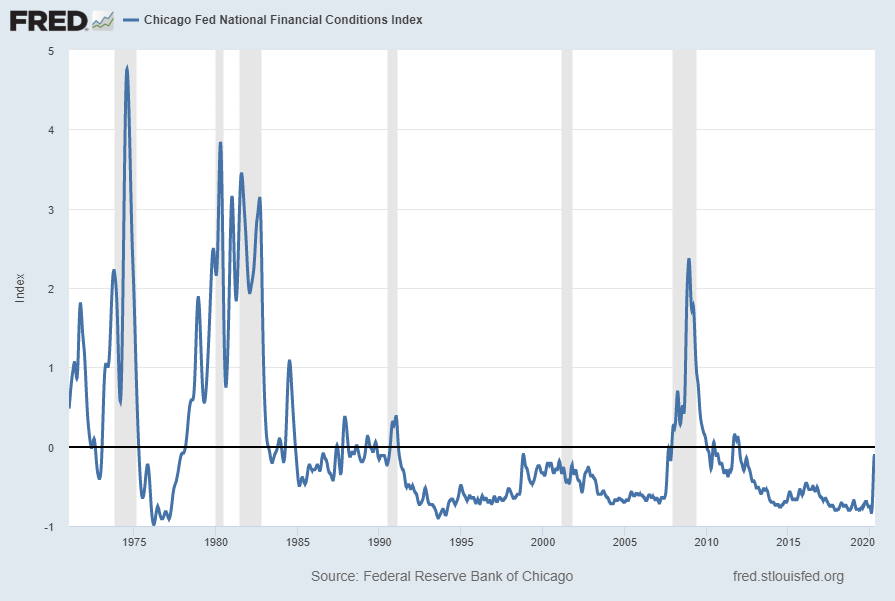
The National Financial Conditions Index (NFCI) measures risk, liquidity and leverage in money markets and debt and equity markets as well as in the traditional and “shadow” banking systems. Positive values of the NFCI indicate financial conditions that are tighter than average, while negative values indicate financial conditions that are looser than average.
The adjusted NFCI (ANFCI). This index isolates a component of financial conditions uncorrelated with economic conditions to provide an update on how financial conditions compare with current economic conditions.
For further information, please visit the Federal Reserve Bank of Chicago’s web site:
Below are the most recently updated charts of the NFCI and ANFCI, respectively.
The NFCI chart below was last updated on April 22, 2020 incorporating data from January 8, 1971 through April 17, 2020, on a weekly basis.  The April 17 value is -.15:
NFCI
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis; accessed April 22, 2020: 
http://research.stlouisfed.org/fred2/series/NFCI
–
The ANFCI chart below was last updated on April 22, 2020 incorporating data from January 8, 1971 through April 17, 2020, on a weekly basis.  The April 17 value is .06:
ANFCI
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis; accessed April 22, 2020: 
http://research.stlouisfed.org/fred2/series/ANFCI
_________
I post various indicators and indices because I believe they should be carefully monitored.  However, as those familiar with this site are aware, I do not necessarily agree with what they depict or imply.
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 2786.03 as this post is written

Trends Of S&P500 Earnings Forecasts

S&P500 earnings trends and estimates are a notably important topic, for a variety of reasons, at this point in time.
FactSet publishes a report titled “Earnings Insight” that contains a variety of information including the trends and expectations of S&P500 earnings.
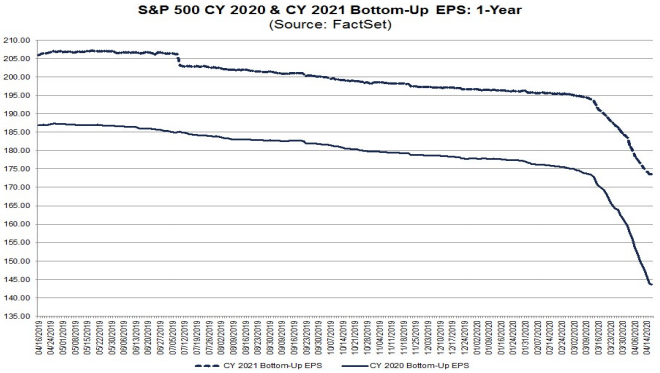
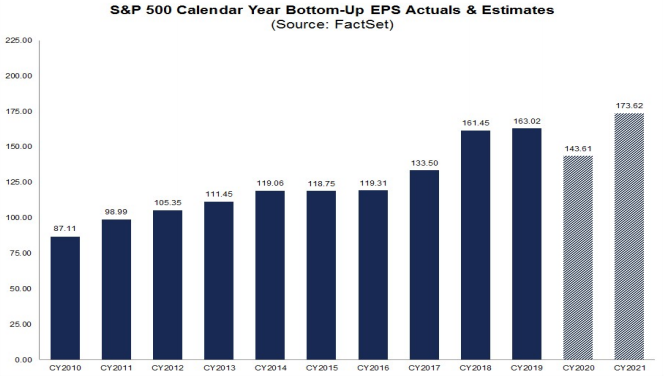
For reference purposes, here are two charts as seen in the “Earnings Insight” report of April 17, 2020:
from page 23:
(click on charts to enlarge images)
S&P500 earnings estimates trends
from page 24:
S&P500 EPS Actuals and Estimates
_____
I post various economic forecasts because I believe they should be carefully monitored.  However, as those familiar with this site are aware, I do not agree with many of the consensus estimates and much of the commentary in these forecast surveys.
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 2736.56 as this post is written

Tuesday, April 21, 2020

S&P500 EPS Estimates 2020 Through 2022 And Prior EPS

As many are aware, Refinitiv publishes earnings estimates for the S&P500.  (My other posts concerning S&P earnings estimates can be found under the S&P500 Earnings label)
The following estimates are from Exhibit 24 of the “S&P500 Earnings Scorecard” (pdf) of April 21, 2020, and represent an aggregation of individual S&P500 component “bottom up” analyst forecasts.  For reference, the Year 2014 value is $118.78/share; the Year 2015 value is $117.46/share; the Year 2016 value is $118.10/share; the Year 2017 value is $132.00/share; the Year 2018 value is $161.93/share; and the Year 2019 value is $162.93/share:
Year 2020 estimate:
$140.05/share
Year 2021 estimate:
$173.37/share
Year 2022 estimate:
$193.95/share
_____
I post various economic forecasts because I believe they should be carefully monitored.  However, as those familiar with this site are aware, I do not agree with many of the consensus estimates and much of the commentary in these forecast surveys.
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 2736.56 as this post is written

Standard & Poor’s S&P500 EPS Estimates 2020 & 2021 – April 16, 2020

As many are aware, Standard & Poor’s publishes earnings estimates for the S&P500.  (My posts concerning their estimates can be found under the S&P500 Earnings label)
For reference purposes, the most current estimates are reflected below, and are as of April 16, 2020:
Year 2020 estimates add to the following:
-From a “bottom up” perspective, operating earnings of $138.65/share
-From a “top down” perspective, operating earnings of N/A
-From a “bottom up” perspective, “as reported” earnings of $125.55/share
Year 2021 estimates add to the following:
-From a “bottom up” perspective, operating earnings of $171.71/share
-From a “top down” perspective, operating earnings of N/A
-From a “bottom up” perspective, “as reported” earnings of $157.84/share
_____
I post various economic forecasts because I believe they should be carefully monitored.  However, as those familiar with this site are aware, I do not agree with many of the consensus estimates and much of the commentary in these forecast surveys.
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 2823.16 as this post is written

Monday, April 20, 2020

Updates Of Economic Indicators April 2020

The following is an update of various indicators that are supposed to predict and/or depict economic activity. These indicators have been discussed in previous blog posts:
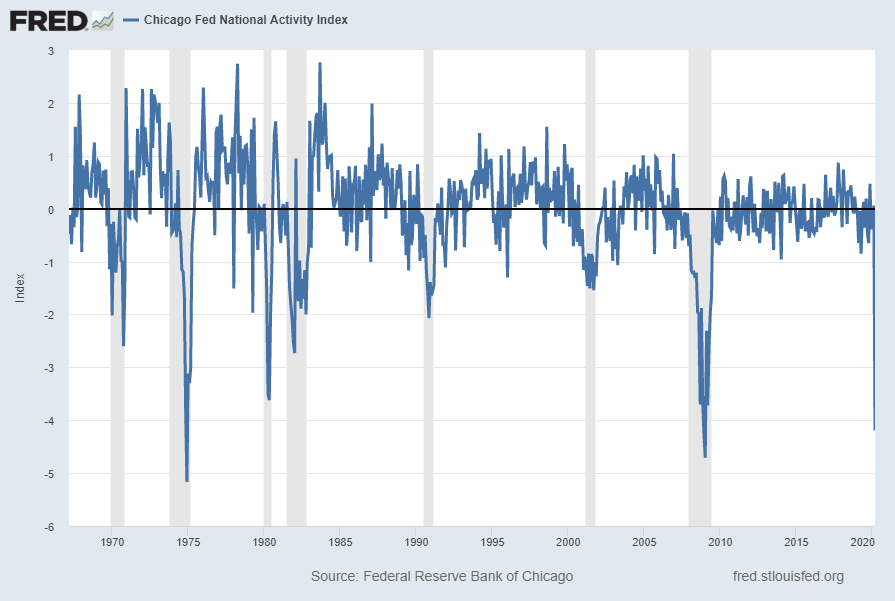
The April 2020 Chicago Fed National Activity Index (CFNAI) updated as of April 20, 2020:
The CFNAI, with current reading of -4.19:
CFNAI
source:  Federal Reserve Bank of Chicago, Chicago Fed National Activity Index [CFNAI], retrieved from FRED, Federal Reserve Bank of St. Louis, April 20, 2020;
https://fred.stlouisfed.org/series/CFNAI
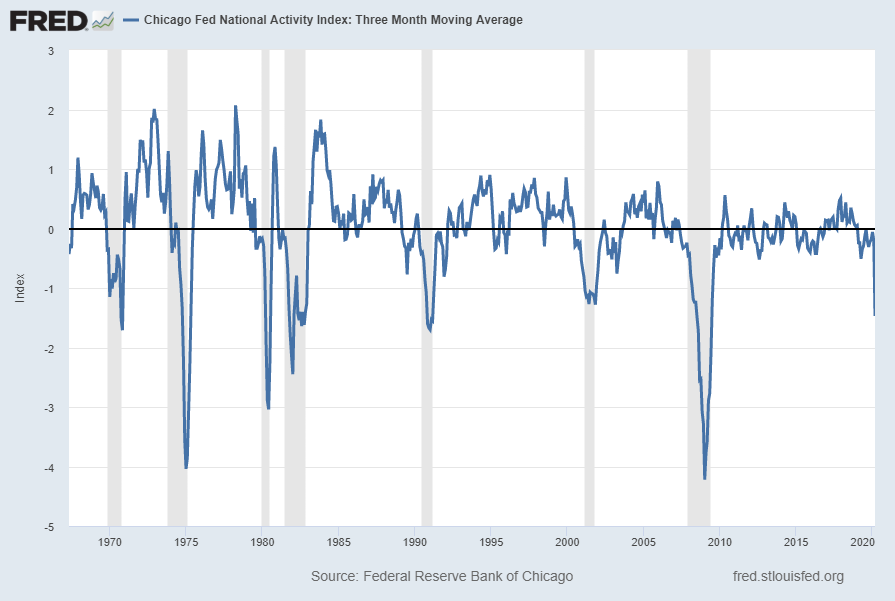
The CFNAI-MA3, with current reading of -1.47:
CFNAIMA3
source:  Federal Reserve Bank of Chicago, Chicago Fed National Activity Index: Three Month Moving Average [CFNAIMA3], retrieved from FRED, Federal Reserve Bank of St. Louis, April 20, 2020;
https://fred.stlouisfed.org/series/CFNAIMA3
–
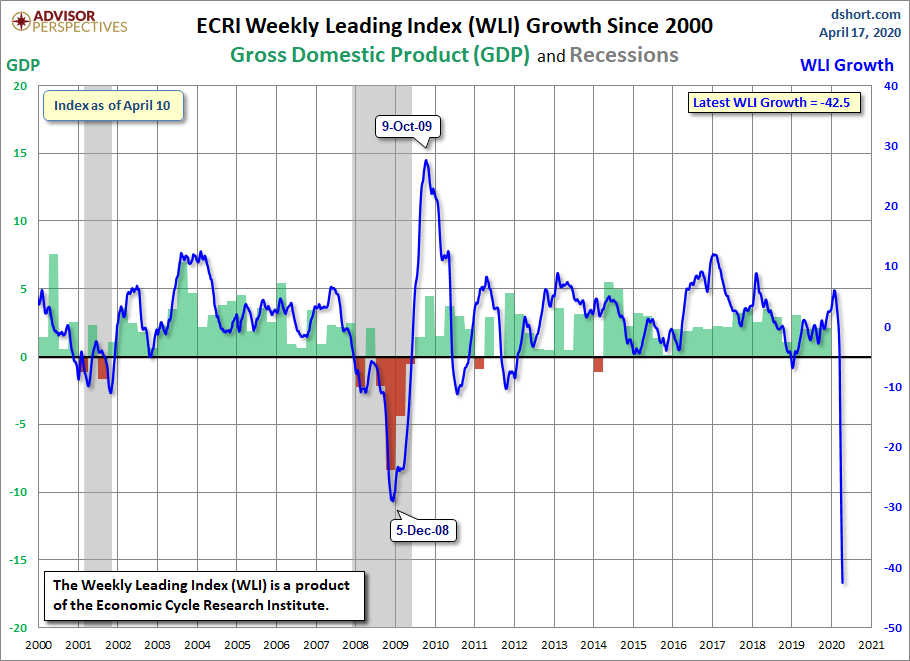
As of April 17, 2020 (incorporating data through April 10, 2020) the WLI was at 111.3 and the WLI, Gr. was at -42.5%.
A chart of the WLI,Gr., from the Advisor Perspectives’ ECRI update post of April 17, 2020:
ECRI WLI,Gr.
–
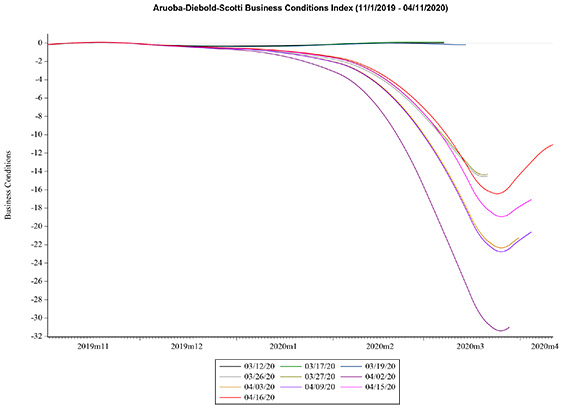
Below is the latest chart, depicting the ADS Index from November 1, 2019 through April 11, 2020:
ADS Index
–
The Conference Board Leading (LEI), Coincident (CEI) Economic Indexes, and Lagging Economic Indicator (LAG):
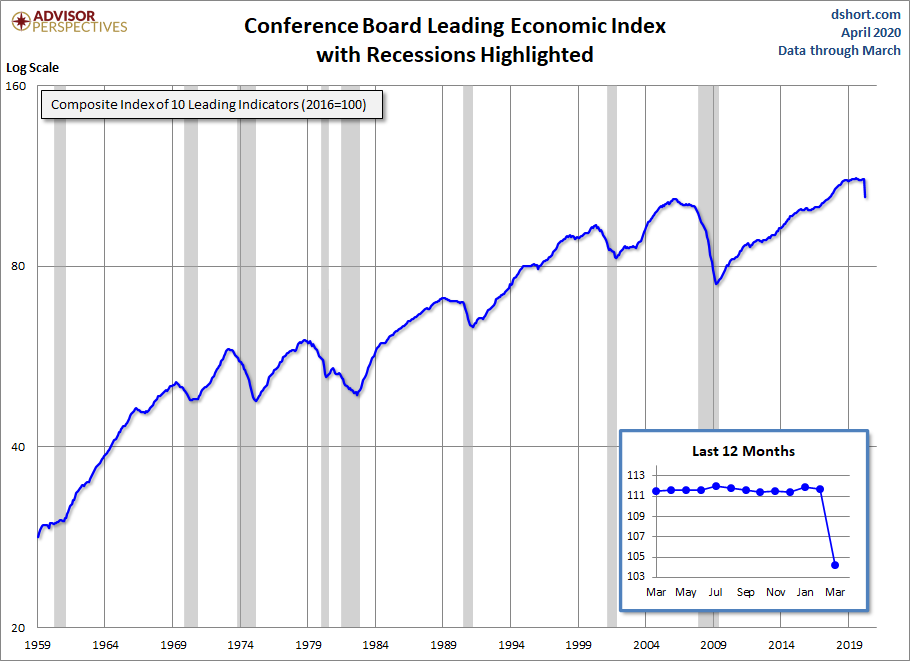
As per the April 17, 2020 Conference Board press release, titled “The Conference Board Leading Economic Index (LEI) for the U.S. Plummets in March” the LEI was at 104.2, the CEI was at 106.6, and the LAG was 110.2 in March.
An excerpt from the release:
“In March, the US LEI registered the largest decline in its 60-year history,” said Ataman Ozyildirim, Senior Director of Economic Research at The Conference Board. “The unprecedented and sudden deterioration was broad based, with the largest negative contributions coming from initial claims for unemployment insurance and stock prices. The sharp drop in the LEI reflects the sudden halting in business activity as a result of the global pandemic and suggests the US economy will be facing a very deep contraction.”
Here is a chart of the LEI from the Advisor Perspectives’ Conference Board Leading Economic Index update of April 17, 2020:
Conference Board LEI
_________
I post various indicators and indices because I believe they should be carefully monitored.  However, as those familiar with this site are aware, I do not necessarily agree with what they depict or imply.
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 2839.13 as this post is written

Friday, April 17, 2020

Long-Term Charts Of The ECRI WLI & ECRI WLI, Gr. – April 17, 2020 Update

As I stated in my July 12, 2010 post (“ECRI WLI Growth History“):
For a variety of reasons, I am not as enamored with ECRI’s WLI and WLI Growth measures as many are.
However, I do think the measures are important and deserve close monitoring and scrutiny.
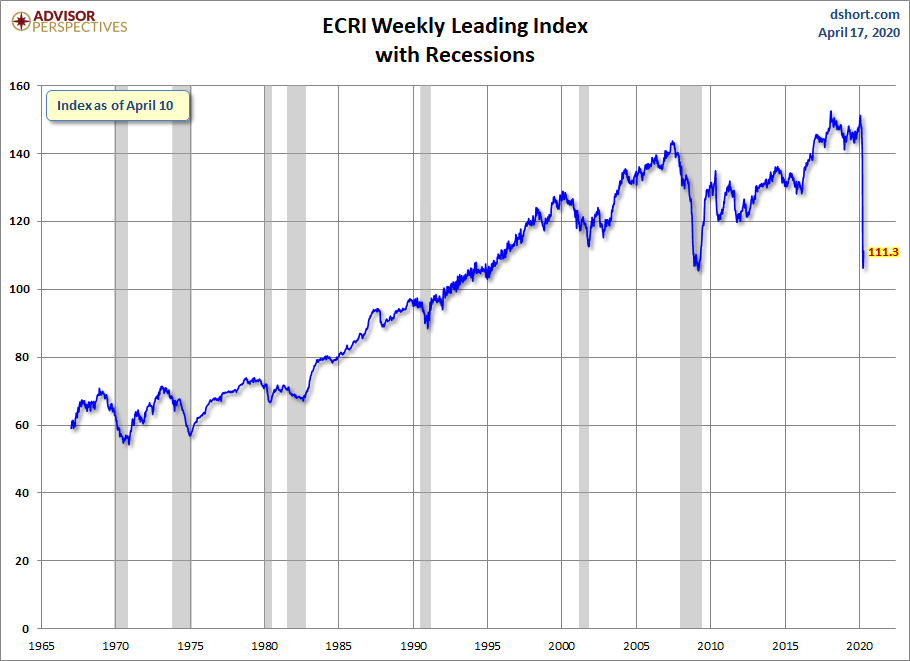
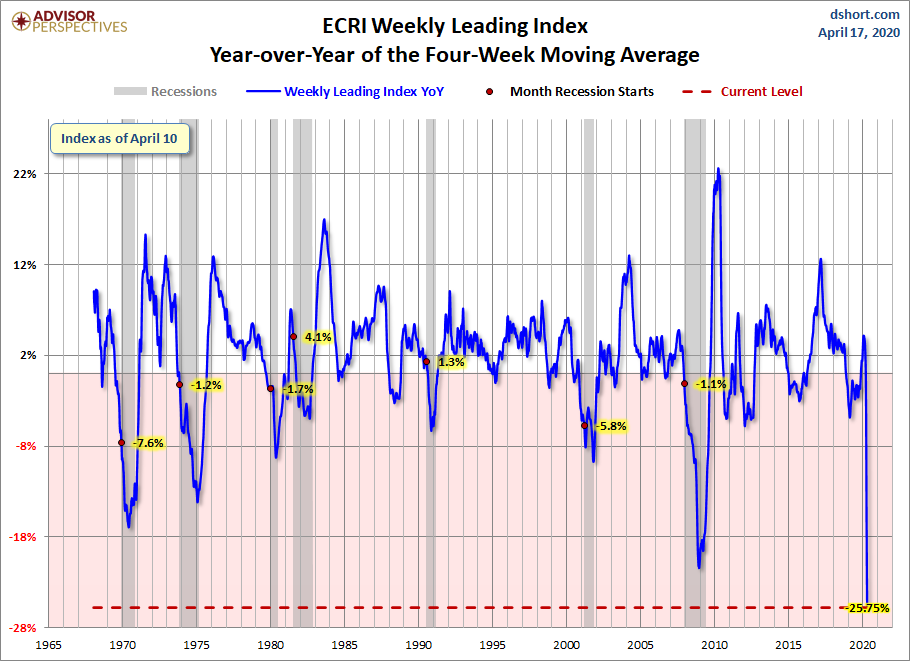
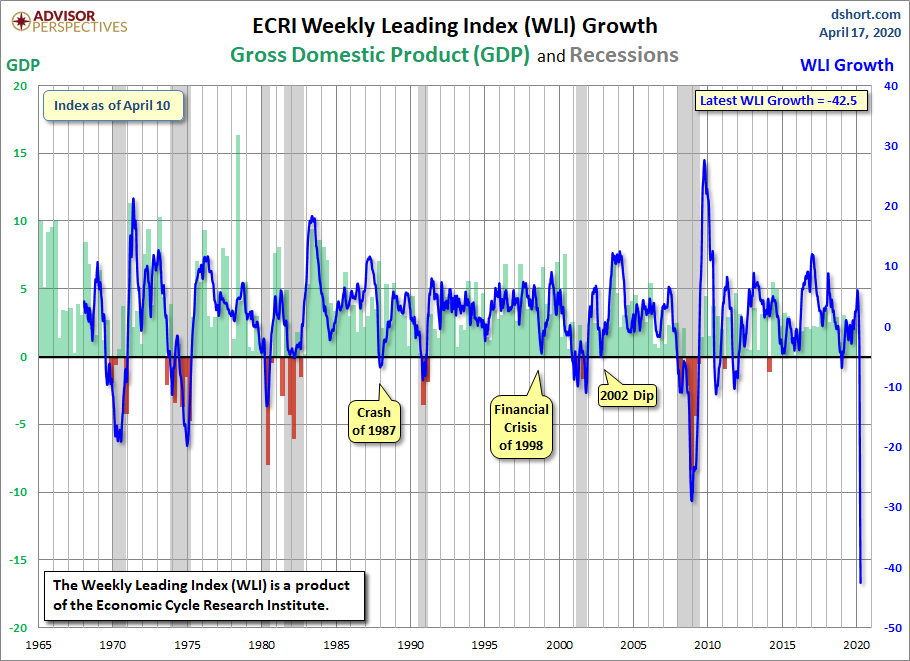
Below are three long-term charts, from Advisor Perspectives’ ECRI update post of April 17, 2020 titled “ECRI Weekly Leading Index Update.”  These charts are on a weekly basis through the April 17, 2020 release, indicating data through April 10, 2020.
Here is the ECRI WLI (defined at ECRI’s glossary):
ECRI WLI
–
This next chart depicts, on a long-term basis, the Year-over-Year change in the 4-week moving average of the WLI:
ECRI YoY of the Four-Week Moving Average
–
This last chart depicts, on a long-term basis, the WLI, Gr.:
ECRI WLI,Gr. -42.5
_________
I post various economic indicators and indices because I believe they should be carefully monitored.  However, as those familiar with this site are aware, I do not necessarily agree with what they depict or imply.
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 2841.43 as this post is written