Sunday, July 17, 2022

The July 2022 Wall Street Journal Economic Forecast Survey

The July 2022 Wall Street Journal Economic Forecast Survey was published on July 17, 2022. The headline is “As Fed Tightens, Economists Worry It Will Go Too Far.”

I found numerous items to be notable – although I don’t necessarily agree with them – both within the article and in the forecasts section.

An excerpt:

Economists increasingly expect the Federal Reserve, in its efforts to push down inflation, to raise rates enough to trigger a recession, with many worrying the central bank will go too far.

Economists surveyed by The Wall Street Journal now put the chance of a recession sometime in the next 12 months at 49% in July, on average, up from 44% a month ago and just 18% in January.

Some 46% of economists said they expect the Fed to raise interest rates excessively and cause unnecessary economic weakness. Slightly fewer, 42%, said they anticipated the Fed increasing rates about the right amount to balance inflation and growth. Around 12.3% thought it would raise rates too little.

As noted above, and also seen in the “Recession Probability” section, the average response as to whether the economy will be in a recession within the next 12 months was 49%. The individual estimates, of those who responded, ranged from 1% to 99%.  For reference, the average response in June’s survey [the previously published survey] was 44%.

As stated in the article, the survey’s 62 respondents were academic, financial and business economists.  The survey was conducted July 8 – July 12. Not every economist answered every question.

–

Economic Forecasts

The current average forecasts among economists polled include the following:

GDP:

full-year 2022:  .71%

full-year 2023:  1.14%

full-year 2024:  2.05%

Unemployment Rate:

December 2022: 3.76%

December 2023: 4.28%

December 2024: 4.35%

10-Year Treasury Yield:

December 2022: 3.32%

December 2023: 3.22%

December 2024: 3.17%

CPI:

December 2022:  6.85%

December 2023:  2.93%

December 2024:  2.31%

Core PCE:

full-year 2022:  4.47%

full-year 2023:  2.93%

full-year 2024:  2.32%

(note: I have highlighted this WSJ Economic Forecast survey each time it is published; it was published monthly until April 2021, after which the survey is conducted (at least) every three months; commentary on past surveys can be found under the “Economic Forecasts” label)

_____

I post various economic forecasts because I believe they should be carefully monitored.  However, as those familiar with this site are aware, I do not necessarily agree with many of the consensus estimates and much of the commentary in these forecast surveys.

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 3863.16 as this post is written

Friday, July 15, 2022

Long-Term Charts Of The ECRI WLI & ECRI WLI, Gr. – July 15, 2022 Update

As I stated in my July 12, 2010 post (“ECRI WLI Growth History“):

For a variety of reasons, I am not as enamored with ECRI’s WLI and WLI Growth measures as many are.

However, I do think the measures are important and deserve close monitoring and scrutiny.

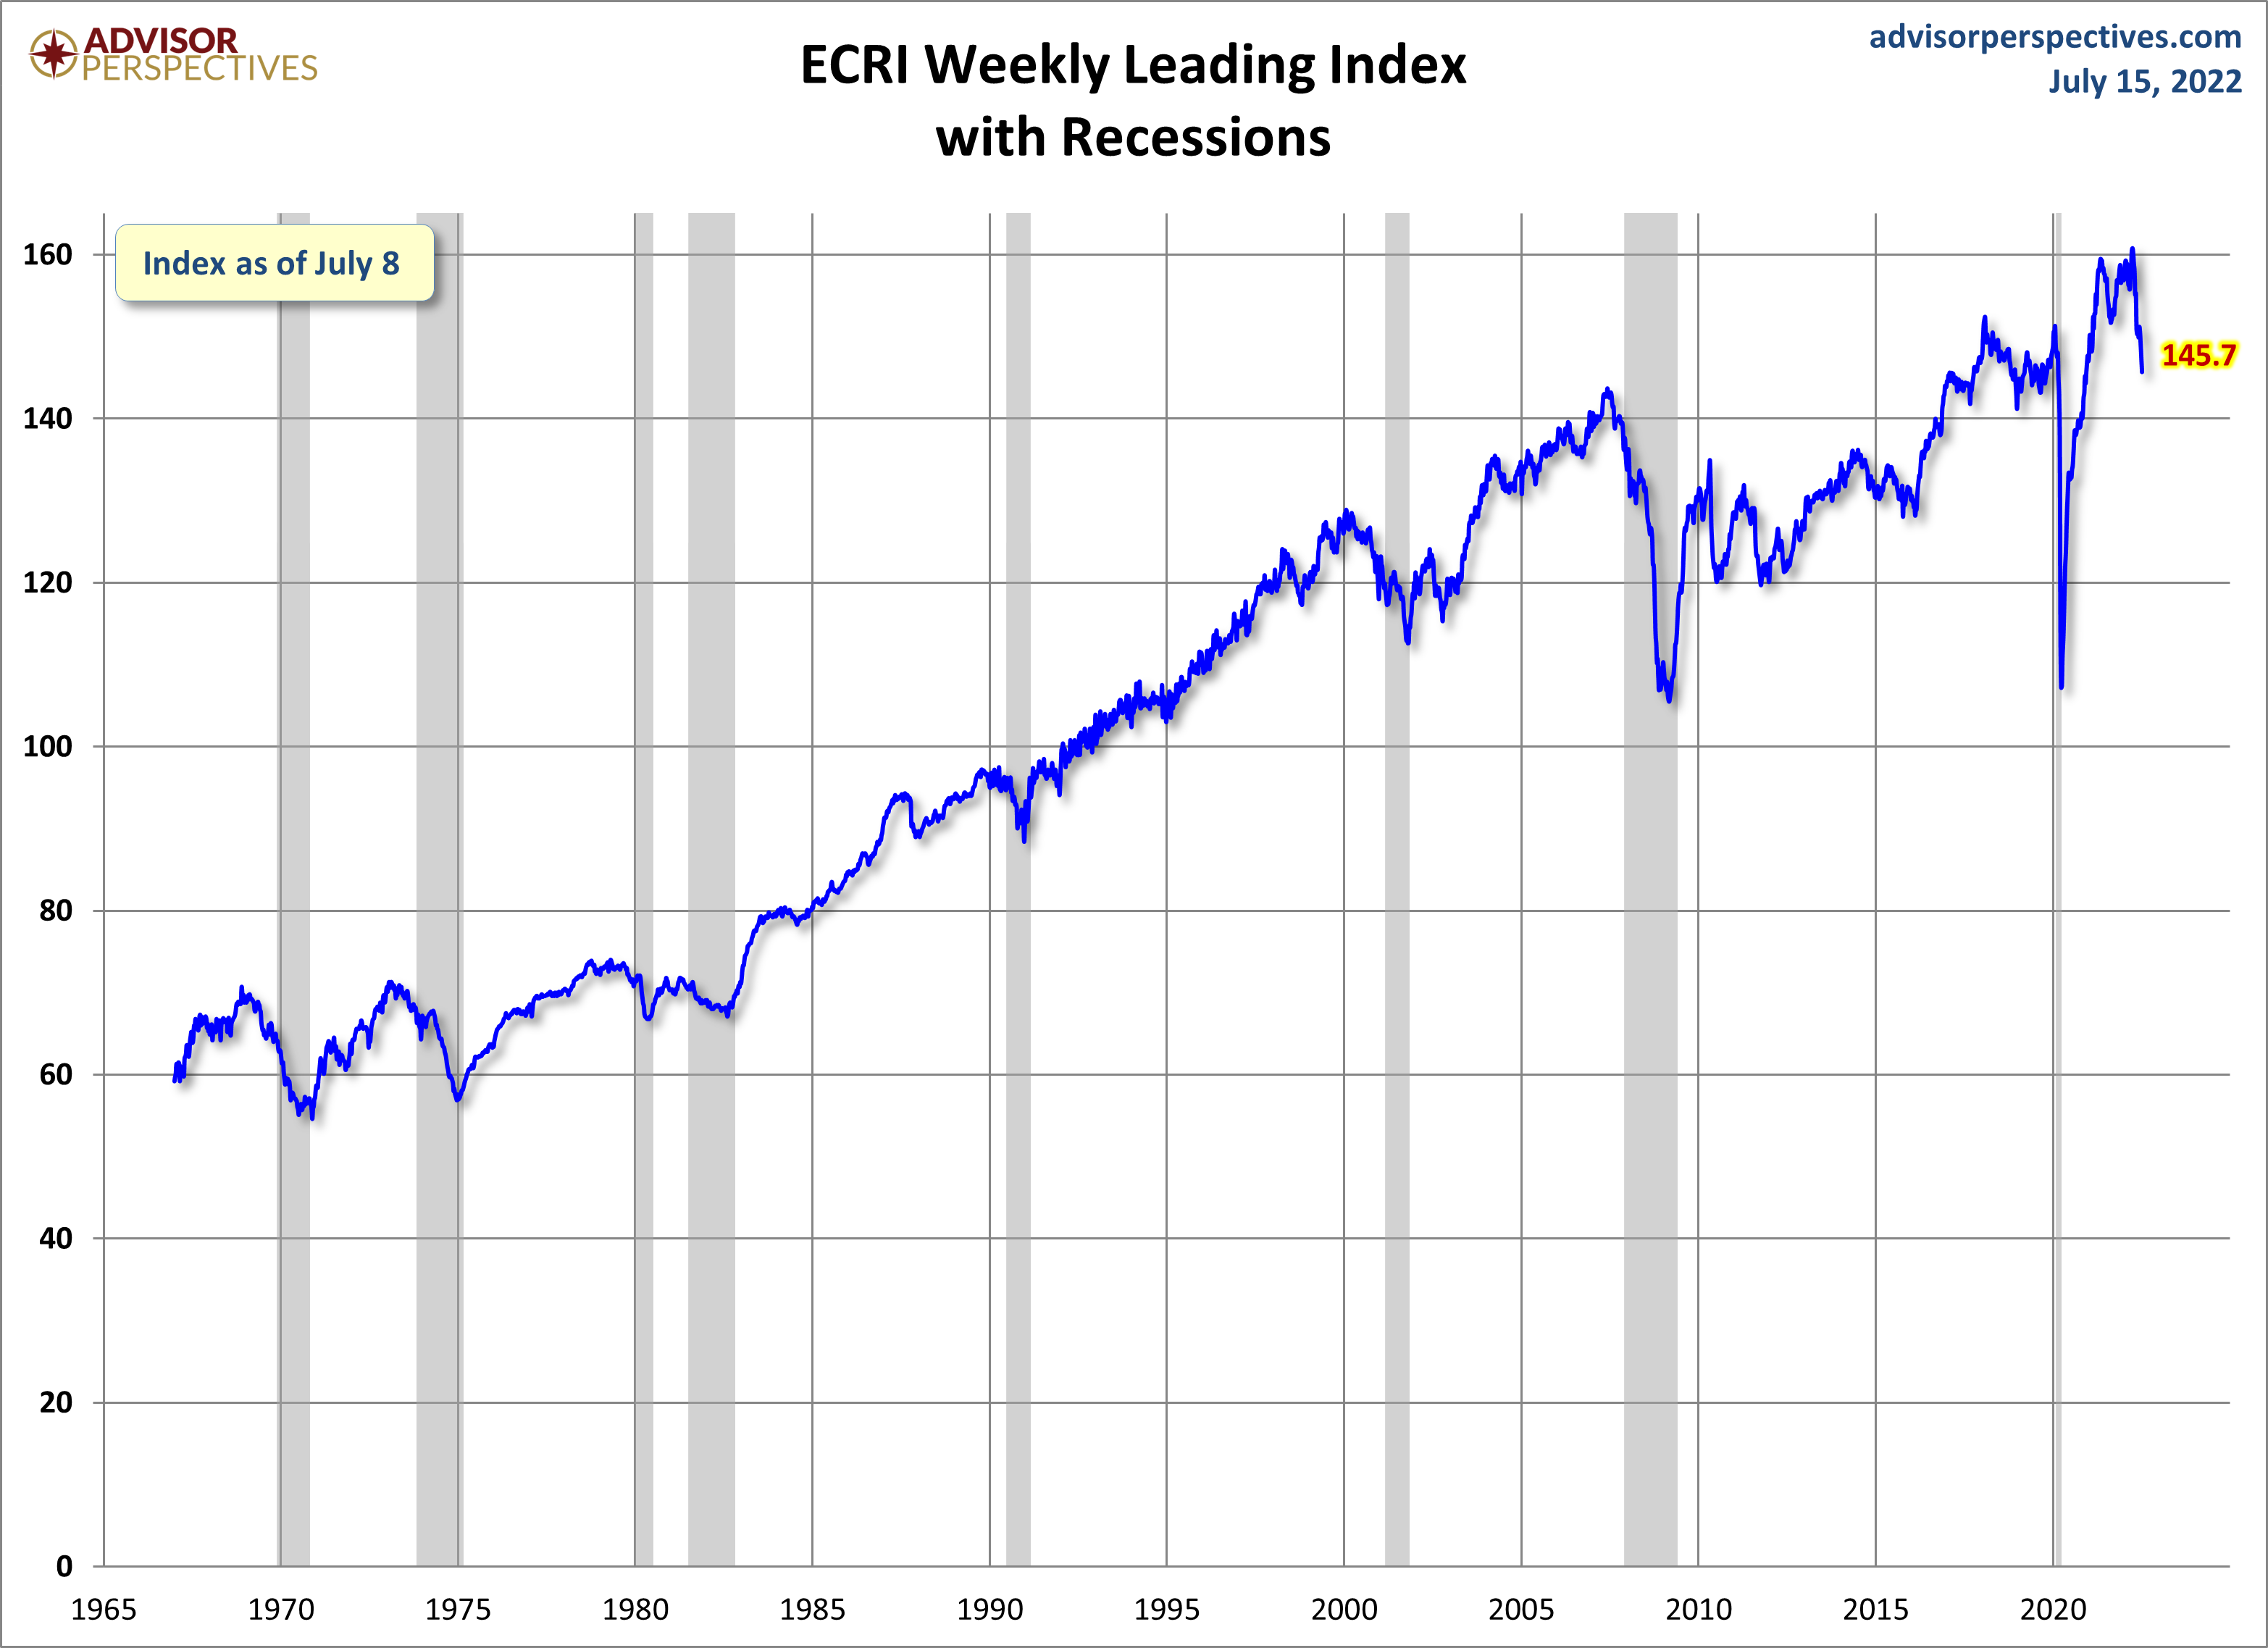
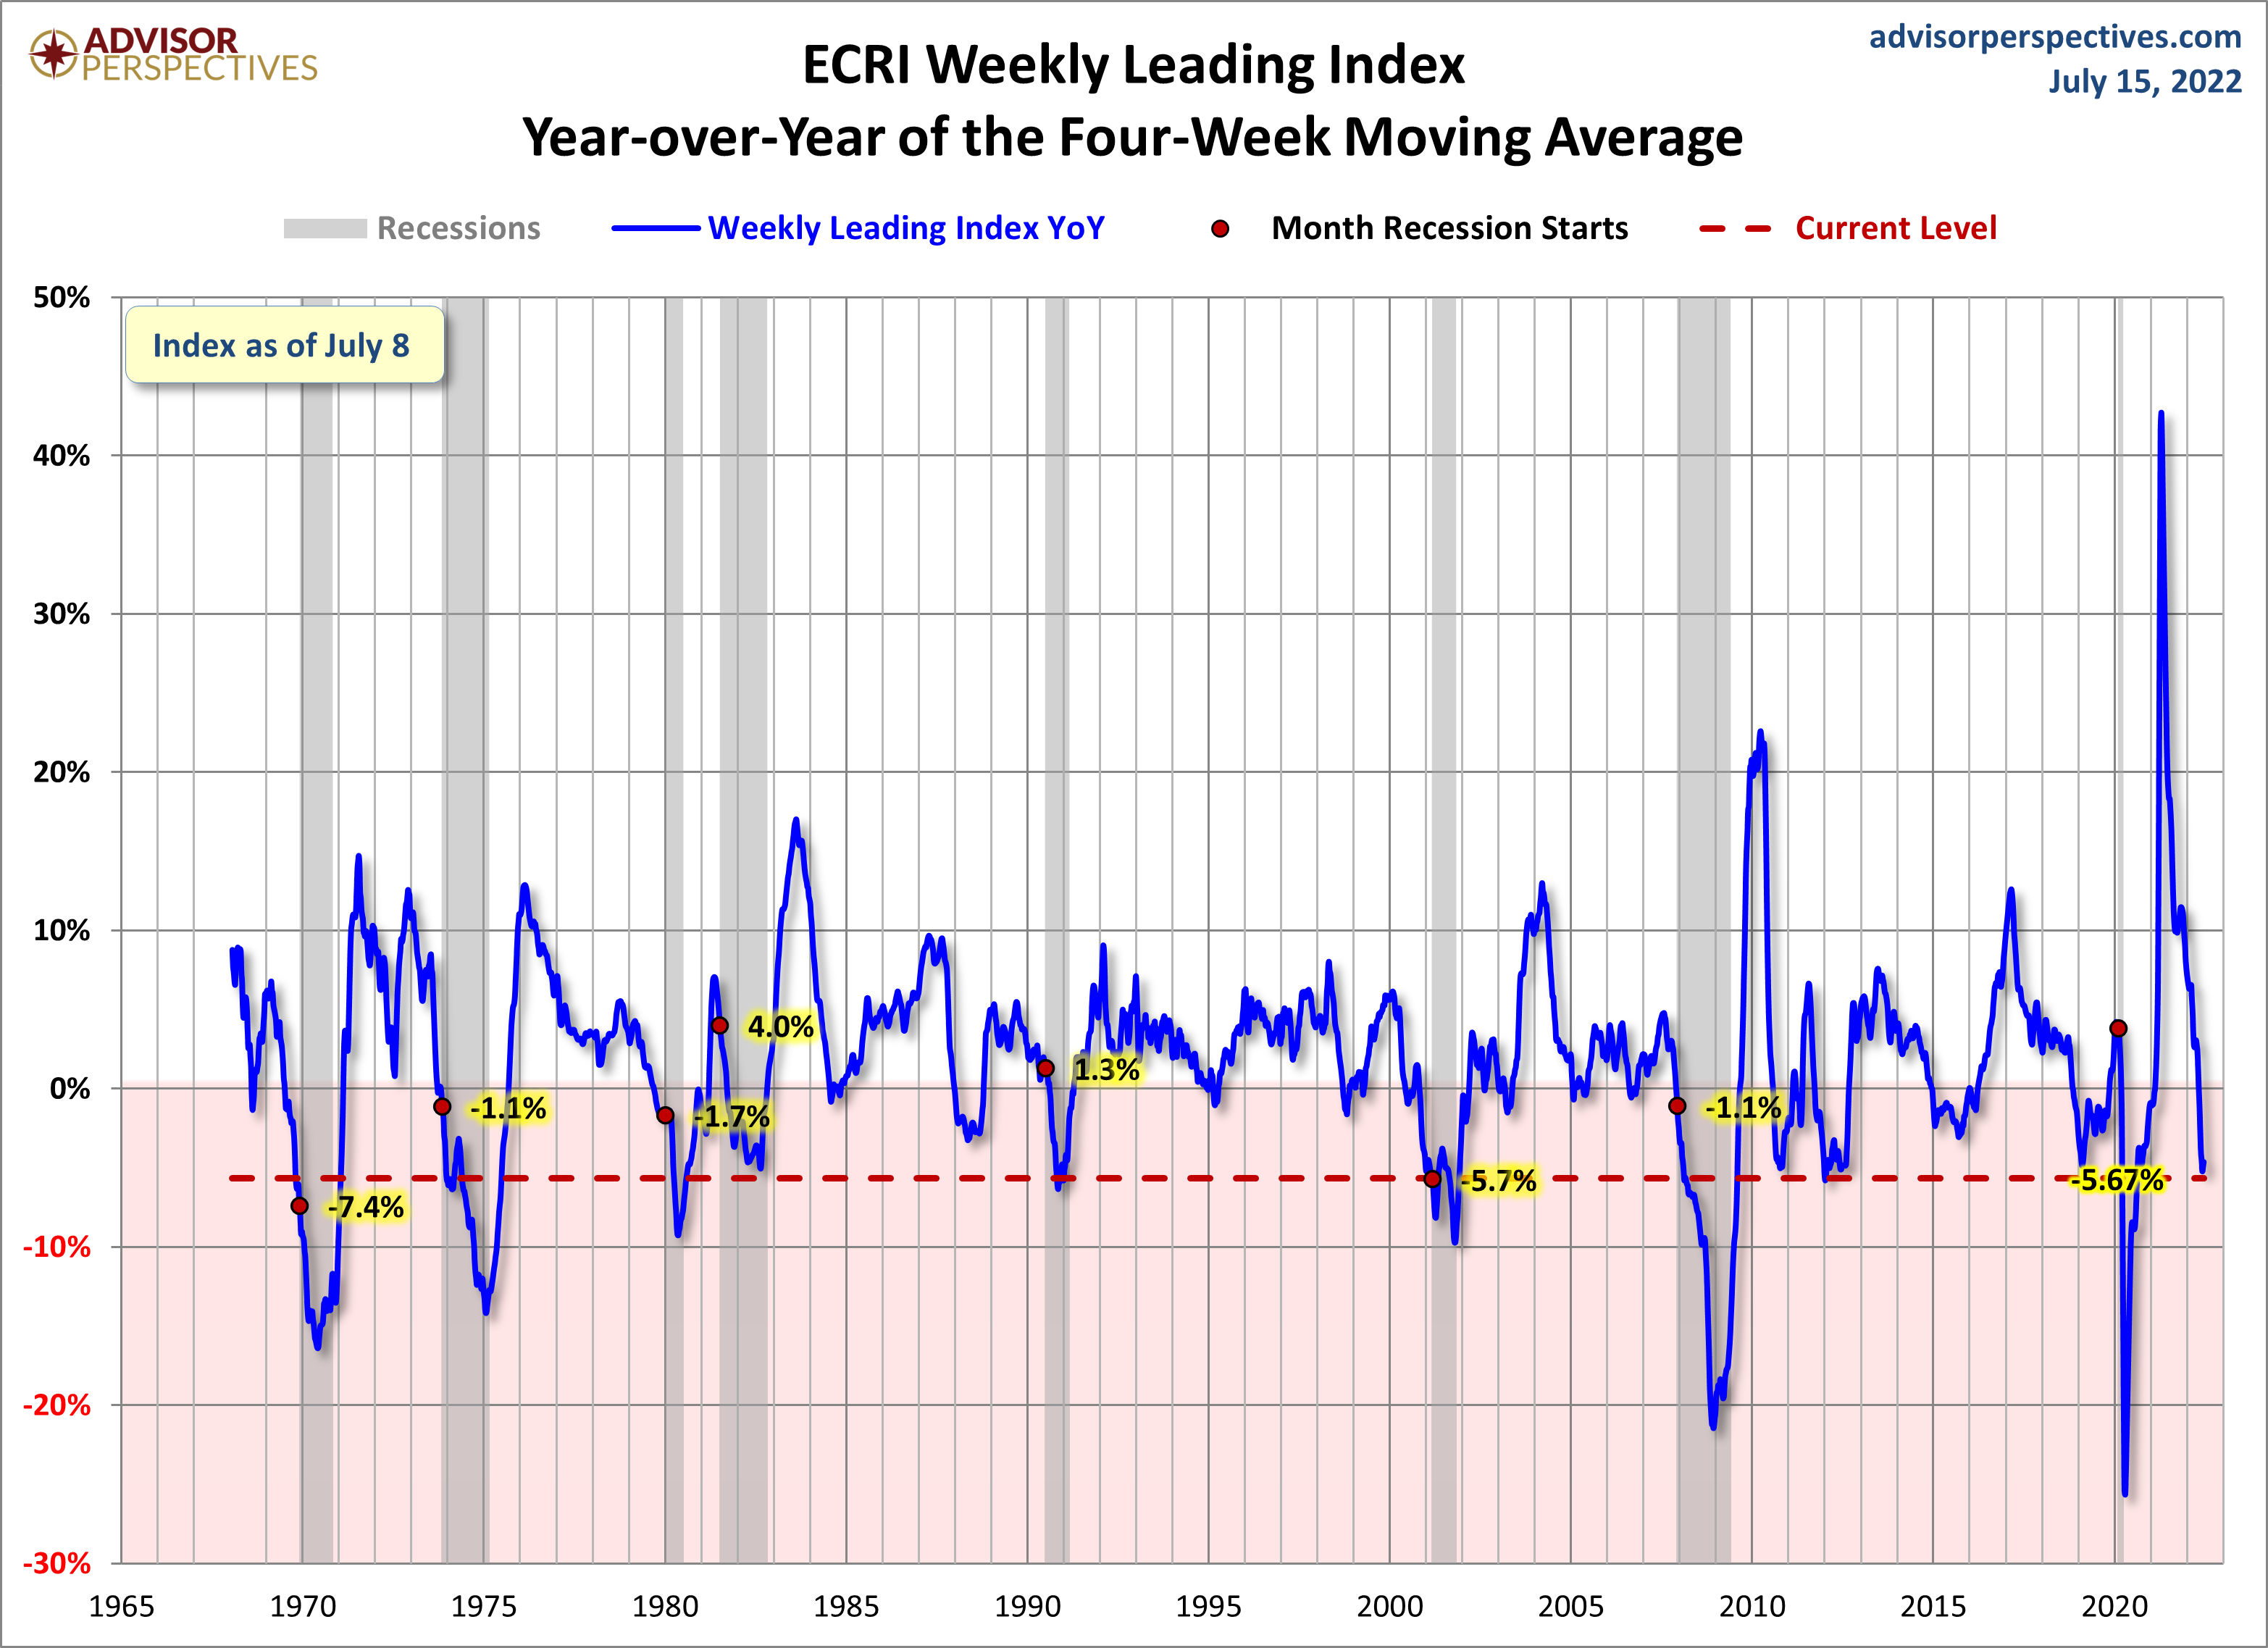
Below are three long-term charts, from Advisor Perspectives’ ECRI update post of July 15, 2022 titled “ECRI Weekly Leading Index Update.”  These charts are on a weekly basis as of the July 15, 2022 release, reflecting data through July 8, 2022.

Here is the ECRI WLI (defined at ECRI’s glossary):

ECRI WLI 145.7

–

This next chart depicts, on a long-term basis, the Year-over-Year change in the 4-week moving average of the WLI:

ECRI WLI YoY of the Four-Week Moving Average

–

This last chart depicts, on a long-term basis, the WLI, Gr.:

ECRI WLI,Gr. -9.1 Percent

_________

I post various economic indicators and indices because I believe they should be carefully monitored.  However, as those familiar with this site are aware, I do not necessarily agree with what they depict or imply.

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 3854.95 as this post is written 

Disturbing Charts (Update 46)

The following is the latest update of 10 charts that depict various aspects of the U.S. economic and financial situation.

I find these charts portray disturbing long-term trends. These trends have been in effect for years.

These charts raise a lot of questions.  As well, they highlight the “atypical” nature of our economic situation from a long-term historical perspective.

All of these charts are from the Federal Reserve, and represent the most recently updated data.

(click on charts to enlarge images)

Housing starts (last update June 16, 2022):

Housing Starts 1549

U.S. Bureau of the Census, Housing Starts: Total: New Privately Owned Housing Units Started [HOUST], retrieved from FRED, Federal Reserve Bank of St. Louis https://research.stlouisfed.org/fred2/series/HOUST/, July 14, 2022.

–

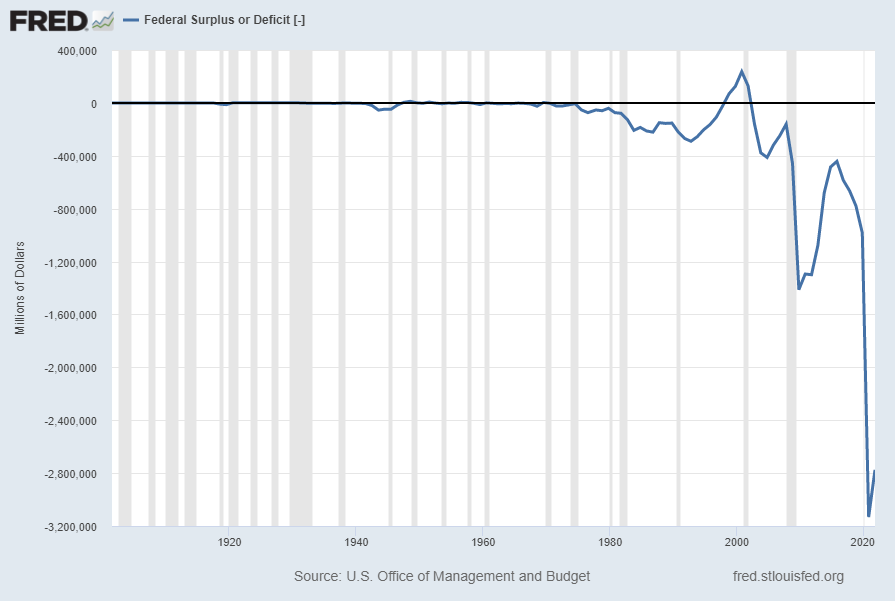
The Federal Deficit (last updated April 1, 2022):

Federal Deficit -2775337

U.S. Office of Management and Budget, Federal Surplus or Deficit [-] [FYFSD], retrieved from FRED, Federal Reserve Bank of St. Louis https://research.stlouisfed.org/fred2/series/FYFSD/, July 14, 2022.

–

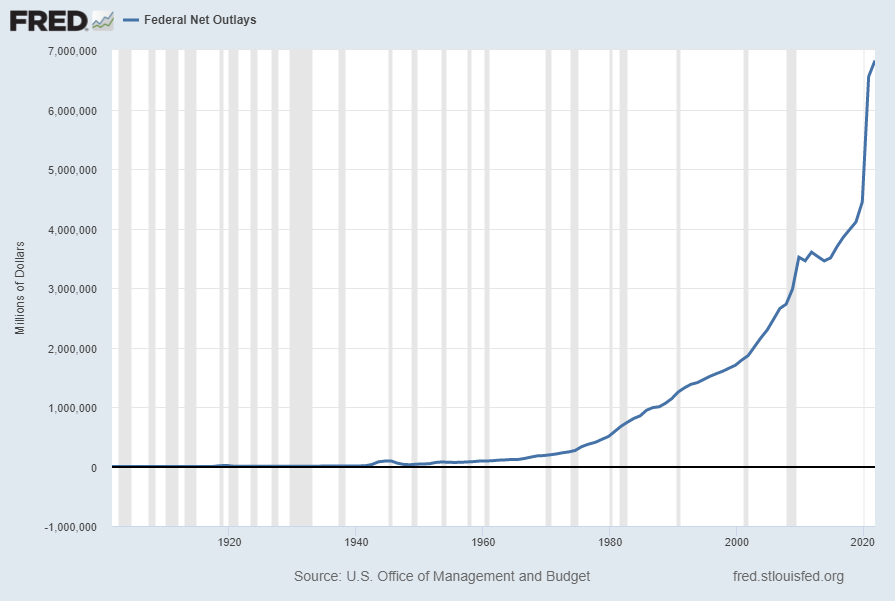
Federal Net Outlays (last updated April 1, 2022):

Federal Net Outlays 6822449

U.S. Office of Management and Budget, Federal Net Outlays [FYONET], retrieved from FRED, Federal Reserve Bank of St. Louis https://research.stlouisfed.org/fred2/series/FYONET/, July 14, 2022.

–

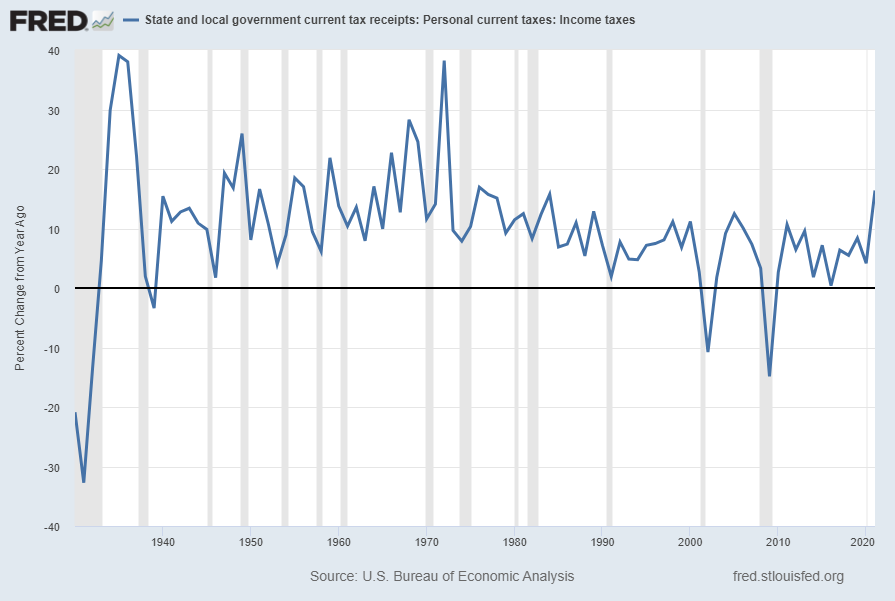
State & Local Personal Income Tax Receipts (% Change from Year Ago)(last updated March 30, 2022):

State & Local Personal Income Tax Receipts Percent Change From Year Ago

U.S. Bureau of Economic Analysis, State and local government current tax receipts: Personal current taxes: Income taxes [ASLPITAX], retrieved from FRED, Federal Reserve Bank of St. Louis https://research.stlouisfed.org/fred2/series/ASLPITAX/, July 14, 2022.

–

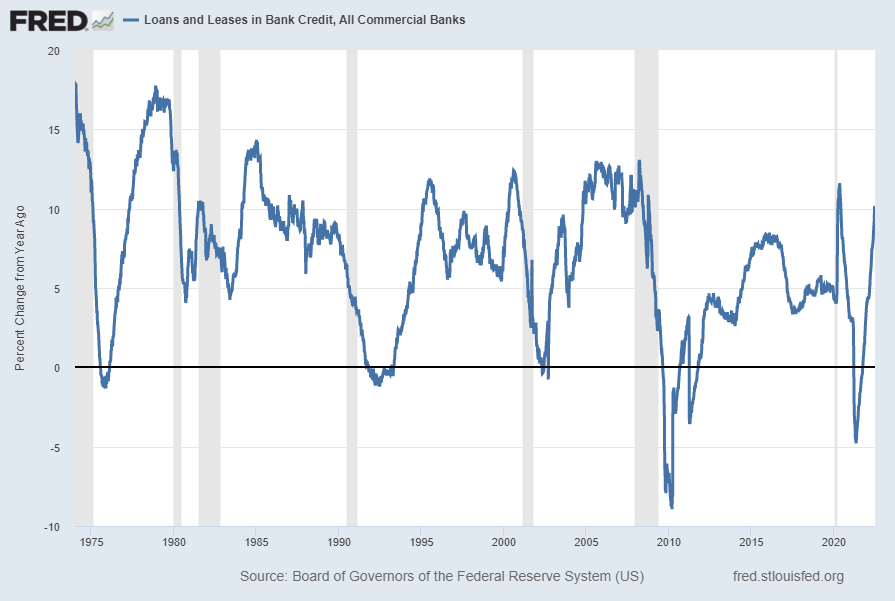
Total Loans and Leases of Commercial Banks (% Change from Year Ago)(last updated July 8, 2022):

Loans and Leases in Bank Credit, All Commercial Banks 10.0 Percent Change From Year Ago

Board of Governors of the Federal Reserve System (US), Loans and Leases in Bank Credit, All Commercial Banks [TOTLL], retrieved from FRED, Federal Reserve Bank of St. Louis https://research.stlouisfed.org/fred2/series/TOTLL/, July 14, 2022.

–

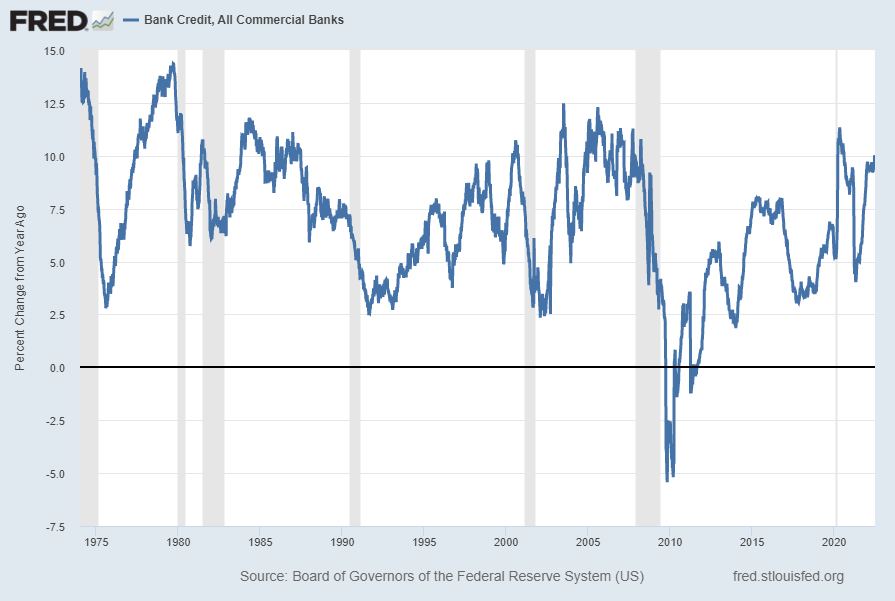
Bank Credit – All Commercial Banks (% Change from Year Ago)(last updated July 8, 2022):

Bank Credit - All Commercial Banks 9.9 Percent Change From Year Ago

Board of Governors of the Federal Reserve System (US), Bank Credit of All Commercial Banks [TOTBKCR], retrieved from FRED, Federal Reserve Bank of St. Louis https://research.stlouisfed.org/fred2/series/TOTBKCR/, July 14, 2022.

–

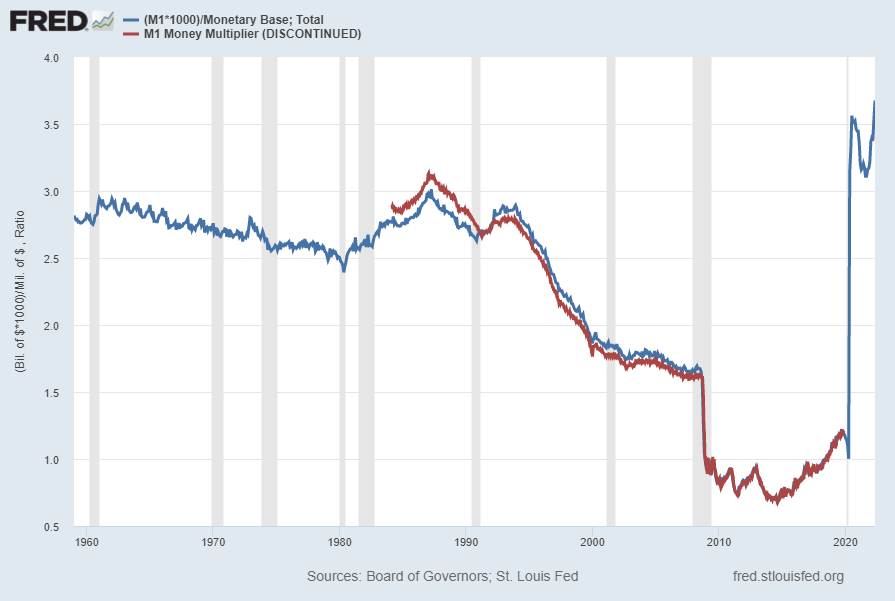
M1 Money Multiplier Proxy:

M1 Money Multiplier Proxy 3.67512

Federal Reserve Bank of St. Louis, M1 Money Multiplier [MULT], retrieved from FRED, Federal Reserve Bank of St. Louis https://research.stlouisfed.org/fred2/series/MULT/, July 14, 2022.

–

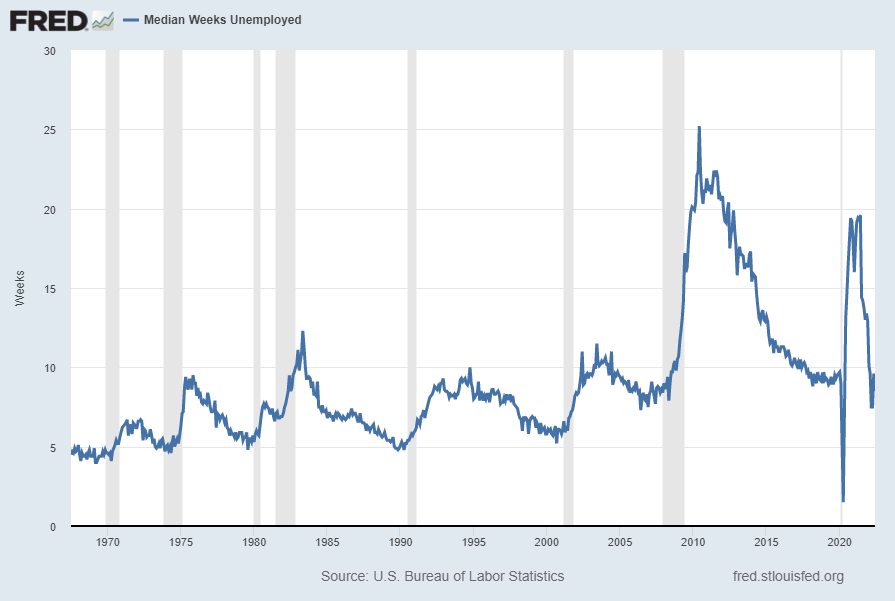
Median Duration of Unemployment (last updated July 8, 2022):

Median Duration Of Unemployment 8.5 weeks

U.S. Bureau of Labor Statistics, Median Duration of Unemployment [UEMPMED], retrieved from FRED, Federal Reserve Bank of St. Louis https://research.stlouisfed.org/fred2/series/UEMPMED/, July 14, 2022.

–

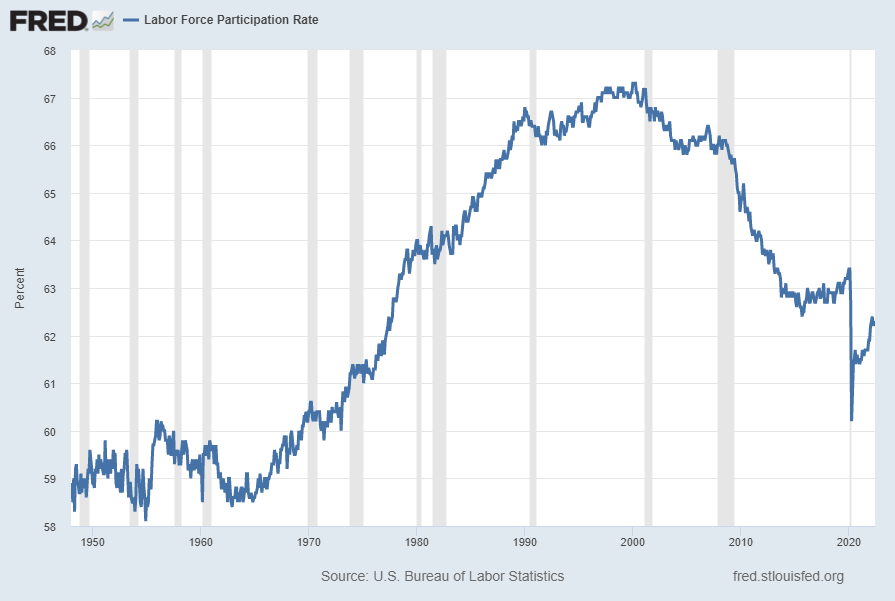
Labor Force Participation Rate (last updated July 8, 2022):

Labor Force Participation Rate 62.2 Percent

U.S. Bureau of Labor Statistics, Civilian Labor Force Participation Rate [CIVPART], retrieved from FRED, Federal Reserve Bank of St. Louis https://research.stlouisfed.org/fred2/series/CIVPART/, July 14, 2022.

–

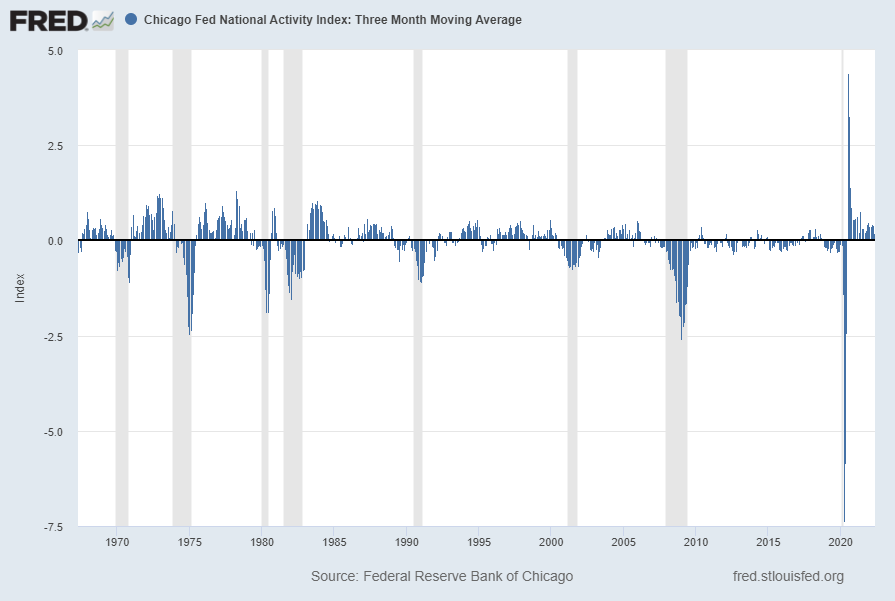
The Chicago Fed National Activity Index (CFNAI) Three Month Moving Average (CFNAI-MA3)(last updated June 21, 2022):

CFNAIMA3 .2

Federal Reserve Bank of Chicago, Chicago Fed National Activity Index: Three Month Moving Average [CFNAIMA3], retrieved from FRED, Federal Reserve Bank of St. Louis https://research.stlouisfed.org/fred2/series/CFNAIMA3/, July 14, 2022.

–

I will continue to update these charts on an intermittent basis as they deserve close monitoring…

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 3790.38 as this post is written

Thursday, July 14, 2022

Chicago Fed National Financial Conditions Index (NFCI)

The St. Louis Fed’s Financial Stress Index (STLFSI3) is one index that is supposed to measure stress in the financial system. Its reading as of the July 14, 2022 update (reflecting data through July 8, 2022) is -1.3021:

STLFSI3

source: Federal Reserve Bank of St. Louis, St. Louis Fed Financial Stress Index [STLFSI3], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed July 14, 2022: https://fred.stlouisfed.org/series/STLFSI3

Of course, there are a variety of other measures and indices that are supposed to measure financial stress and other related issues, both from the Federal Reserve as well as from private sources.

Two other indices that I regularly monitor include the Chicago Fed National Financial Conditions Index (NFCI) as well as the Chicago Fed Adjusted National Financial Conditions Index (ANFCI).

Here are summary descriptions of each, as seen in FRED:

The National Financial Conditions Index (NFCI) measures risk, liquidity and leverage in money markets and debt and equity markets as well as in the traditional and “shadow” banking systems. Positive values of the NFCI indicate financial conditions that are tighter than average, while negative values indicate financial conditions that are looser than average.

The adjusted NFCI (ANFCI). This index isolates a component of financial conditions uncorrelated with economic conditions to provide an update on how financial conditions compare with current economic conditions.

For further information, please visit the Federal Reserve Bank of Chicago’s web site:

http://www.chicagofed.org/webpages/publications/nfci/index.cfm

Below are the most recently updated charts of the NFCI and ANFCI, respectively.

The NFCI chart below was last updated on July 13, 2022 incorporating data from January 8, 1971 through July 8, 2022 on a weekly basis.  The July 8 value is -.09113:

NFCI -.09113

Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis; accessed July 14, 2022:  
http://research.stlouisfed.org/fred2/series/NFCI

–

The ANFCI chart below was last updated on July 13, 2022 incorporating data from January 8, 1971 through July 8, 2022, on a weekly basis.  The July 8, 2022 value is .15599:

ANFCI .15599

Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis; accessed July 14, 2022:  
http://research.stlouisfed.org/fred2/series/ANFCI

_________

I post various indicators and indices because I believe they should be carefully monitored.  However, as those familiar with this site are aware, I do not necessarily agree with what they depict or imply.

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 3787.38 as this post is written

Wednesday, July 13, 2022

Recession Probability Models – July 2022

There are a variety of economic models that are supposed to predict the probabilities of recession.

While I don’t agree with the methodologies employed or probabilities of impending economic weakness as depicted by the following two models, I think the results of these models should be monitored.

Please note that each of these models is updated regularly, and the results of these – as well as other recession models – can fluctuate significantly.

The first is the “Yield Curve as a Leading Indicator” from the New York Federal Reserve.  I wrote a post concerning this measure on March 1, 2010, titled “The Yield Curve as a Leading Indicator.”

Currently (last updated July 11, 2022 using data through June 2022) this “Yield Curve” model shows a 5.9258% probability of a recession in the United States twelve months ahead.  For comparison purposes, it showed a 4.1063% probability through May 2022, and a chart going back to 1960 is seen at the “Probability Of U.S. Recession Predicted by Treasury Spread.” (pdf)

The second model is from Marcelle Chauvet and Jeremy Piger.  This model is described on the St. Louis Federal Reserve site (FRED) as follows:

Smoothed recession probabilities for the United States are obtained from a dynamic-factor markov-switching model applied to four monthly coincident variables: non-farm payroll employment, the index of industrial production, real personal income excluding transfer payments, and real manufacturing and trade sales. This model was originally developed in Chauvet, M., “An Economic Characterization of Business Cycle Dynamics with Factor Structure and Regime Switching,” International Economic Review, 1998, 39, 969-996. (http://faculty.ucr.edu/~chauvet/ier.pdf)

Additional details and explanations can be seen on the “U.S. Recession Probabilities” page.

This model, last updated on July 1, 2022 currently shows a .48% probability using data through June 2022.

Here is the FRED chart (last updated July 1, 2022):

Smoothed U.S. Recession Probabilities

Data Source:  Piger, Jeremy Max and Chauvet, Marcelle, Smoothed U.S. Recession Probabilities [RECPROUSM156N], retrieved from FRED, Federal Reserve Bank of St. Louis, accessed July 13, 2022:  
http://research.stlouisfed.org/fred2/series/RECPROUSM156N

–

The two models featured above can be compared against measures seen in recent posts.  For instance, as seen in the June 21, 2022 post titled “The June 2022 Wall Street Journal Economic Forecast Survey“ economists surveyed averaged a 44% probability of a U.S. recession within the next 12 months.

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 3815.51 as this post is written

Friday, July 8, 2022

Average Hourly Earnings Trends

I have written many blog posts concerning the worrisome trends in income and earnings.

Along these lines, one of the measures showing disconcerting trends is that of hourly earnings.

While the concept of hourly earnings can be defined and measured in a variety of ways, below are a few charts that I believe broadly illustrate problematic trends.

The first chart depicts Average Hourly Earnings Of All Employees: Total Private (FRED series CES0500000003)(current value = $32.08):

(click on chart to enlarge image)(chart last updated 7-8-22)

CES0500000003

Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis: Average Hourly Earnings of All Employees:  Total Private [CES0500000003] ; U.S. Department of Labor: Bureau of Labor Statistics; accessed July 8, 2022: 
http://research.stlouisfed.org/fred2/series/CES0500000003

–

This next chart depicts this same measure on a “Percentage Change From A Year Ago” basis.   While not totally surprising, I find the decline from 2009 and subsequent trend to be disconcerting:

(click on chart to enlarge image)(chart last updated 7-8-22)

CES0500000003 Percent Change From Year Ago

–

There are slightly different measures available from a longer-term perspective. Pictured below is another measure, the Average Hourly Earnings of Production and Nonsupervisory Employees – Total Private (FRED series AHETPI)(current value = $27.45):

(click on chart to enlarge image)(chart last updated 7-8-22)

AHETPI

Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis: Average Hourly Earnings of Production and Nonsupervisory Employees:  Total Private [AHETPI] ; U.S. Department of Labor: Bureau of Labor Statistics;  accessed July 8, 2022: 
http://research.stlouisfed.org/fred2/series/AHETPI

–

Pictured below is this AHETPI measure on a “Percentage Change From A Year Ago” basis.   While not totally surprising, I find the decline from 2009 and subsequent trend to be disconcerting:

(click on chart to enlarge image)(chart last updated 7-8-22)

AHETPI 27.45

–

I will continue to actively monitor these trends, especially given the post-2009 dynamics.

_________

I post various economic indicators and indices because I believe they should be carefully monitored.  However, as those familiar with this site are aware, I do not necessarily agree with what they depict or imply.

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 3891.30 as this post is written