Showing posts with label asset bubbles. Show all posts

Sunday, October 5, 2025

The Stock Market Bubble – October 2025 Update

This post is a brief update to various past commentaries concerning the stock market bubble, most notably the February 2020 page titled “The Immense Stock Market Bubble And Characteristics.”

The stock market bubble continues to grow in size, which is highly notable given the enormous size of the bubble during February 2020. My analyses indicate that this stock market bubble is the largest stock market bubble ever in the United States. As well, another problematic aspect is that the stock market bubble is just one of many exceedingly large asset bubbles in existence. The existence of these astoundingly large asset bubbles poses a grave risk to the financial system and economy.

I have written extensively concerning the stock market bubble, its causes, and current and future consequences. It should be noted that a fully comprehensive discussion would be exceedingly lengthy and at times very complex. Perhaps the paramount aspects of this stock market bubble is that, for various reasons, it is far larger than most conventional measures would suggest; and that the future consequences of the “bursting” of the bubble will be highly problematical on many fronts.

As stated in the February 2020 commentary, one of the foremost signs of asset bubbles is excessive sentiment. Excessive sentiment can manifest in many ways. The current stock market environment exhibits a broad array of excessively positive sentiment. This excessively positive sentiment is often referred to as excessive speculation or “froth.” The stock market is experiencing an epochal speculative mania.

There are many different measures that portray the (vastly) oversized nature of the bubble from a valuation perspective. Here is a chart showing the “Market Cap/GVA” as seen in the September 2025 Hussman market commentary (further explained on that site):

Market Cap/GVA

In the February 2020 commentary I displayed a variety of long-term charts that depicted notable fundamental and technical measures. Below is an update to three of those charts, the S&P500, the XLK ETF, and the Nasdaq 100.

Shown below is the S&P500 daily chart since 1990, with prices displayed on a linear scale on the top plot and a LOG scale on the bottom plot:

(click on charts to enlarge images)(charts courtesy of StockCharts.com; chart creation and annotation by the author)

SPX Since 1990

Here is the XLK (technology) ETF since the year 2000, shown on a linear price scale (top plot) and a LOG scale (bottom plot):

(click on chart to enlarge image)(charts courtesy of StockCharts.com; chart creation and annotation by the author)

XLK since 2000

From a technical analysis perspective, many indicators show highly unique readings. Among these are the Bollinger Bands seen in the Nasdaq 100 chart, demonstrating the outsized velocity of recent price increases. As seen in the monthly chart below, the price has strongly rebounded since mid-2022 and is once again at the upper Bollinger Band:

(click on chart to enlarge image)(charts courtesy of StockCharts.com; chart creation and annotation by the author)

NDX Monthly

Another indication of a highly elevated level of froth is the extreme excessive valuations and accompanying very rapid price advance of scores of individual stocks both in technology as well as other sectors.

As I have mentioned in previous commentaries, the “bursting” of this stock market bubble will have many adverse impacts. My analyses continue to indicate this popping of the bubble will occur during a crash.

As I have previously written, most recently in “The U.S. Economic Situation” updates:

My analyses continues to indicate that the growing level of financial danger will lead to the next stock market crash that will also involve (as seen in 2008) various other markets as well.  Key attributes of this next crash is its outsized magnitude (when viewed from an ultra-long term historical perspective) and the resulting economic impact.  This next financial crash is of tremendous concern, as my analyses indicate it will lead to a Super Depression – i.e. an economy characterized by deeply embedded, highly complex, and difficult-to-solve problems.

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 6715.79 as this post is written

Monday, December 16, 2024

The Stock Market Bubble – December 2024 Update

This post is a brief update to various past commentaries concerning the stock market bubble, most notably the February 2020 page titled “The Immense Stock Market Bubble And Characteristics.”

The stock market bubble continues to grow in size, which is highly notable given the enormous size of the bubble during February 2020. My analyses indicate that this stock market bubble is the largest stock market bubble ever in the United States. As well, another problematic aspect is that the stock market bubble is just one of many exceedingly large asset bubbles in existence. The existence of these astoundingly large asset bubbles poses a grave risk to the financial system and economy.

I have written extensively concerning the stock market bubble, its causes, and current and future consequences. It should be noted that a fully comprehensive discussion would be exceedingly lengthy and at times very complex. Perhaps the paramount aspects of this stock market bubble is that, for various reasons, it is far larger than most conventional measures would suggest; and that the future consequences of the “bursting” of the bubble will be highly problematical on many fronts.

As stated in the February 2020 commentary, one of the foremost signs of asset bubbles is excessive sentiment. Excessive sentiment can manifest in many ways. The current stock market environment exhibits a broad array of excessively positive sentiment. This excessively positive sentiment is often referred to as excessive speculation or “froth.” The stock market is experiencing an epochal speculative mania.

Of particular note are the characteristics of the most overvalued sector, technology. Here is a chart showing the “Price-To-Sales Ratio” for two technology segments from the Bloomberg article of December 11, 2024 titled “Inflation Took a Licking…“:

In the February 2020 commentary I displayed a variety of long-term charts that depicted notable fundamental and technical measures. Below is an update to three of those charts, the S&P500, the XLK ETF, and the Nasdaq 100.

Shown below is the S&P500 daily chart since 1990, with prices displayed on a linear scale on the top plot and a LOG scale on the bottom plot:

(click on charts to enlarge images)(charts courtesy of StockCharts.com; chart creation and annotation by the author)

S&P500 since 1990

Here is the XLK (technology) ETF since the year 2000, shown on a linear price scale (top plot) and a LOG scale (bottom plot):

(click on chart to enlarge image)(charts courtesy of StockCharts.com; chart creation and annotation by the author)

XLK since 2000

From a technical analysis perspective, many indicators show highly unique readings. Among these are the Bollinger Bands seen in the Nasdaq 100 chart, demonstrating the outsized velocity of recent price increases. As seen in the monthly chart below, the price has strongly rebounded since mid-2022 and is once again at the upper Bollinger Band:

(click on chart to enlarge image)(charts courtesy of StockCharts.com; chart creation and annotation by the author)

NDX Monthly

Another indication of a highly elevated level of froth is the extreme excessive valuations and accompanying very rapid price advance of scores of individual stocks both in technology as well as other sectors.

As I have mentioned in previous commentaries, the “bursting” of this stock market bubble will have many adverse impacts. My analyses continue to indicate this popping of the bubble will occur during a crash.

As I have previously written, most recently in “The U.S. Economic Situation” updates:

My analyses continues to indicate that the growing level of financial danger will lead to the next stock market crash that will also involve (as seen in 2008) various other markets as well.  Key attributes of this next crash is its outsized magnitude (when viewed from an ultra-long term historical perspective) and the resulting economic impact.  This next financial crash is of tremendous concern, as my analyses indicate it will lead to a Super Depression – i.e. an economy characterized by deeply embedded, highly complex, and difficult-to-solve problems.

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 6051.09 as this post is written
Tuesday, February 20, 2024

The Stock Market Bubble – February 2024 Update

This post is a brief update to various past commentaries concerning the stock market bubble, most notably the February 2020 page titled “The Immense Stock Market Bubble And Characteristics.”

The stock market bubble continues to grow in size, which is highly notable given the enormous size of the bubble during February 2020. My analyses indicate that this stock market bubble is the largest stock market bubble ever in the United States. As well, another problematic aspect is that the stock market bubble is just one of many exceedingly large asset bubbles in existence. The existence of these astoundingly large asset bubbles poses a grave risk to the financial system and economy.

I have written extensively concerning the stock market bubble, its causes, and current and future consequences. It should be noted that a fully comprehensive discussion would be exceedingly lengthy and at times very complex. Perhaps the paramount aspects of this stock market bubble is that, for various reasons, it is far larger than most conventional measures would suggest; and that the future consequences of the “bursting” of the bubble will be highly problematical on many fronts.

As stated in the February 2020 commentary, one of the foremost signs of asset bubbles is excessive sentiment. Excessive sentiment can manifest in many ways. The current stock market environment exhibits a broad array of excessively positive sentiment. This excessively positive sentiment is often referred to as excessive speculation or “froth.” The current stock market is experiencing an epochal speculative mania.

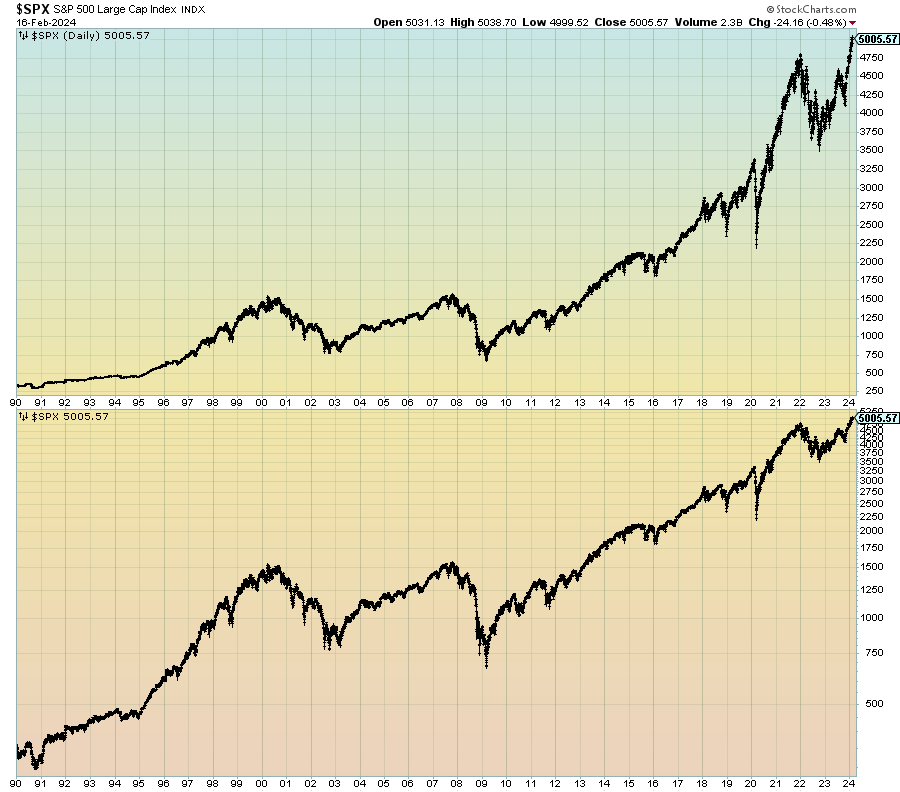
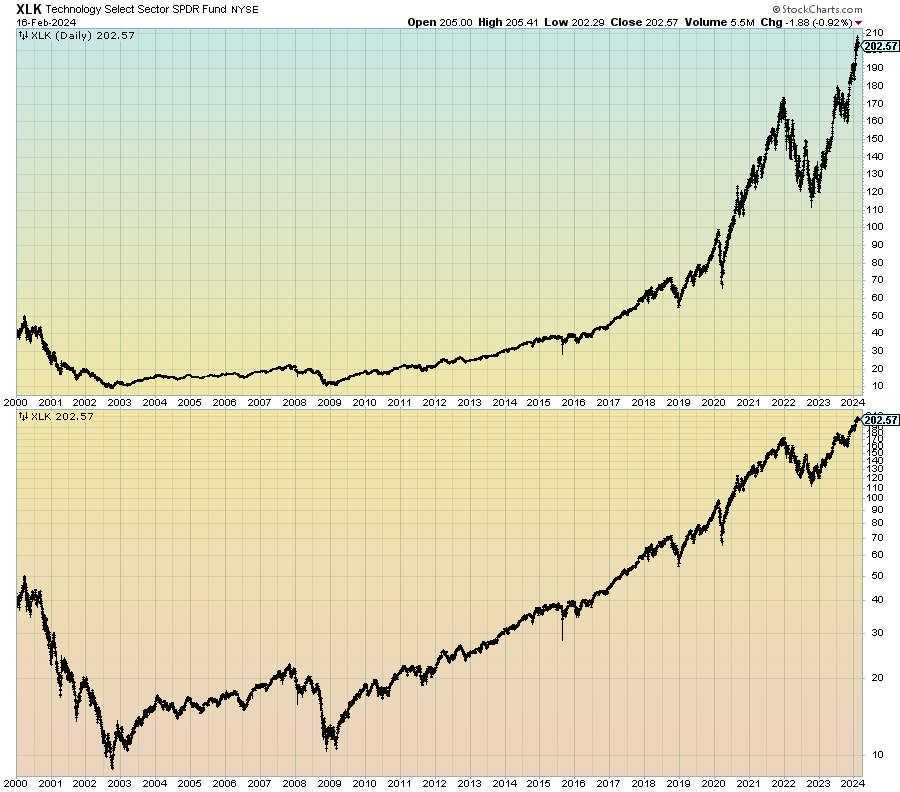
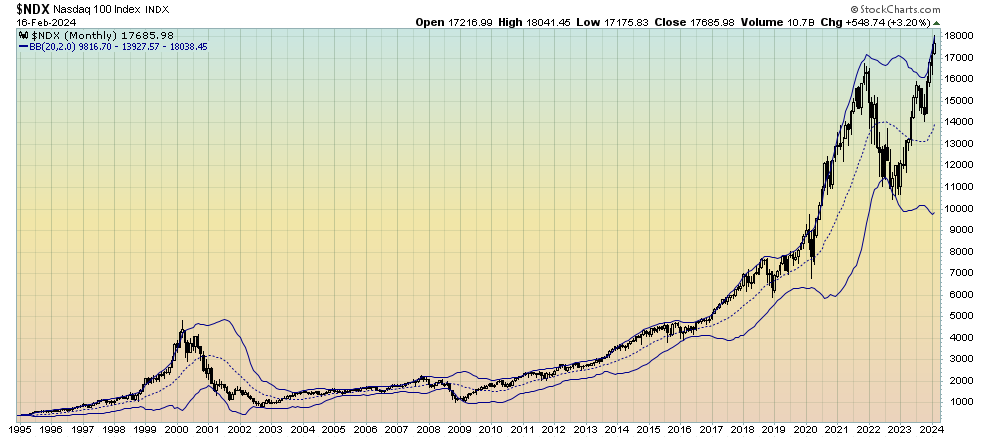
In the February 2020 commentary I displayed a variety of long-term charts that depicted notable fundamental and technical measures. Below is an update to three of those charts, the S&P500, the XLK ETF, and the Nasdaq 100. The XLK and Nasdaq 100 illustrate the outsized price appreciation of perhaps the most overvalued market segment, technology.

Shown below is the S&P500 daily chart since 1990, with prices displayed on a linear scale on the top plot and a LOG scale on the bottom plot:

(click on charts to enlarge images)(charts courtesy of StockCharts.com; chart creation and annotation by the author)

S&P500 since 1990

Here is the XLK (technology) ETF since the year 2000, shown on a linear price scale (top plot) and a LOG scale (bottom plot):

(click on chart to enlarge image)(charts courtesy of StockCharts.com; chart creation and annotation by the author)

XLK since 2000

From a technical analysis perspective, many indicators show highly unique readings. Among these are the Bollinger Bands seen in the Nasdaq 100 chart, demonstrating the outsized velocity of recent price increases. As seen in the monthly chart below, the price has strongly rebounded since mid-2022 and is once again at the upper Bollinger Band:

(click on chart to enlarge image)(charts courtesy of StockCharts.com; chart creation and annotation by the author)

Nasdaq 100

Another indication of a highly elevated level of froth is the extreme excessive valuations and accompanying very rapid price advance of scores of individual stocks both in technology as well as other sectors.

As I have mentioned in previous commentaries, the “bursting” of this stock market bubble will have many adverse impacts. My analyses continue to indicate this popping of the bubble will occur during a crash.

As I have previously written, most recently in “The U.S. Economic Situation” updates:

My analyses continues to indicate that the growing level of financial danger will lead to the next stock market crash that will also involve (as seen in 2008) various other markets as well.  Key attributes of this next crash is its outsized magnitude (when viewed from an ultra-long term historical perspective) and the resulting economic impact.  This next financial crash is of tremendous concern, as my analyses indicate it will lead to a Super Depression – i.e. an economy characterized by deeply embedded, highly complex, and difficult-to-solve problems.

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 5005.57 as this post is written

Monday, June 26, 2023

The Real Fed Funds Rate And Its Significance

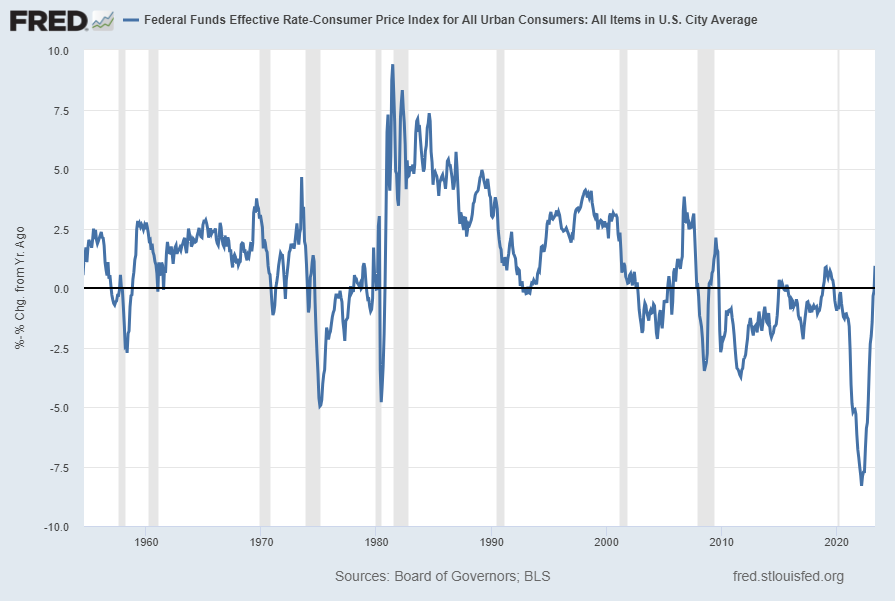
On January 9, 2017 I wrote a post titled “Low Interest Rates And The Formation Of Asset Bubbles.“  As discussed in that post – and for other reasons – the level of the Fed Funds rate – and whether its level is appropriate – has vast importance and far-reaching consequences with regard to many aspects of the economy and financial system.

Along these lines, below is an updated long-term chart indicating the Real Fed Funds Rate [FRED FEDFUNDS – CPIAUCSL] , with a last value of .93116% through May 2023. [FEDFUNDS = 5.06% as of the June 1, 2023 update; CPIAUCSL = 4.1% as of the June 13, 2023 update]

Of particular note is the post-2000 persistently, and often extensively, negative Real Fed Funds rate:

FEDFUNDS-CPIAUCSL .93116

source: Board of Governors of the Federal Reserve System (US), Effective Federal Funds Rate [FEDFUNDS], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed June 26, 2023: https://fred.stlouisfed.org/series/FEDFUNDS

source: U.S. Bureau of Labor Statistics, Consumer Price Index: All Items in U.S. City Average, All Urban Consumers [CPIAUCSL], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed June 26, 2023: https://fred.stlouisfed.org/series/CPIAUCSL

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 4337.55 as this post is written

Friday, September 16, 2022

The Negative Real Fed Funds Rate And Its Significance

On January 9, 2017 I wrote a post titled “Low Interest Rates And The Formation Of Asset Bubbles.“  As discussed in that post – and for other reasons – the level of the Fed Funds rate – and whether its level is appropriate – has vast importance and far-reaching consequences with regard to many aspects of the economy and financial system.

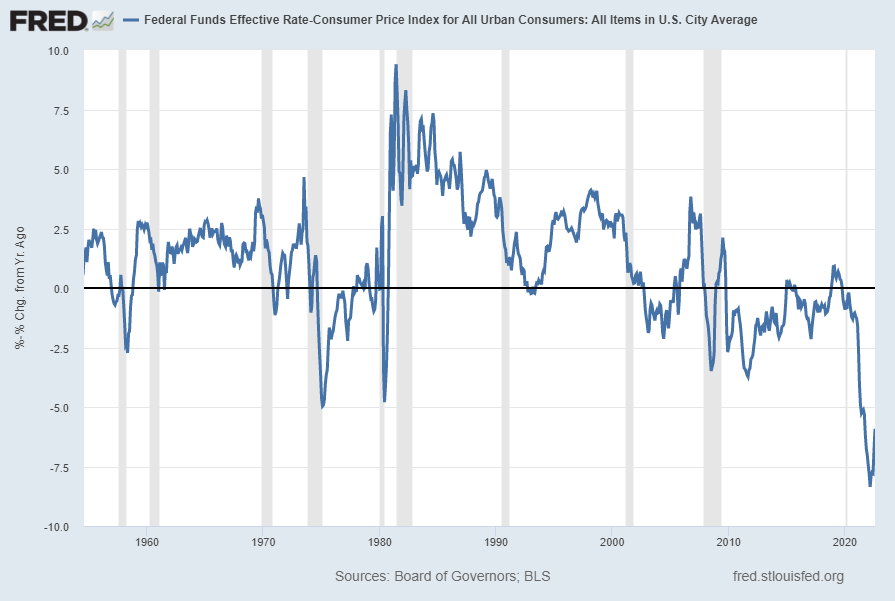
Along these lines, below is an updated long-term chart indicating the Real Fed Funds Rate [FRED FEDFUNDS – CPIAUCSL] , with a last value of -5.91923% through August 2022. [FEDFUNDS = 2.33% as of the September 1, 2022 update; CPIAUCSL = 8.2% as of the September 13, 2022 update]

Of particular note is the post-2000 persistently negative Real Fed Funds rate:

Real Fed Funds Rate -5.91923 Percent

source: Board of Governors of the Federal Reserve System (US), Effective Federal Funds Rate [FEDFUNDS], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed September 16, 2022: https://fred.stlouisfed.org/series/FEDFUNDS

source: U.S. Bureau of Labor Statistics, Consumer Price Index: All Items in U.S. City Average, All Urban Consumers [CPIAUCSL], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed September 16, 2022: https://fred.stlouisfed.org/series/CPIAUCSL

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 3850.50 as this post is written

Monday, June 13, 2022

The Notable Level Of The Real Fed Funds Rate

On January 9, 2017 I wrote a post titled “Low Interest Rates And The Formation Of Asset Bubbles.“  As discussed in that post – and for other reasons – the level of the Fed Funds rate – and whether its level is appropriate – has vast importance and far-reaching consequences with regard to many aspects of the economy and financial system.

Along these lines, below is an updated long-term chart indicating the Real Fed Funds Rate [FRED FEDFUNDS – CPIAUCSL] , with a last value of -7.74641% through May 2022. [FEDFUNDS = .77% as of the June 1, 2022 update; CPIAUCSL = 8.51641% as of the June 10, 2022 update]

Of particular note is the post-2000 persistently negative Real Fed Funds rate:

Real Fed Funds Rate

source: Board of Governors of the Federal Reserve System (US), Effective Federal Funds Rate [FEDFUNDS], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed June 13, 2022: https://fred.stlouisfed.org/series/FEDFUNDS

source: U.S. Bureau of Labor Statistics, Consumer Price Index: All Items in U.S. City Average, All Urban Consumers [CPIAUCSL], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed June 13, 2022: https://fred.stlouisfed.org/series/CPIAUCSL

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 3800.28 as this post is written

Wednesday, April 13, 2022

The Historic Level Of The Real Fed Funds Rate

On January 9, 2017 I wrote a post titled “Low Interest Rates And The Formation Of Asset Bubbles.“  As discussed in that post – and for other reasons – the level of the Fed Funds rate – and whether its level is appropriate – has vast importance and far-reaching consequences with regard to many aspects of the economy and financial system.

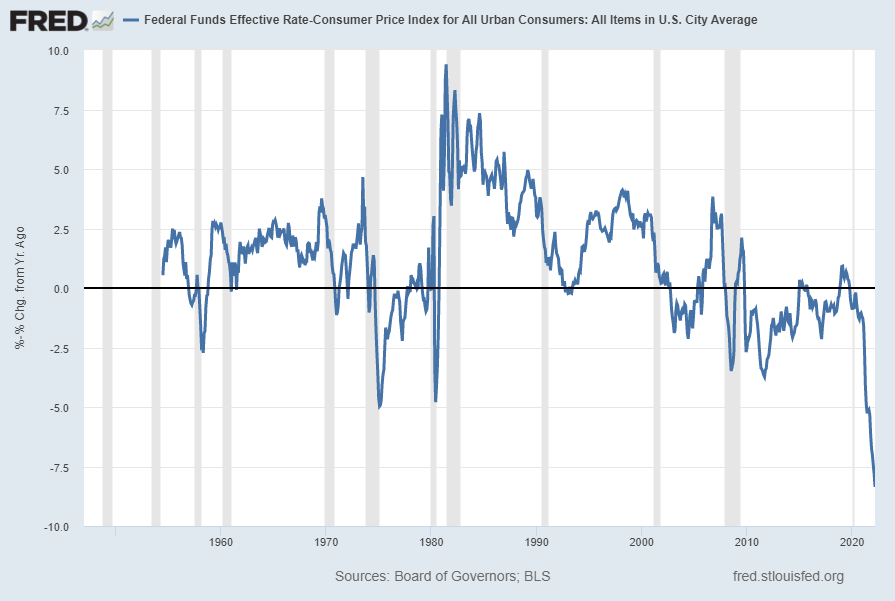
Along these lines, below is an updated long-term chart indicating the Real Fed Funds Rate [FRED FEDFUNDS – CPIAUCSL] , with a last value of -8.35759% through March 2022. [FEDFUNDS = .20% as of the April 1, 2022 update; CPIAUCSL = 8.55759% as of the April 12, 2022 update]

Of particular note is the post-2000 persistently negative Real Fed Funds rate:

Real Fed Funds Rate

source: Board of Governors of the Federal Reserve System (US), Effective Federal Funds Rate [FEDFUNDS], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed April 13, 2022: https://fred.stlouisfed.org/series/FEDFUNDS

source: U.S. Bureau of Labor Statistics, Consumer Price Index: All Items in U.S. City Average, All Urban Consumers [CPIAUCSL], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed April 13, 2022: https://fred.stlouisfed.org/series/CPIAUCSL

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 4419.17 as this post is written

Wednesday, November 10, 2021

Real Fed Funds Rate Level And Its Importance

On January 9, 2017 I wrote a post titled “Low Interest Rates And The Formation Of Asset Bubbles.“  As discussed in that post – and for other reasons – the level of the Fed Funds rate – and whether its level is appropriate – has vast importance and far-reaching consequences with regard to many aspects of the economy and financial system.

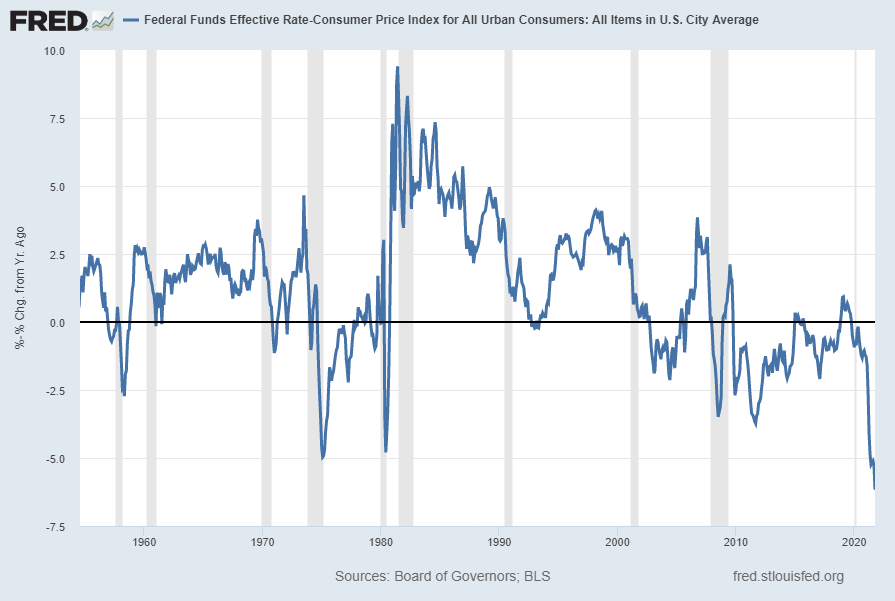
Along these lines, below is an updated long-term chart indicating the Real Fed Funds Rate [FRED FEDFUNDS – CPIAUCSL] , with a last value of -6.16352 through October 2021. Of particular note is the post-2000 persistently negative Real Fed Funds rate:

Real Fed Funds Rate chart

source: Board of Governors of the Federal Reserve System (US), Effective Federal Funds Rate [FEDFUNDS], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed November 10, 2021: https://fred.stlouisfed.org/series/FEDFUNDS

source: U.S. Bureau of Labor Statistics, Consumer Price Index: All Items in U.S. City Average, All Urban Consumers [CPIAUCSL], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed November 10, 2021: https://fred.stlouisfed.org/series/CPIAUCSL

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 4676.86 as this post is written

Friday, August 20, 2021

The Real Fed Funds Rate Level And Its Importance

On January 9, 2017 I wrote a post titled “Low Interest Rates And The Formation Of Asset Bubbles.“  As discussed in that post – and for other reasons – the level of the Fed Funds rate – and whether its level is appropriate – has vast importance and far-reaching consequences with regard to many aspects of the economy and financial system.

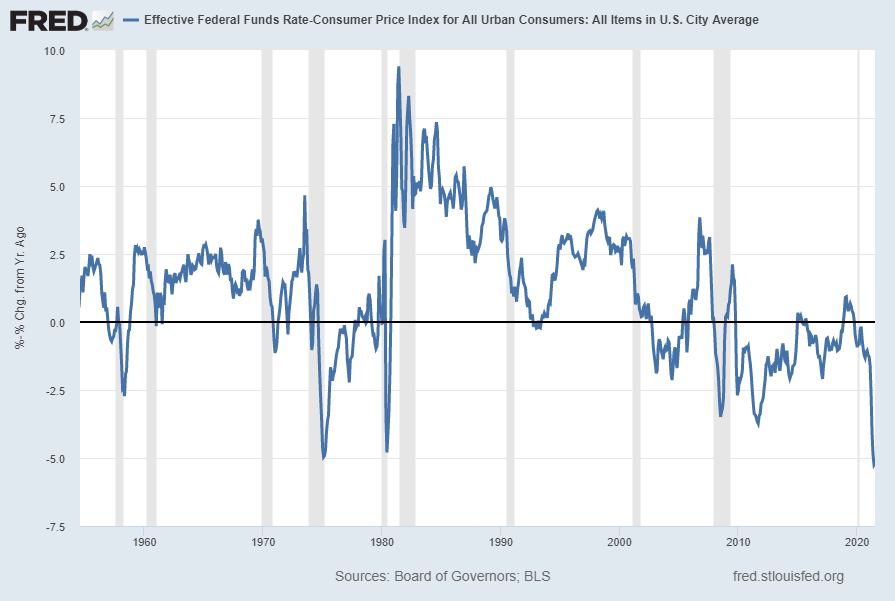
Along these lines, below is an updated long-term chart indicating the Real Fed Funds Rate [FRED FEDFUNDS – CPIAUCSL] , with a last value of -5.18259 through July 2021. Of particular note is the post-2000 persistently negative Real Fed Funds rate:

Real Fed Funds Rate -5.18259 through July 2021

source: Board of Governors of the Federal Reserve System (US), Effective Federal Funds Rate [FEDFUNDS], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed August 20, 2021: https://fred.stlouisfed.org/series/FEDFUNDS

source: U.S. Bureau of Labor Statistics, Consumer Price Index: All Items in U.S. City Average, All Urban Consumers [CPIAUCSL], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed August 20, 2021: https://fred.stlouisfed.org/series/CPIAUCSL

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 4405.80 as this post is written

Wednesday, January 20, 2021

The Stock Market Bubble – January 2021 Update

This post is a brief update to various past commentaries concerning the stock market bubble, most notably the February 2020 page titled “The Immense Stock Market Bubble And Characteristics.”

Since February 2020, the stock market bubble has grown in size, which is highly notable given the enormous size of the bubble at that time. My analyses indicate that this stock market bubble is the largest stock market bubble ever in the United States. As well, another problematic aspect is that the stock market bubble is just one of many exceedingly large asset bubbles in existence. The existence of these astoundingly large asset bubbles poses a grave risk to the financial system and economy.

I have written extensively concerning the stock market bubble, its causes, and current and future consequences. It should be noted that a fully comprehensive discussion would be exceedingly lengthy and at times very complex. Perhaps the paramount aspects of this stock market bubble is that it is far larger than most conventional measures would suggest; and that the future consequences of the “bursting” of the bubble will be highly problematical on many fronts.

As stated in the February 2020 commentary, one of the foremost signs of asset bubbles is excessive sentiment. Excessive sentiment can manifest in many ways. The current stock market environment exhibits a broad array of excessively positive sentiment. This excessively positive sentiment is often referred to as excessive speculation or “froth.” The current stock market can be categorized as an epochal speculative mania.

In the February 2020 commentary I displayed a variety of long-term charts that depicted notable fundamental and technical measures. Below is an update to one of those charts, the XLK ETF, that shows the outsized price appreciation of perhaps the most overvalued market segment, technology.

Here is the XLK (technology) ETF since the year 2000, shown on a linear price scale (top plot) and a LOG scale (bottom plot):

(click on chart to enlarge image)(charts courtesy of StockCharts.com; chart creation and annotation by the author)

Another indication of a highly elevated level of froth is the extreme excessive valuations and accompanying very rapid price advance of scores of individual stocks both in technology as well as other sectors.

As I have mentioned in previous commentaries, the “bursting” of this stock market bubble will have many adverse impacts. My analyses continue to indicate this popping of the bubble will occur during a crash.

As I have previously written, most recently in “The U.S. Economic Situation” updates:

My analyses continues to indicate that the growing level of financial danger will lead to the next stock market crash that will also involve (as seen in 2008) various other markets as well.  Key attributes of this next crash is its outsized magnitude (when viewed from an ultra-long term historical perspective) and the resulting economic impact.  This next financial crash is of tremendous concern, as my analyses indicate it will lead to a Super Depression – i.e. an economy characterized by deeply embedded, highly complex, and difficult-to-solve problems.

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 3798.91 as this post is written