Thursday, February 13, 2020

Charts Indicating Economic Weakness – February 2020

U.S. Economic Indicators

Throughout this site there are many discussions of economic indicators.  At this time, the readings of various indicators are especially notable.  This post is the latest in a series of posts indicating U.S. economic weakness or a notably low growth rate.
While many U.S. economic indicators – including GDP – are indicating economic growth, others depict (or imply) various degrees of weak growth or economic contraction.  As seen in the January 2020 Wall Street Journal Economic Forecast Survey the consensus (average estimate) among various economists is for 2.3% GDP growth in 2019 and 1.9% GDP growth in 2020.  However, there are other broad-based economic indicators that seem to imply a weaker growth rate.
As well, it should be remembered that GDP figures can be (substantially) revised.

Charts Indicating U.S. Economic Weakness

Below are a small sampling of charts that depict weak growth or contraction, and a brief comment for each:

Total Federal Receipts

“Total Federal Receipts” growth continues to be intermittent in nature since 2015.  As well, the level of growth does not seem congruent to the (recent) levels of economic growth as seen in aggregate measures such as Real GDP.
“Total Federal Receipts” through January had a last monthly value of $372,288 Million.  Shown below is the measure displayed on a “Percent Change From Year Ago” basis with value 9.5%, last updated February 12, 2020:
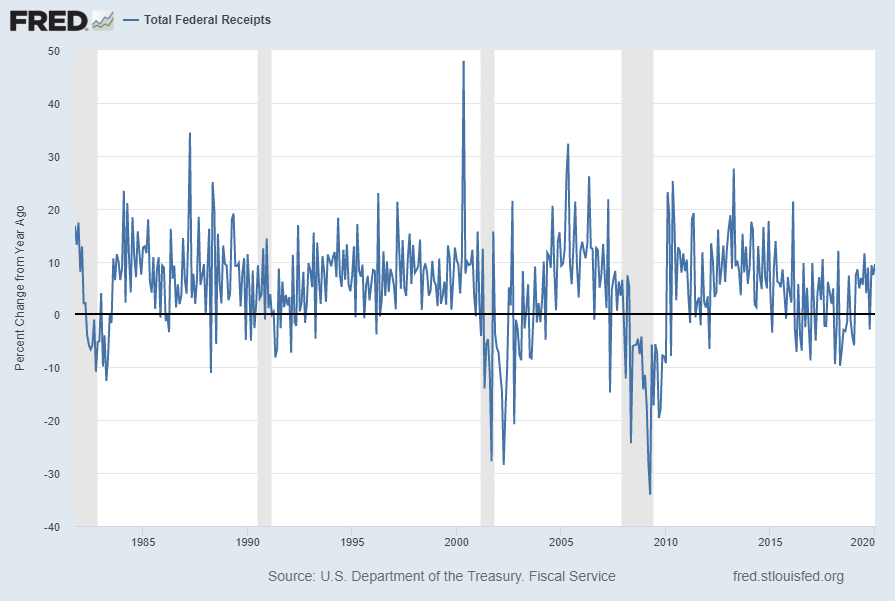
Total Federal Receipts Percent Change From Year Ago
source:  U.S. Department of the Treasury. Fiscal Service, Total Federal Receipts [MTSR133FMS], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed February 12, 2020: 
https://fred.stlouisfed.org/series/MTSR133FMS
__

The Chicago Fed National Activity Index (CFNAI)

A broad-based economic indicator that has been implying weaker growth or mild contraction is the Chicago Fed National Activity Index (CFNAI).
The January 2020 Chicago Fed National Activity Index (CFNAI) updated as of January 22, 2020:
The CFNAI, with current reading of -.35:
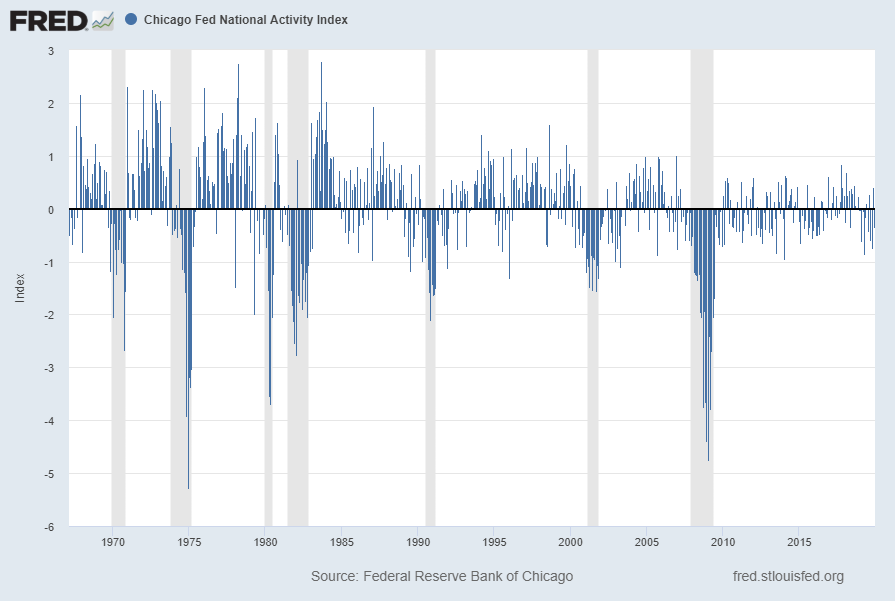
CFNAI
source:  Federal Reserve Bank of Chicago, Chicago Fed National Activity Index [CFNAI], retrieved from FRED, Federal Reserve Bank of St. Louis, January 22, 2020;
https://fred.stlouisfed.org/series/CFNAI
The CFNAI-MA3, with current reading of -.23:
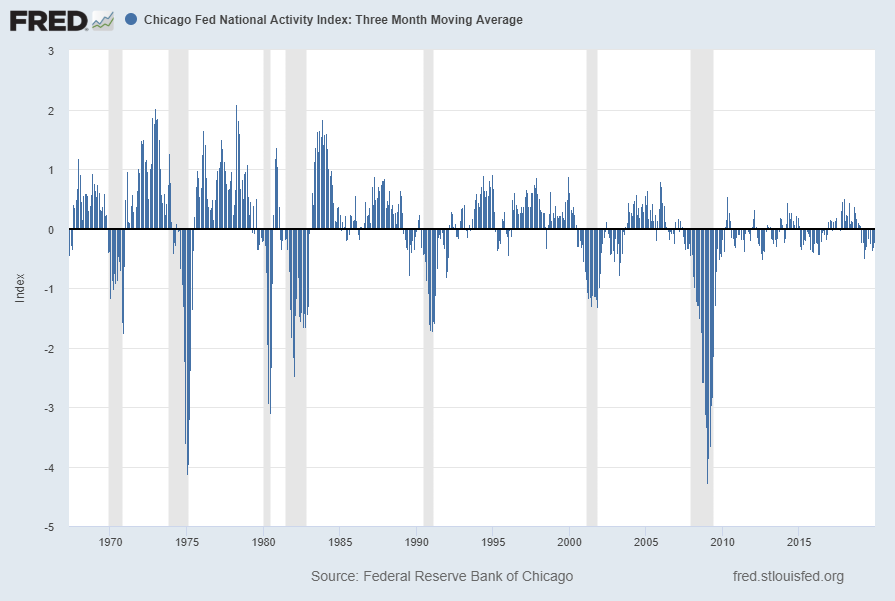
CFNAIMA3
source:  Federal Reserve Bank of Chicago, Chicago Fed National Activity Index: Three Month Moving Average [CFNAIMA3], retrieved from FRED, Federal Reserve Bank of St. Louis, January 22, 2020;
https://fred.stlouisfed.org/series/CFNAIMA3
__

The Yield Curve

Many people believe that the Yield Curve is a leading economic indicator for the United States economy.
On March 1, 2010, I wrote a post on the issue, titled “The Yield Curve As A Leading Economic Indicator.”
While I continue to have the stated reservations regarding the “Yield Curve” as an indicator, I do believe that it should be monitored.
Various portions of the U.S. Yield Curve have been showing intermittent or prolonged inversions. Below is the spread between 10-Year Treasury Constant Maturity and the 3-Month Treasury Constant Maturity from 1982 through the February 11, 2020 value, showing a value of .02 (10-Year Treasury Yield (FRED DGS10) of 1.56% , 3-Month Treasury Yield (FRED DGS3MO) of 1.58%):
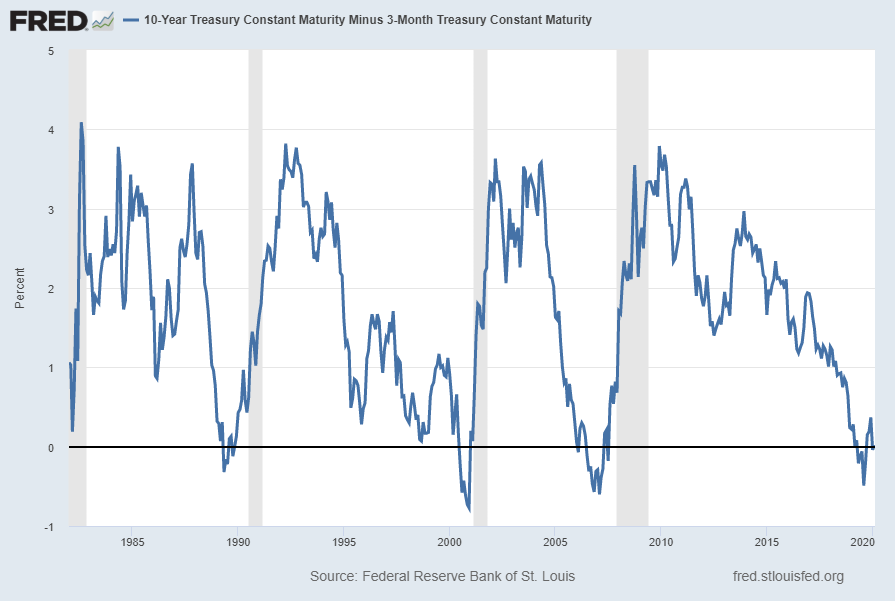
T10Y3M
source: Federal Reserve Bank of St. Louis, 10-Year Treasury Constant Maturity Minus 3-Month Treasury Constant Maturity [T10Y3M], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed February 12, 2020: https://fred.stlouisfed.org/series/T10Y3M
__

Loan Demand And Related Measures

As seen in previous updates, various aspects of lending growth and related measures have shown a contraction.  Shown below is a measure, Net Percentage of Domestic Banks Reporting Stronger Demand for Commercial and Industrial Loans from Large and Middle-Market Firms [DRSDCILM], that shows a decline.  The current value is -11.1% as of the February 3, 2020 quarterly update:
Net Percentage of Domestic Banks Reporting Stronger Demand for Commercial and Industrial Loans from Large and Middle-Market Firms [DRSDCILM]
source: Board of Governors of the Federal Reserve System (US), Net Percentage of Domestic Banks Reporting Stronger Demand for Commercial and Industrial Loans from Large and Middle-Market Firms [DRSDCILM], retrieved from FRED, Federal Reserve Bank of St. Louis; accesssed February 12, 2020: https://fred.stlouisfed.org/series/DRSDCILM
__

Job Openings

Job openings, (Job Openings: Total Nonfarm [JTSJOL]) although still at a high level, have recently declined significantly. This Job Openings measure had a value of 6423 (Thousands) through December, as of the February 11, 2020 update, as shown below:
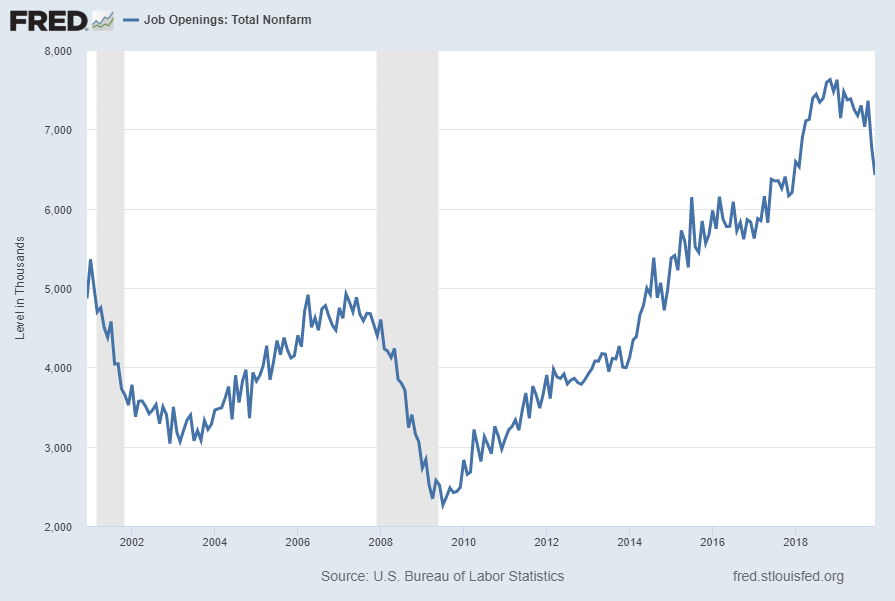
Job Openings JTSJOL
Shown below is this measure displayed on a “Percent Change From Year Ago” basis with value -14.1%:
Job Openings: Total Nonfarm [JTSJOL] Percent Change From Year Ago
source: U.S. Bureau of Labor Statistics, Job Openings: Total Nonfarm [JTSJOL], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed February 12, 2020: https://fred.stlouisfed.org/series/JTSJOL
__

Other Indicators

As mentioned previously, many other indicators discussed on this site indicate weak economic growth or economic contraction, if not outright (gravely) problematical economic conditions.
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 3379.45 as this post is written

Wednesday, February 12, 2020

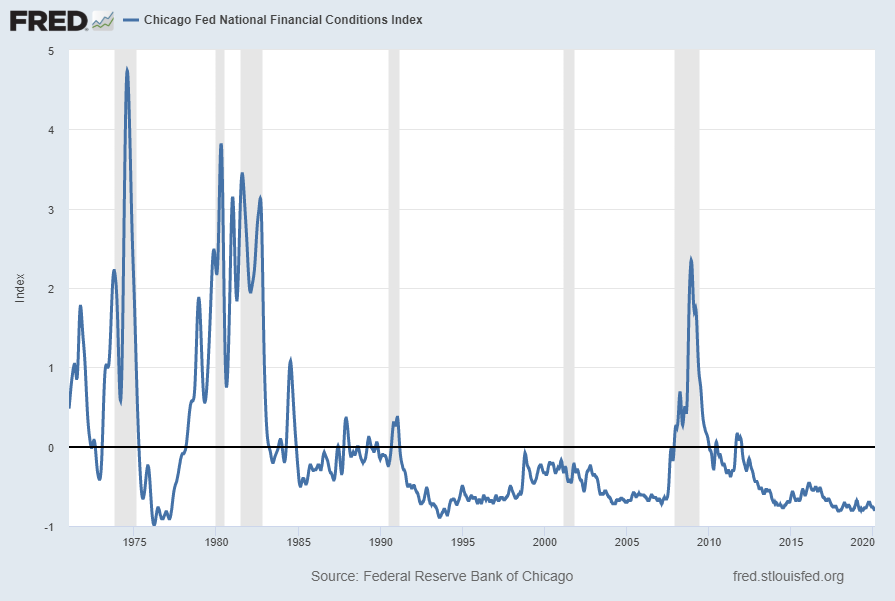
Chicago Fed National Financial Conditions Index (NFCI)

The St. Louis Fed’s Financial Stress Index (STLFSI) is one index that is supposed to measure stress in the financial system.  Its reading as of the February 6, 2020 update (reflecting data through January 31, 2020) is -1.463.
Of course, there are a variety of other measures and indices that are supposed to measure financial stress and other related issues, both from the Federal Reserve as well as from private sources.
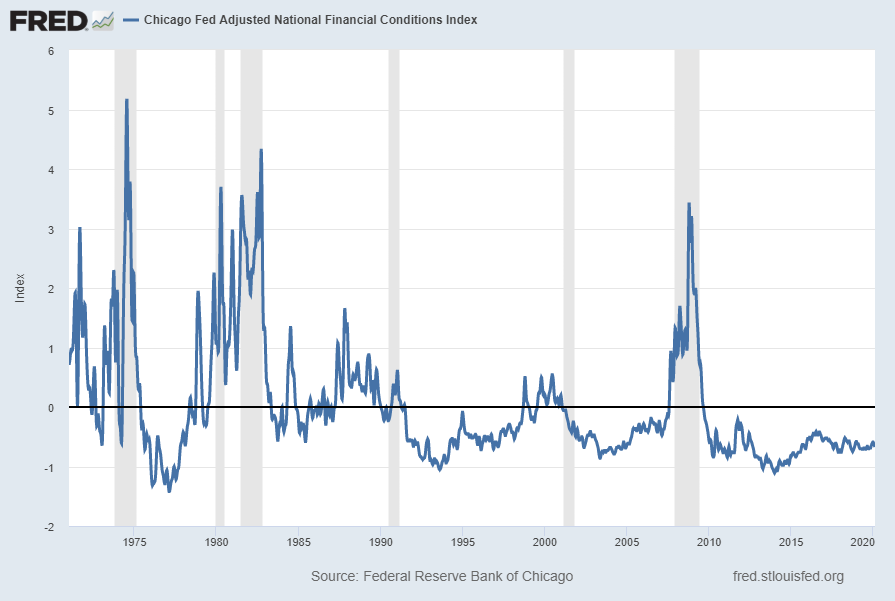
Two other indices that I regularly monitor include the Chicago Fed National Financial Conditions Index (NFCI) as well as the Chicago Fed Adjusted National Financial Conditions Index (ANFCI).
Here are summary descriptions of each, as seen in FRED:
The National Financial Conditions Index (NFCI) measures risk, liquidity and leverage in money markets and debt and equity markets as well as in the traditional and “shadow” banking systems. Positive values of the NFCI indicate financial conditions that are tighter than average, while negative values indicate financial conditions that are looser than average.
The adjusted NFCI (ANFCI). This index isolates a component of financial conditions uncorrelated with economic conditions to provide an update on how financial conditions compare with current economic conditions.
For further information, please visit the Federal Reserve Bank of Chicago’s web site:
Below are the most recently updated charts of the NFCI and ANFCI, respectively.
The NFCI chart below was last updated on February 12, 2020 incorporating data from January 8, 1971 through February 7, 2020, on a weekly basis.  The February 7 value is -.81:
NFCI
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis; accessed February 12, 2020: 
http://research.stlouisfed.org/fred2/series/NFCI
–
The ANFCI chart below was last updated on February 12, 2020 incorporating data from January 8, 1971 through February 7, 2020, on a weekly basis.  The February 7 value is -.67:
ANFCI
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis; accessed February 12, 2020: 
http://research.stlouisfed.org/fred2/series/ANFCI
_________
I post various indicators and indices because I believe they should be carefully monitored.  However, as those familiar with this site are aware, I do not necessarily agree with what they depict or imply.
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 3371.86 as this post is written
Tuesday, February 11, 2020

Recession Probability Models – February 2020

There are a variety of economic models that are supposed to predict the probabilities of recession.
While I don’t agree with the methodologies employed or probabilities of impending economic weakness as depicted by the following two models, I think the results of these models should be monitored.
Please note that each of these models is updated regularly, and the results of these – as well as other recession models – can fluctuate significantly.
The first is the “Yield Curve as a Leading Indicator” from the New York Federal Reserve.  I wrote a post concerning this measure on March 1, 2010, titled “The Yield Curve as a Leading Indicator.”
Currently (last updated February 4, 2020 using data through January 2020) this “Yield Curve” model shows a 25.2037% probability of a recession in the United States twelve months ahead.  For comparison purposes, it showed a 23.6237% probability through December 2019, and a chart going back to 1960 is seen at the “Probability Of U.S. Recession Predicted by Treasury Spread.” (pdf)
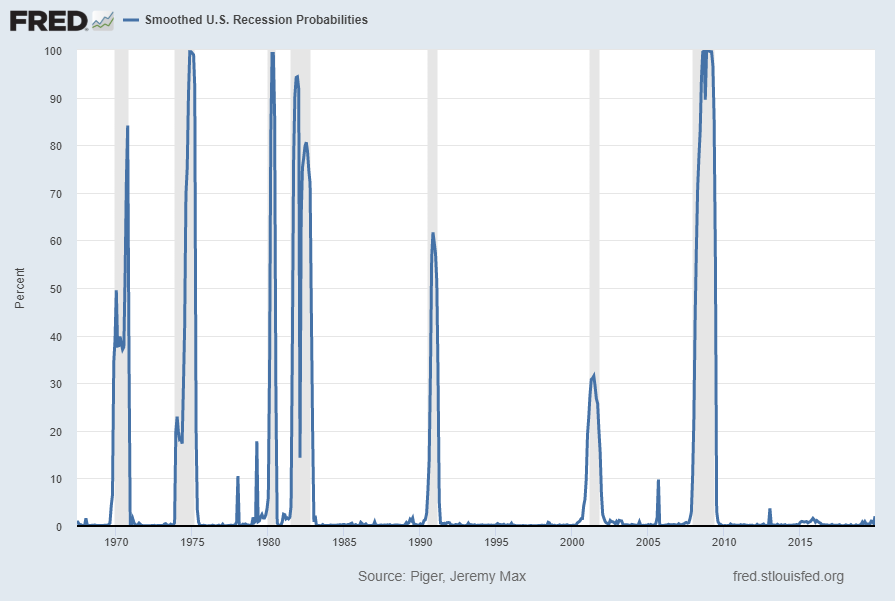
The second model is from Marcelle Chauvet and Jeremy Piger.  This model is described on the St. Louis Federal Reserve site (FRED) as follows:
Smoothed recession probabilities for the United States are obtained from a dynamic-factor markov-switching model applied to four monthly coincident variables: non-farm payroll employment, the index of industrial production, real personal income excluding transfer payments, and real manufacturing and trade sales. This model was originally developed in Chauvet, M., “An Economic Characterization of Business Cycle Dynamics with Factor Structure and Regime Switching,” International Economic Review, 1998, 39, 969-996. (http://faculty.ucr.edu/~chauvet/ier.pdf)
Additional details and explanations can be seen on the “U.S. Recession Probabilities” page.
This model, last updated on February 3, 2020 currently shows a 2.06% probability using data through December 2019.
Here is the FRED chart (last updated February 3, 2020):

Smoothed Recession Probabilities for the United States

Data Source:  Piger, Jeremy Max and Chauvet, Marcelle, Smoothed U.S. Recession Probabilities [RECPROUSM156N], retrieved from FRED, Federal Reserve Bank of St. Louis, accessed February 10, 2020:
http://research.stlouisfed.org/fred2/series/RECPROUSM156N
–
The two models featured above can be compared against measures seen in recent posts.  For instance, as seen in the January 16, 2020 post titled “The January 2020 Wall Street Journal Economic Forecast Survey“ economists surveyed averaged a 23.97% probability of a U.S. recession within the next 12 months.
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 3352.09 as this post is written
Friday, February 7, 2020

Monthly Changes In Total Nonfarm Payroll – February 7, 2020 Update

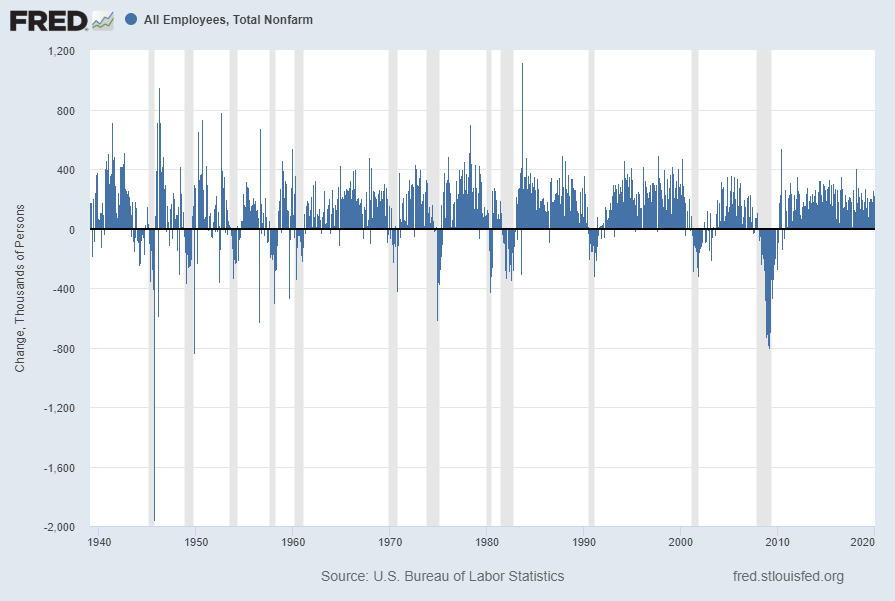
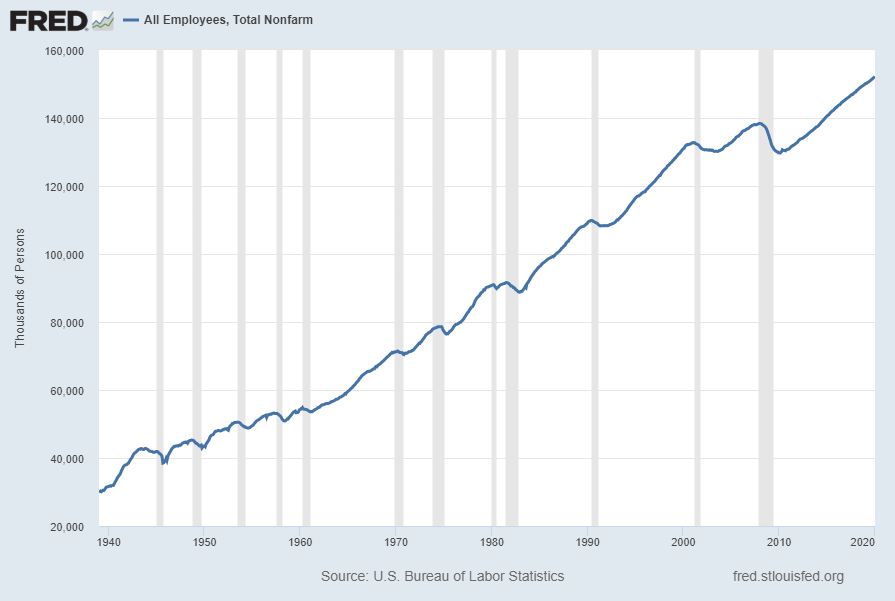
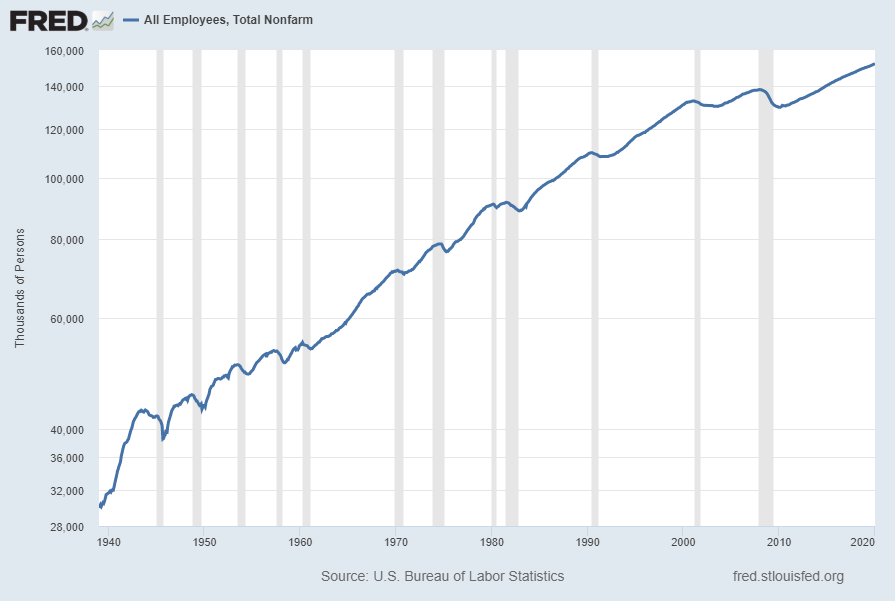
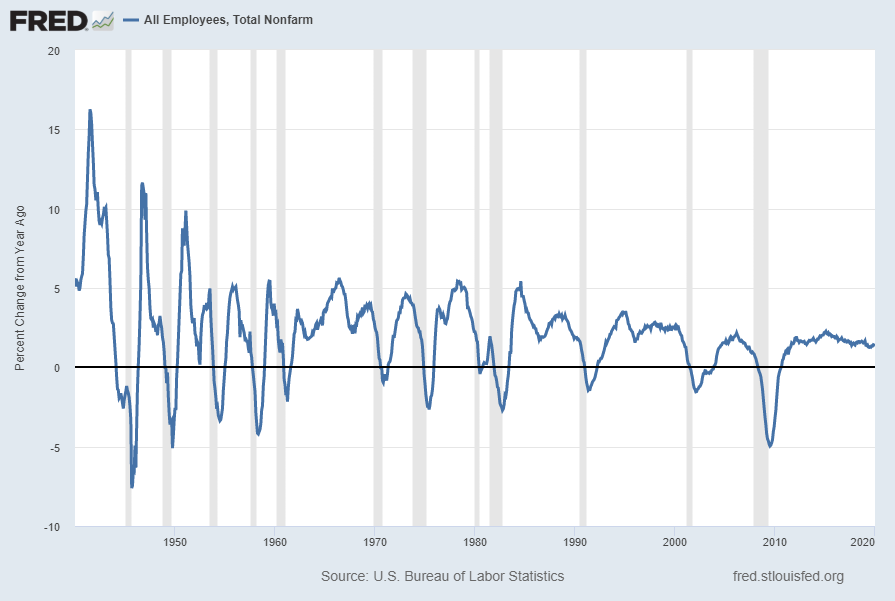
For reference purposes, below are five charts that display growth in payroll employment, as depicted by the Total Nonfarm Payroll measures (FRED data series PAYEMS).
PAYEMS, which is seasonally adjusted, is defined in Financial Reserve Economic Data [FRED] as:
All Employees: Total Nonfarm, commonly known as Total Nonfarm Payroll, is a measure of the number of U.S. workers in the economy that excludes proprietors, private household employees, unpaid volunteers, farm employees, and the unincorporated self-employed. This measure accounts for approximately 80 percent of the workers who contribute to Gross Domestic Product (GDP).
This measure provides useful insights into the current economic situation because it can represent the number of jobs added or lost in an economy. Increases in employment might indicate that businesses are hiring which might also suggest that businesses are growing. Additionally, those who are newly employed have increased their personal incomes, which means (all else constant) their disposable incomes have also increased, thus fostering further economic expansion.
Generally, the U.S. labor force and levels of employment and unemployment are subject to fluctuations due to seasonal changes in weather, major holidays, and the opening and closing of schools. The Bureau of Labor Statistics (BLS) adjusts the data to offset the seasonal effects to show non-seasonal changes: for example, women’s participation in the labor force; or a general decline in the number of employees, a possible indication of a downturn in the economy. To closely examine seasonal and non-seasonal changes, the BLS releases two monthly statistical measures: the seasonally adjusted All Employees: Total Nonfarm (PAYEMS) and All Employees: Total Nonfarm (PAYNSA), which is not seasonally adjusted.
The series comes from the ‘Current Employment Statistics (Establishment Survey).’
The source code is: CES0000000001
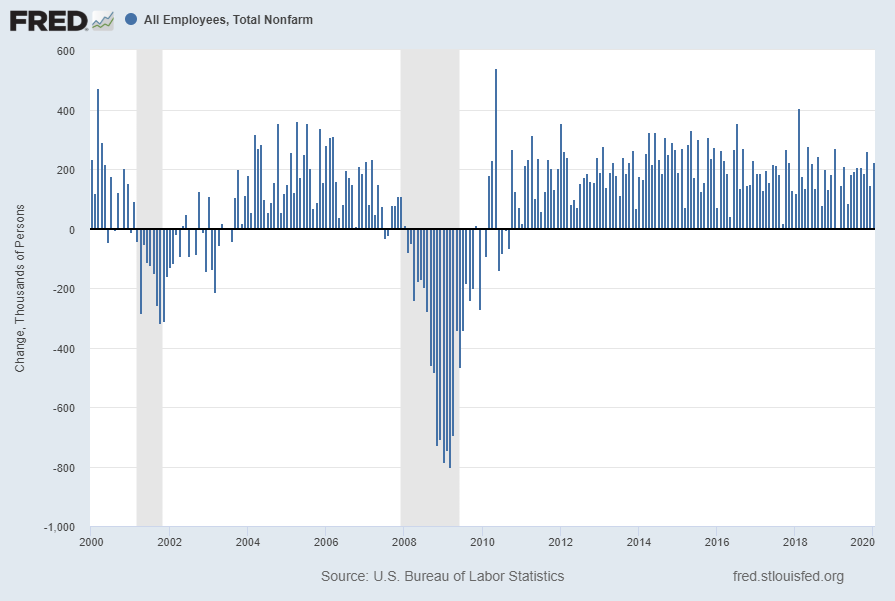
The first chart shows the monthly change in Total Nonfarm Payroll from the year 2000 through the current January 2020 report (January 2020 value of 225 (Thousands)):
(click on charts to enlarge images)
Total Nonfarm Payroll monthly change chart from the year 2000
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis: All Employees: Total Nonfarm [PAYEMS] ; U.S. Department of Labor: Bureau of Labor Statistics; accessed February 7, 2020; https://fred.stlouisfed.org/series/PAYEMS
The second chart shows a longer-term chart of the same month-over-month change in Total Nonfarm Payroll (reports of February 1939 through the present report of January 2020):
Total Nonfarm Payroll monthly change chart from 1939
The third chart shows the aggregate number of Total Nonfarm Payroll, from the reports of February 1939 – January 2020 (January 2020 value of 152.186 million):
Total Nonfarm Payroll chart from year 1939
The fourth chart shows this same aggregate number of Total Nonfarm Payroll measure as seen above but presented on a LOG scale:
PAYEMS LOG scale
Lastly, the fifth chart shows the Total Nonfarm Payroll number on a “Percent Change from Year Ago” basis from January 1940 – January 2020: (January 2020 value of 1.4%)
PAYEMS Percent Change From Year Ago
_________
I post various indicators and indices because I believe they should be carefully monitored.  However, as those familiar with this site are aware, I do not necessarily agree with what they depict or imply.
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 3332.16 as this post is written
Average Hourly Earnings Trends

I have written many blog posts concerning the worrisome trends in income and earnings.
Along these lines, one of the measures showing disconcerting trends is that of hourly earnings.
While the concept of hourly earnings can be defined and measured in a variety of ways, below are a few charts that I believe broadly illustrate problematic trends.
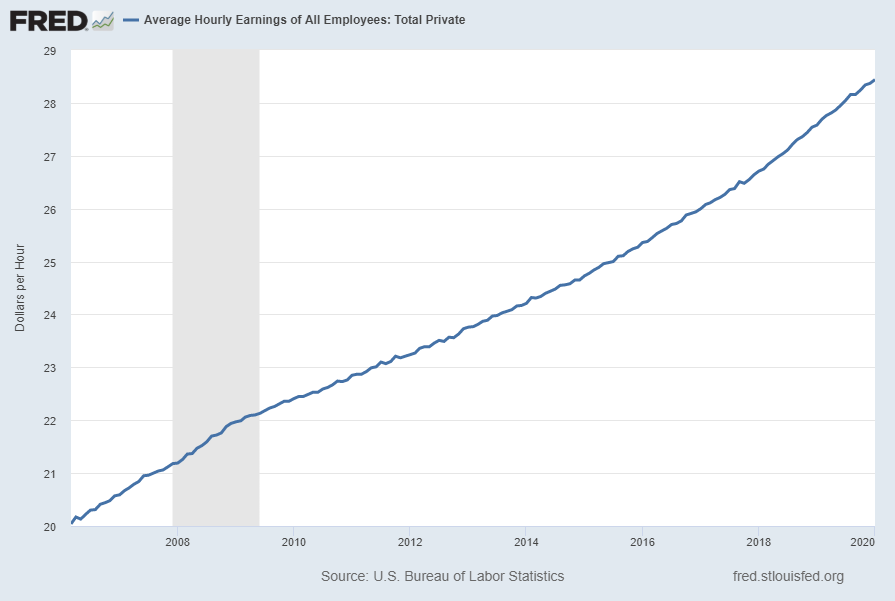
The first chart depicts Average Hourly Earnings Of All Employees: Total Private (FRED series CES0500000003)(current value = $28.44):
(click on chart to enlarge image)(chart last updated 2-7-20)
CES0500000003
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis: Average Hourly Earnings of All Employees:  Total Private [CES0500000003] ; U.S. Department of Labor: Bureau of Labor Statistics; accessed February 7, 2020:
http://research.stlouisfed.org/fred2/series/CES0500000003
–
This next chart depicts this same measure on a “Percentage Change From A Year Ago” basis.   While not totally surprising, I find the decline from 2009 and subsequent trend to be disconcerting:
(click on chart to enlarge image)(chart last updated 2-7-20)
CES0500000003 Percent Change From Year Ago
–
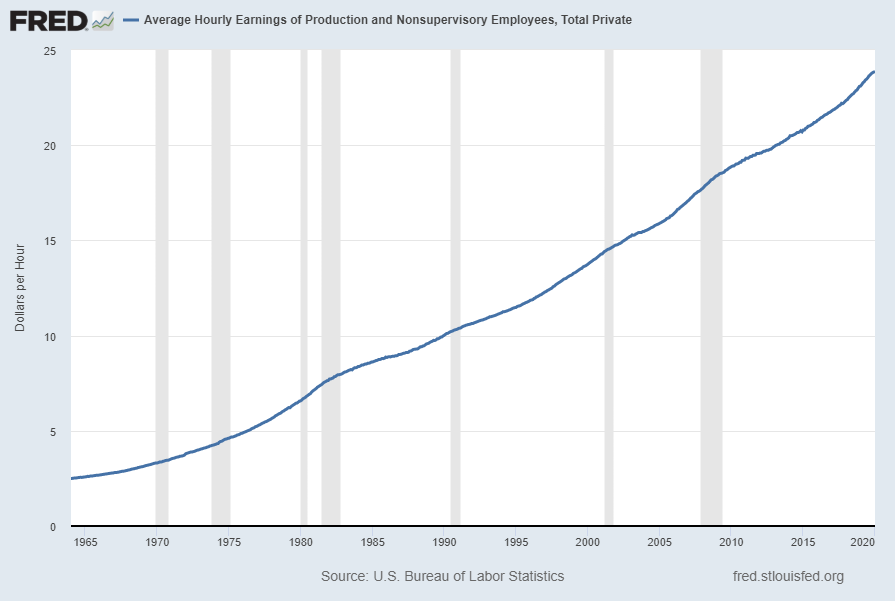
There are slightly different measures available from a longer-term perspective. Pictured below is another measure, the Average Hourly Earnings of Production and Nonsupervisory Employees – Total Private (FRED series AHETPI)(current value = $23.87):
(click on chart to enlarge image)(chart last updated 2-7-20)
AHETPI
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis: Average Hourly Earnings of Production and Nonsupervisory Employees:  Total Private [AHETPI] ; U.S. Department of Labor: Bureau of Labor Statistics;  accessed February 7, 2020:
http://research.stlouisfed.org/fred2/series/AHETPI
–
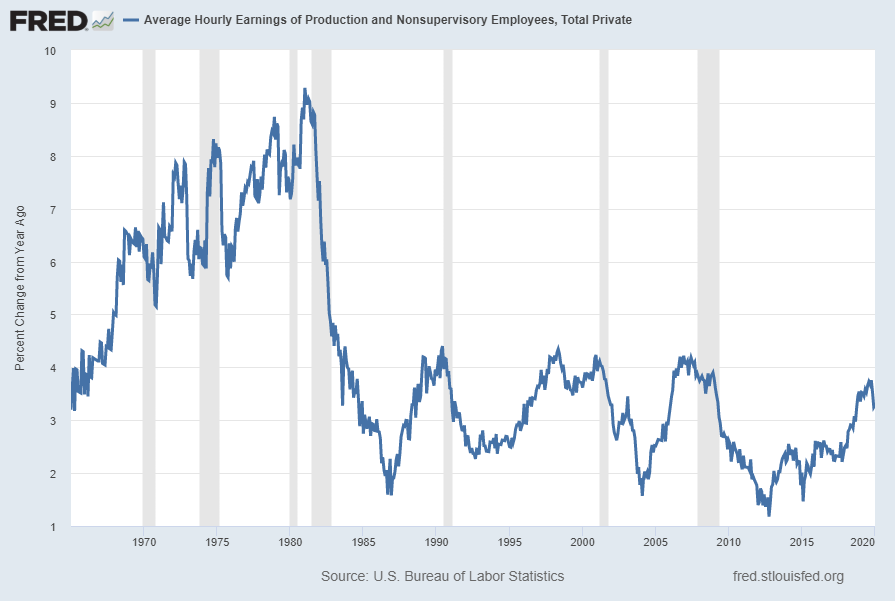
Pictured below is this AHETPI measure on a “Percentage Change From A Year Ago” basis.   While not totally surprising, I find the decline from 2009 and subsequent trend to be disconcerting:
(click on chart to enlarge image)(chart last updated 2-7-20)
AHETPI Percent Change From Year Ago
–
I will continue to actively monitor these trends, especially given the post-2009 dynamics.
_________
I post various economic indicators and indices because I believe they should be carefully monitored.  However, as those familiar with this site are aware, I do not necessarily agree with what they depict or imply.
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 3335.84 this post is written
U-3 And U-6 Unemployment Rate Long-Term Reference Charts As Of February 7, 2020

Shortly after each monthly employment report I have been posting a continual series titled “3 Critical Unemployment Charts.”
Of course, there are many other employment charts that can be displayed as well.
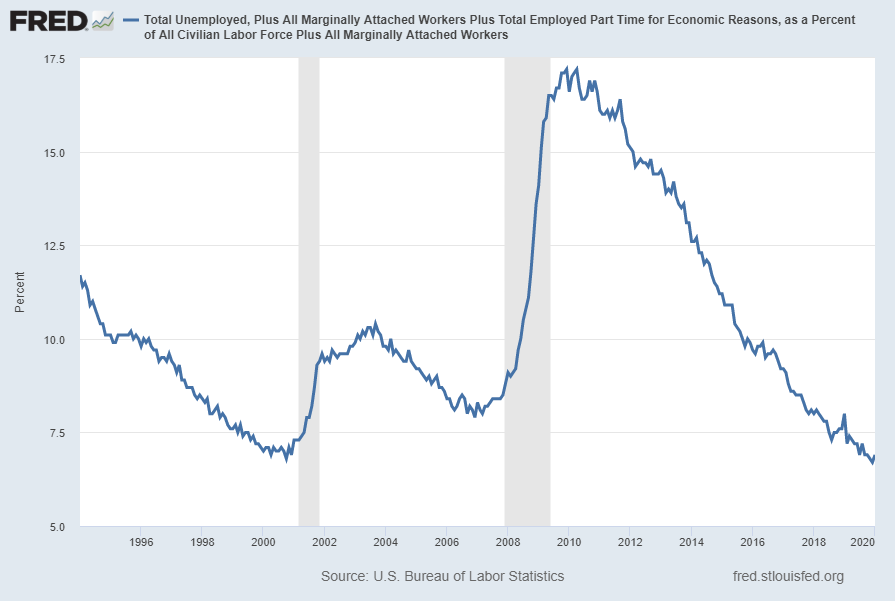
For reference purposes, below are the U-3 and U-6 Unemployment Rate charts from a long-term historical perspective.  Both charts are from the St. Louis Fed site.  The U-3 measure is what is commonly referred to as the official unemployment rate; whereas the U-6 rate is officially (per Bureau of Labor Statistics) defined as:
Total unemployed, plus all persons marginally attached to the labor force, plus total employed part time for economic reasons, as a percent of the civilian labor force plus all persons marginally attached to the labor force
Of note, many economic observers use the U-6 rate as a (closer) proxy of the actual unemployment rate rather than that depicted by the U-3 measure.
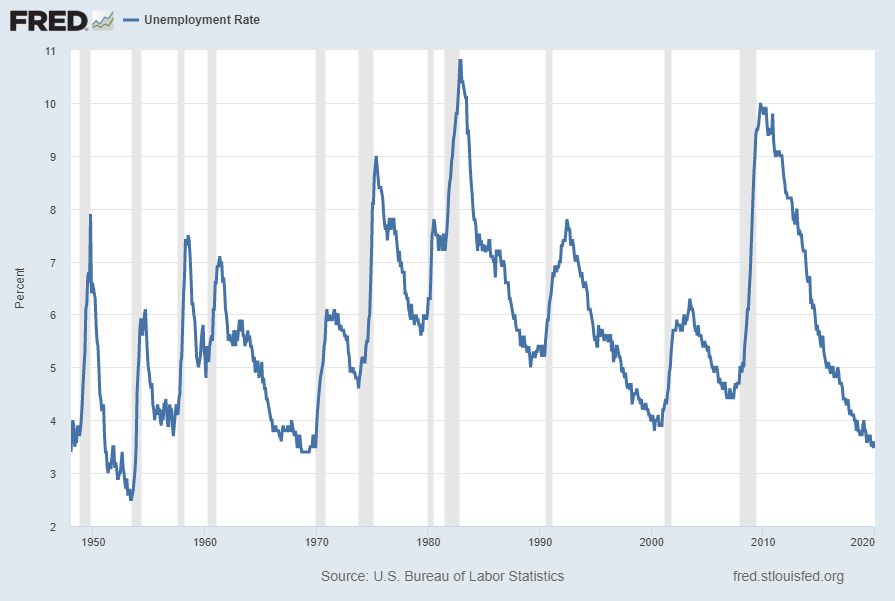
Here is the U-3 chart, currently showing a 3.6% unemployment rate:
(click on charts to enlarge images)(charts updated as of 2-7-20)
U-3 rate
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis: Civilian Unemployment Rate [UNRATE] ; U.S. Department of Labor: Bureau of Labor Statistics; accessed February 7, 2020:
http://research.stlouisfed.org/fred2/series/UNRATE
–
Here is the U-6 chart, currently showing a 6.9% unemployment rate:
U-6 rate
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis: Total unemployed, plus all marginally attached workers plus total employed part time for economic reasons  [U6RATE] ; U.S. Department of Labor: Bureau of Labor Statistics; accessed February 7, 2020: 
http://research.stlouisfed.org/fred2/series/U6RATE
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 3339.58 as this post is written
3 Critical Unemployment Charts – February 2020

As I have commented previously, as in the October 6, 2009 post (“A Note About Unemployment Statistics”), in my opinion the official methodologies used to measure the various job loss and unemployment statistics do not provide an accurate depiction; they serve to understate the severity of unemployment.
However, even if one chooses to look at the official statistics, the following charts provide an interesting (and disconcerting) long-term perspective of certain aspects of the officially-stated unemployment (and, in the third chart, employment) situation.
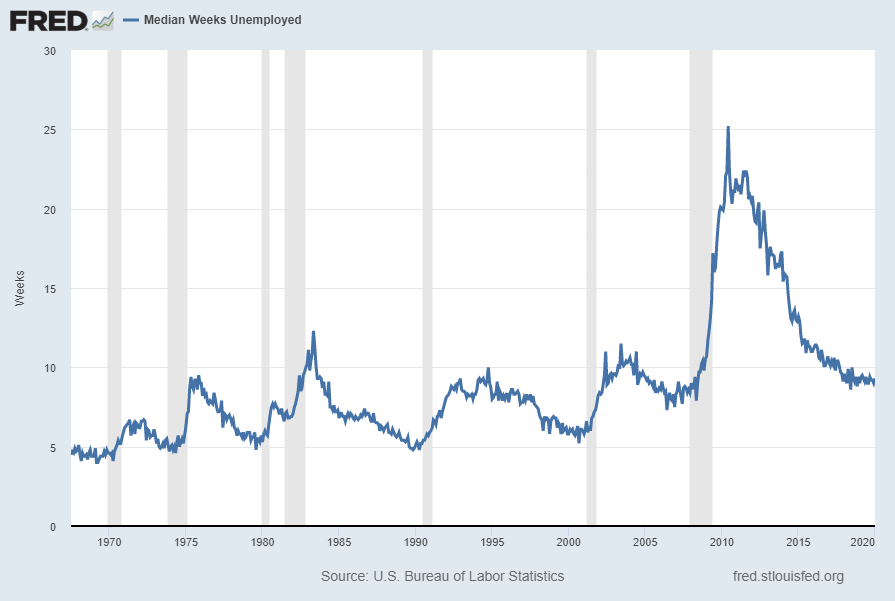
The three charts below are from the St. Louis Fed site.  Here is the Median Duration of Unemployment (current value = 9.3 weeks):
(click on charts to enlarge images)(charts updated as of 2-7-20)
Median Duration of Unemployment
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis: Median Duration of Unemployment [UEMPMED] ; U.S. Department of Labor: Bureau of Labor Statistics; accessed February 7, 2020: 
http://research.stlouisfed.org/fred2/series/UEMPMED
–
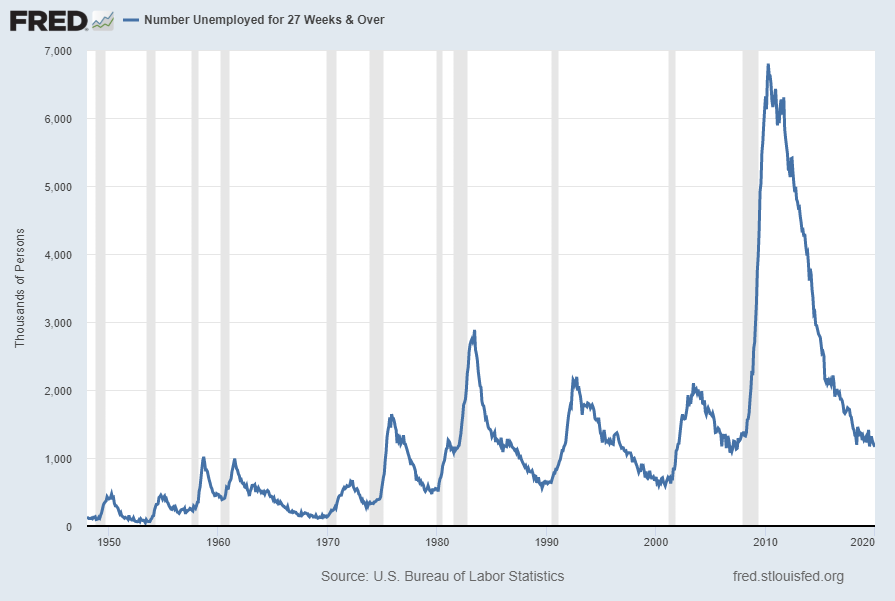
Here is the chart for Unemployed 27 Weeks and Over (current value = 1.166 million):
Unemployed 27 Weeks And Over
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis: Civilians Unemployed for 27 Weeks and Over [UEMP27OV] ; U.S. Department of Labor: Bureau of Labor Statistics; accessed February 7, 2020:
http://research.stlouisfed.org/fred2/series/UEMP27OV
–
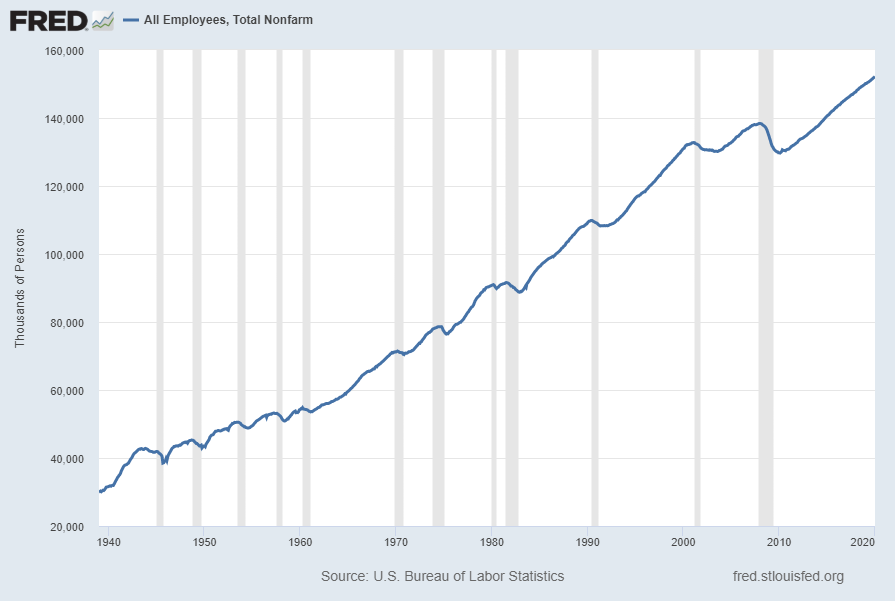
Here is the chart for Total Nonfarm Payroll (current value = 152.186 million):
Total Nonfarm Payroll
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis: All Employees: Total Nonfarm [PAYEMS] ; U.S. Department of Labor: Bureau of Labor Statistics; accessed February 7, 2020: 
https://research.stlouisfed.org/fred2/series/PAYEMS
–
Our unemployment problem is severe.  The underlying dynamics of the current – and especially future – unemployment situation remain exceedingly worrisome.  These dynamics are numerous and complex, and greatly lack recognition and understanding.
My commentary regarding unemployment is generally found in the “Unemployment” label.  This commentary includes the page titled “U.S. Unemployment Trends,” which discusses various problematical issues concerning the present and future employment situation.
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 3333.07 as this post is written

Building Financial Danger – February 7, 2020 Update

My overall analysis indicates a continuing elevated and growing level of financial danger which contains many worldwide and U.S.-specific “stresses” of a very complex nature. I have written numerous posts on this site concerning both ongoing and recent “negative developments.”  These developments, as well as other exceedingly problematical conditions, have presented a highly perilous economic environment that endangers the overall financial system.
Also of ongoing immense importance is the existence of various immensely large asset bubbles, a subject of which I have extensively written.  While all of these asset bubbles are wildly pernicious and will have profound adverse future implications, hazards presented by the bond market bubble are especially notable.
Predicting the specific timing and extent of a stock market crash is always difficult, and the immense complexity of today’s economic situation makes such a prediction even more challenging. With that being said, my analyses continue to indicate that a near-term exceedingly large (from an ultra long-term perspective) stock market crash – that would also involve (as seen in 2008) various other markets – will occur. [note: the “next crash” and its aftermath has paramount significance and implications, as discussed in the post of January 6, 2012 titled “The Next Crash And Its Significance“ and various subsequent posts in the “Economic Depression” label]
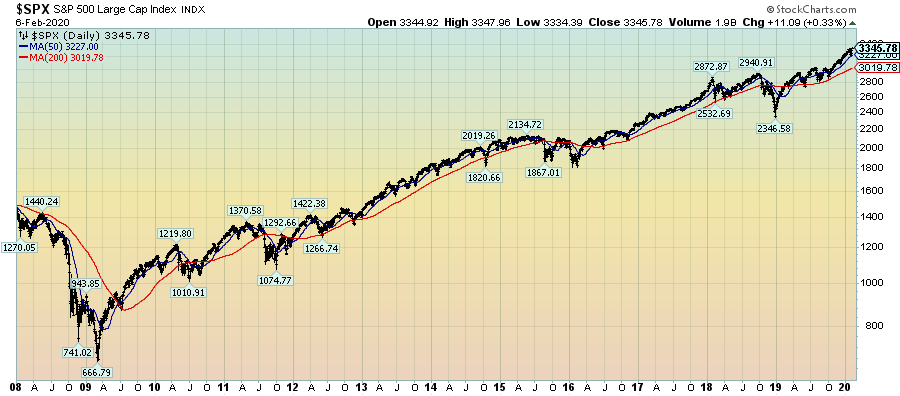
As reference, below is a daily chart since 2008 of the S&P500 (through February 6, 2020 with a last price of 3345.78), depicted on a LOG scale, indicating both the 50dma and 200dma as well as price labels:
(click on chart to enlarge image)(chart courtesy of StockCharts.com; chart creation and annotation by the author)
S&P500 since 2008 chart
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 3345.78 as this post is written