Shortly after each monthly employment report I have been posting a continual series titled “3 Critical Unemployment Charts.”
Of course, there are many other employment charts that can be displayed as well.
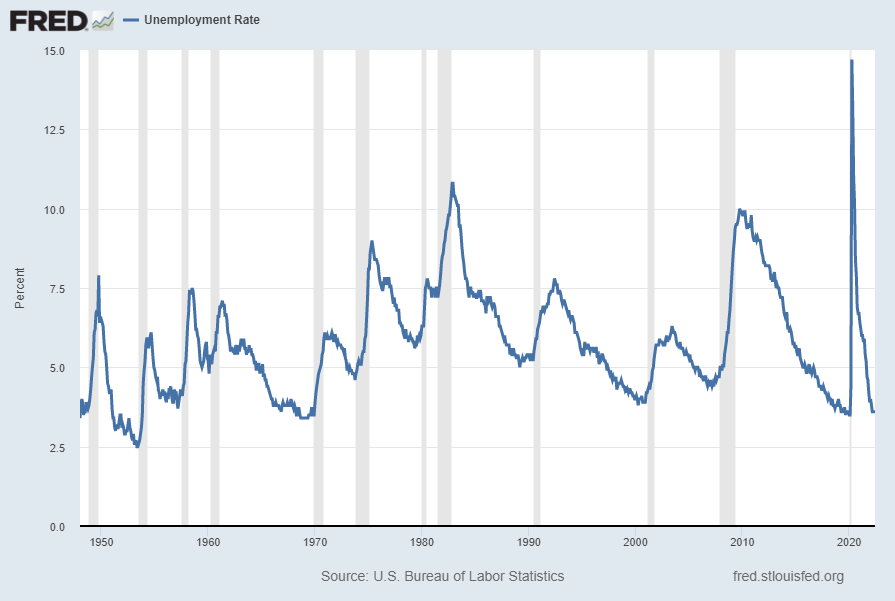
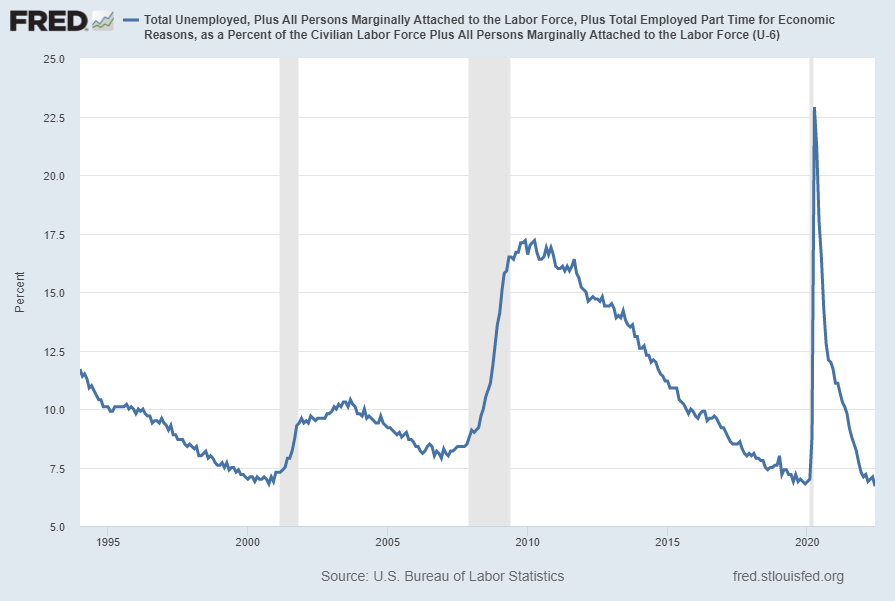
For reference purposes, below are the U-3 and U-6 Unemployment Rate charts from a long-term historical perspective. Both charts are from the St. Louis Fed site. The U-3 measure is what is commonly referred to as the official unemployment rate; whereas the U-6 rate is officially (per Bureau of Labor Statistics) defined as:
Total unemployed, plus all persons marginally attached to the labor force, plus total employed part time for economic reasons, as a percent of the civilian labor force plus all persons marginally attached to the labor force
Of note, many economic observers use the U-6 rate as a (closer) proxy of the actual unemployment rate rather than that depicted by the U-3 measure.
Here is the U-3 chart, currently showing a 3.6% unemployment rate:
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis: Civilian Unemployment Rate [UNRATE] ; U.S. Department of Labor: Bureau of Labor Statistics; accessed July 8, 2022: http://research.stlouisfed.org/fred2/series/UNRATE
–
Here is the U-6 chart, currently showing a 6.7% unemployment rate:
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis: Total unemployed, plus all marginally attached workers plus total employed part time for economic reasons [U6RATE] ; U.S. Department of Labor: Bureau of Labor Statistics; accessed July 8, 2022: http://research.stlouisfed.org/fred2/series/U6RATE
_____
The Special Note summarizes my overall thoughts about our economic situation
As I have commented previously, as in the October 6, 2009 post (“A Note About Unemployment Statistics”), in my opinion the official methodologies used to measure the various job loss and unemployment statistics do not provide an accurate depiction; they serve to understate the severity of unemployment.
However, even if one chooses to look at the official statistics, the following charts provide an interesting (and disconcerting) long-term perspective of certain aspects of the officially-stated unemployment (and, in the third chart, employment) situation.
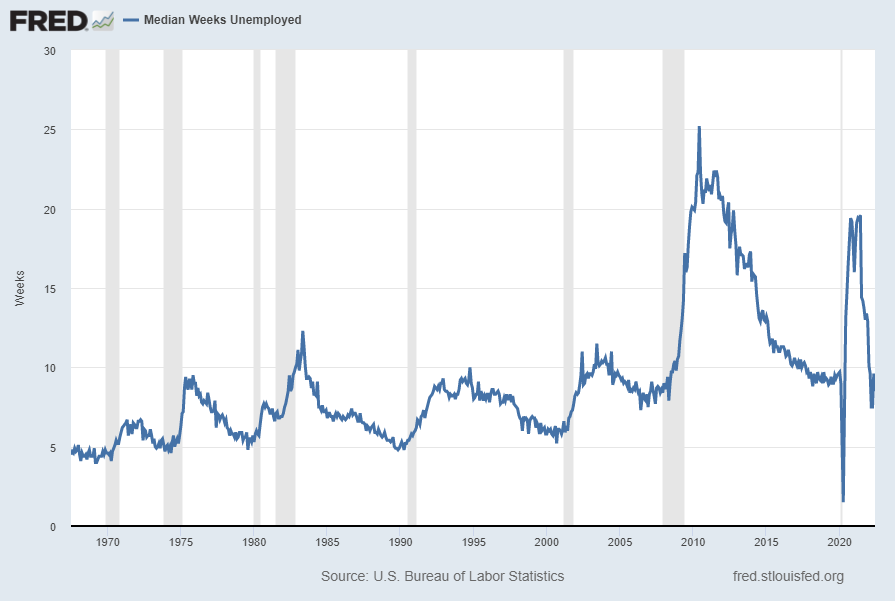
The three charts below are from the St. Louis Fed site. Here is the Median Duration of Unemployment (current value = 8.5 weeks):
(click on charts to enlarge images)(charts updated as of 7-8-22)
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis: Median Duration of Unemployment [UEMPMED] ; U.S. Department of Labor: Bureau of Labor Statistics; accessed July 8, 2022: http://research.stlouisfed.org/fred2/series/UEMPMED
–
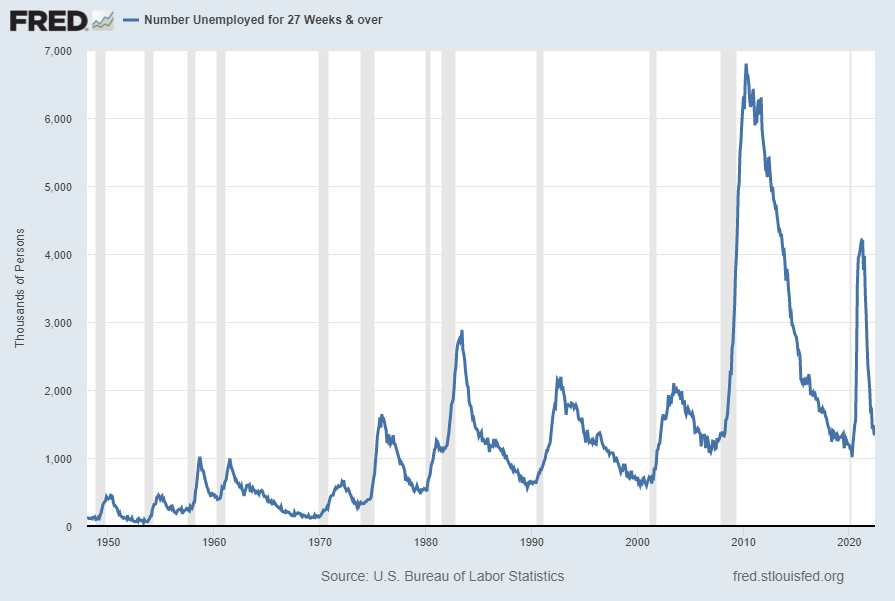
Here is the chart for Unemployed 27 Weeks and Over (current value = 1.336 million):
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis: Civilians Unemployed for 27 Weeks and Over [UEMP27OV] ; U.S. Department of Labor: Bureau of Labor Statistics; accessed July 8, 2022: http://research.stlouisfed.org/fred2/series/UEMP27OV
–
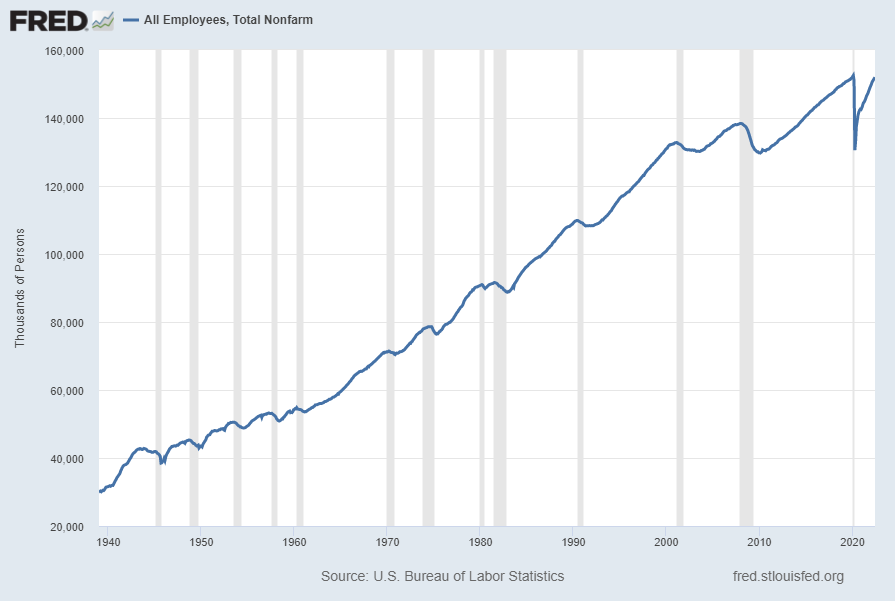
Here is the chart for Total Nonfarm Payroll (current value = 151.980 million):
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis: All Employees: Total Nonfarm [PAYEMS] ; U.S. Department of Labor: Bureau of Labor Statistics; accessed July 8, 2022: https://research.stlouisfed.org/fred2/series/PAYEMS
–
Our unemployment problem is severe. The underlying dynamics of the current – and especially future – unemployment situation remain exceedingly worrisome. These dynamics are numerous and complex, and greatly lack recognition and understanding.
My commentary regarding unemployment is generally found in the “Unemployment” category. This commentary includes the page titled “U.S. Unemployment Trends,” which discusses various problematical issues concerning the present and future employment situation.
_____
The Special Note summarizes my overall thoughts about our economic situation
Throughout this site there are many discussions of economic indicators. This post is the latest in a series of posts indicating facets of U.S. economic weakness or a notably low growth rate.
The level and trend of economic growth is especially notable at this time. As seen in various estimates, the probability of recession has grown to significant levels.
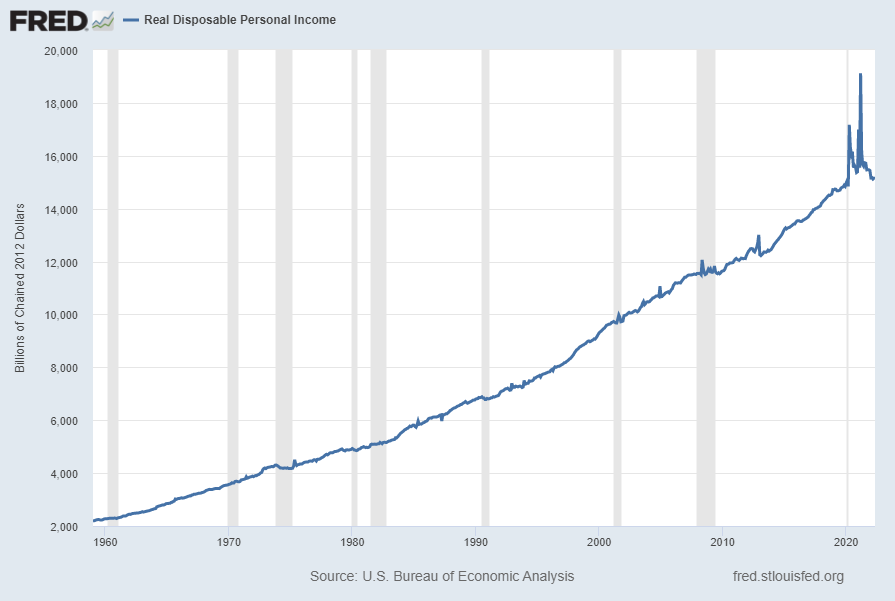
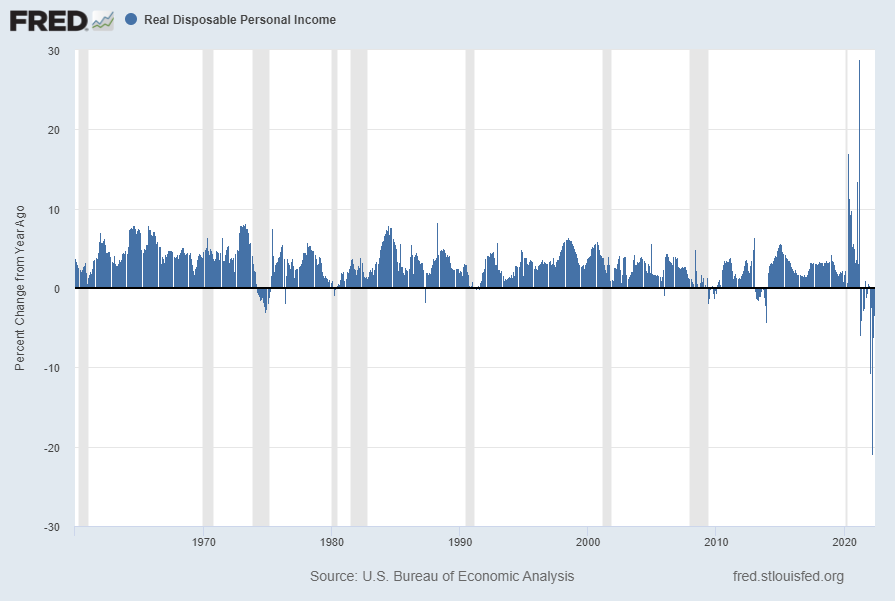
“Real Disposable Personal Income” (DSPIC96) has been volatile since 2020, and ongoing high inflation is presenting a hurdle to its continued growth. Shown below is this measure with last value of $15,144.8 Billion through May, last updated June 30, 2022:
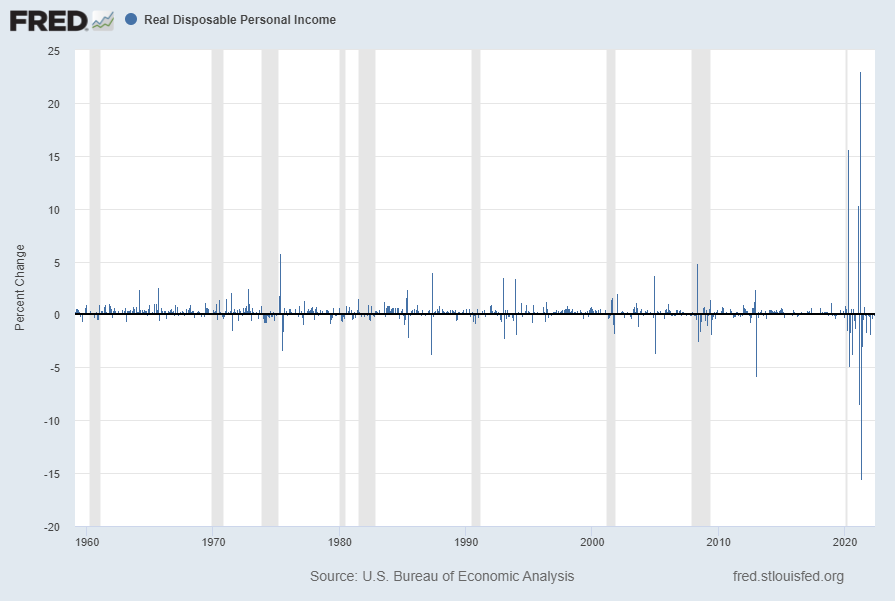
Below is this measure displayed on a “Percent Change” (from prior month) basis with last value of -.1%:
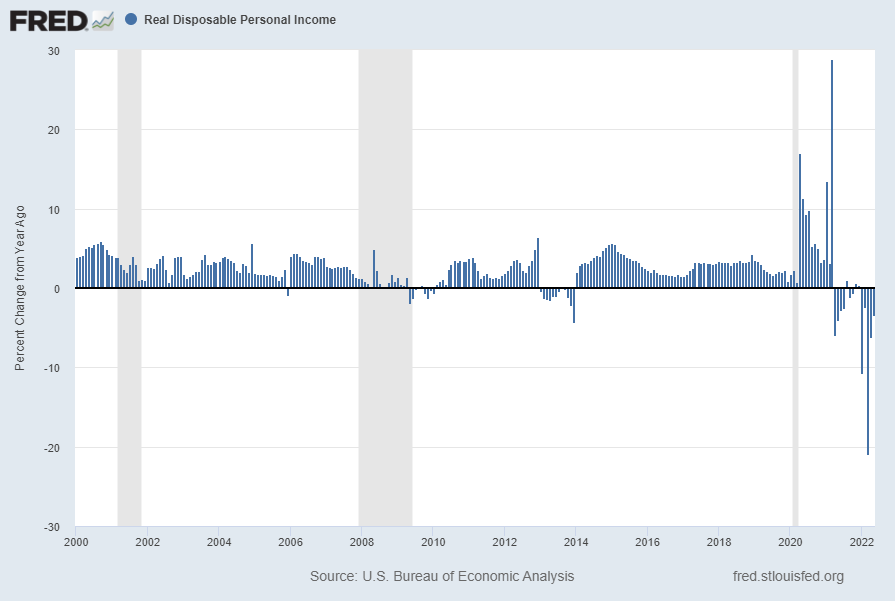
Below is this measure displayed on a “Percent Change From Year Ago” basis with value -3.3%:
Below is this same measure (“Percent Change From Year Ago” basis) but from the year 2000 onward:
source: U.S. Bureau of Economic Analysis, Real Disposable Personal Income [DSPIC96], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed July 6, 2022: https://fred.stlouisfed.org/series/DSPIC96
__
The Yield Curve (T10Y2Y)
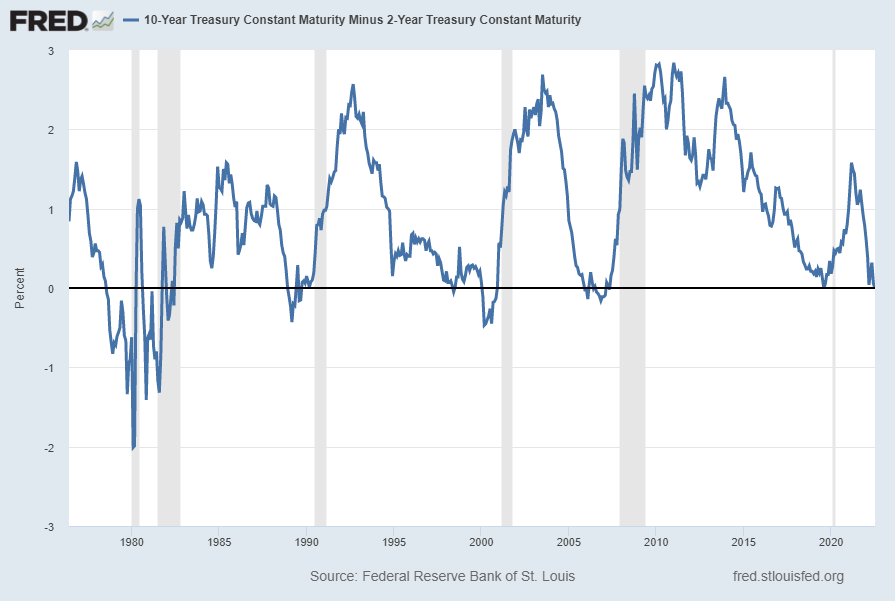
Many people believe that the Yield Curve is a leading economic indicator for the United States economy.
While I continue to have the stated reservations regarding the “Yield Curve” as an indicator, I do believe that it should be monitored.
The U.S. Yield Curve (one proxy seen below) while positive, is (all things considered) notably low when viewed from a long-term perspective. Below is the spread between the 10-Year Treasury Constant Maturity and the 2-Year Treasury Constant Maturity from June 1976 through the July 5, 2022 value, showing a value of 0.0% [10-Year Treasury Yield (FRED DGS10) of 2.88% as of the July 5 update, 2-Year Treasury Yield (FRED DGS2) of 2.84% as of the July 5 update]:
source: Federal Reserve Bank of St. Louis, 10-Year Treasury Constant Maturity Minus 2-Year Treasury Constant Maturity [T10Y2Y], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed July 6, 2022: https://fred.stlouisfed.org/series/T10Y2Y
__
University of Michigan Consumer Sentiment Index
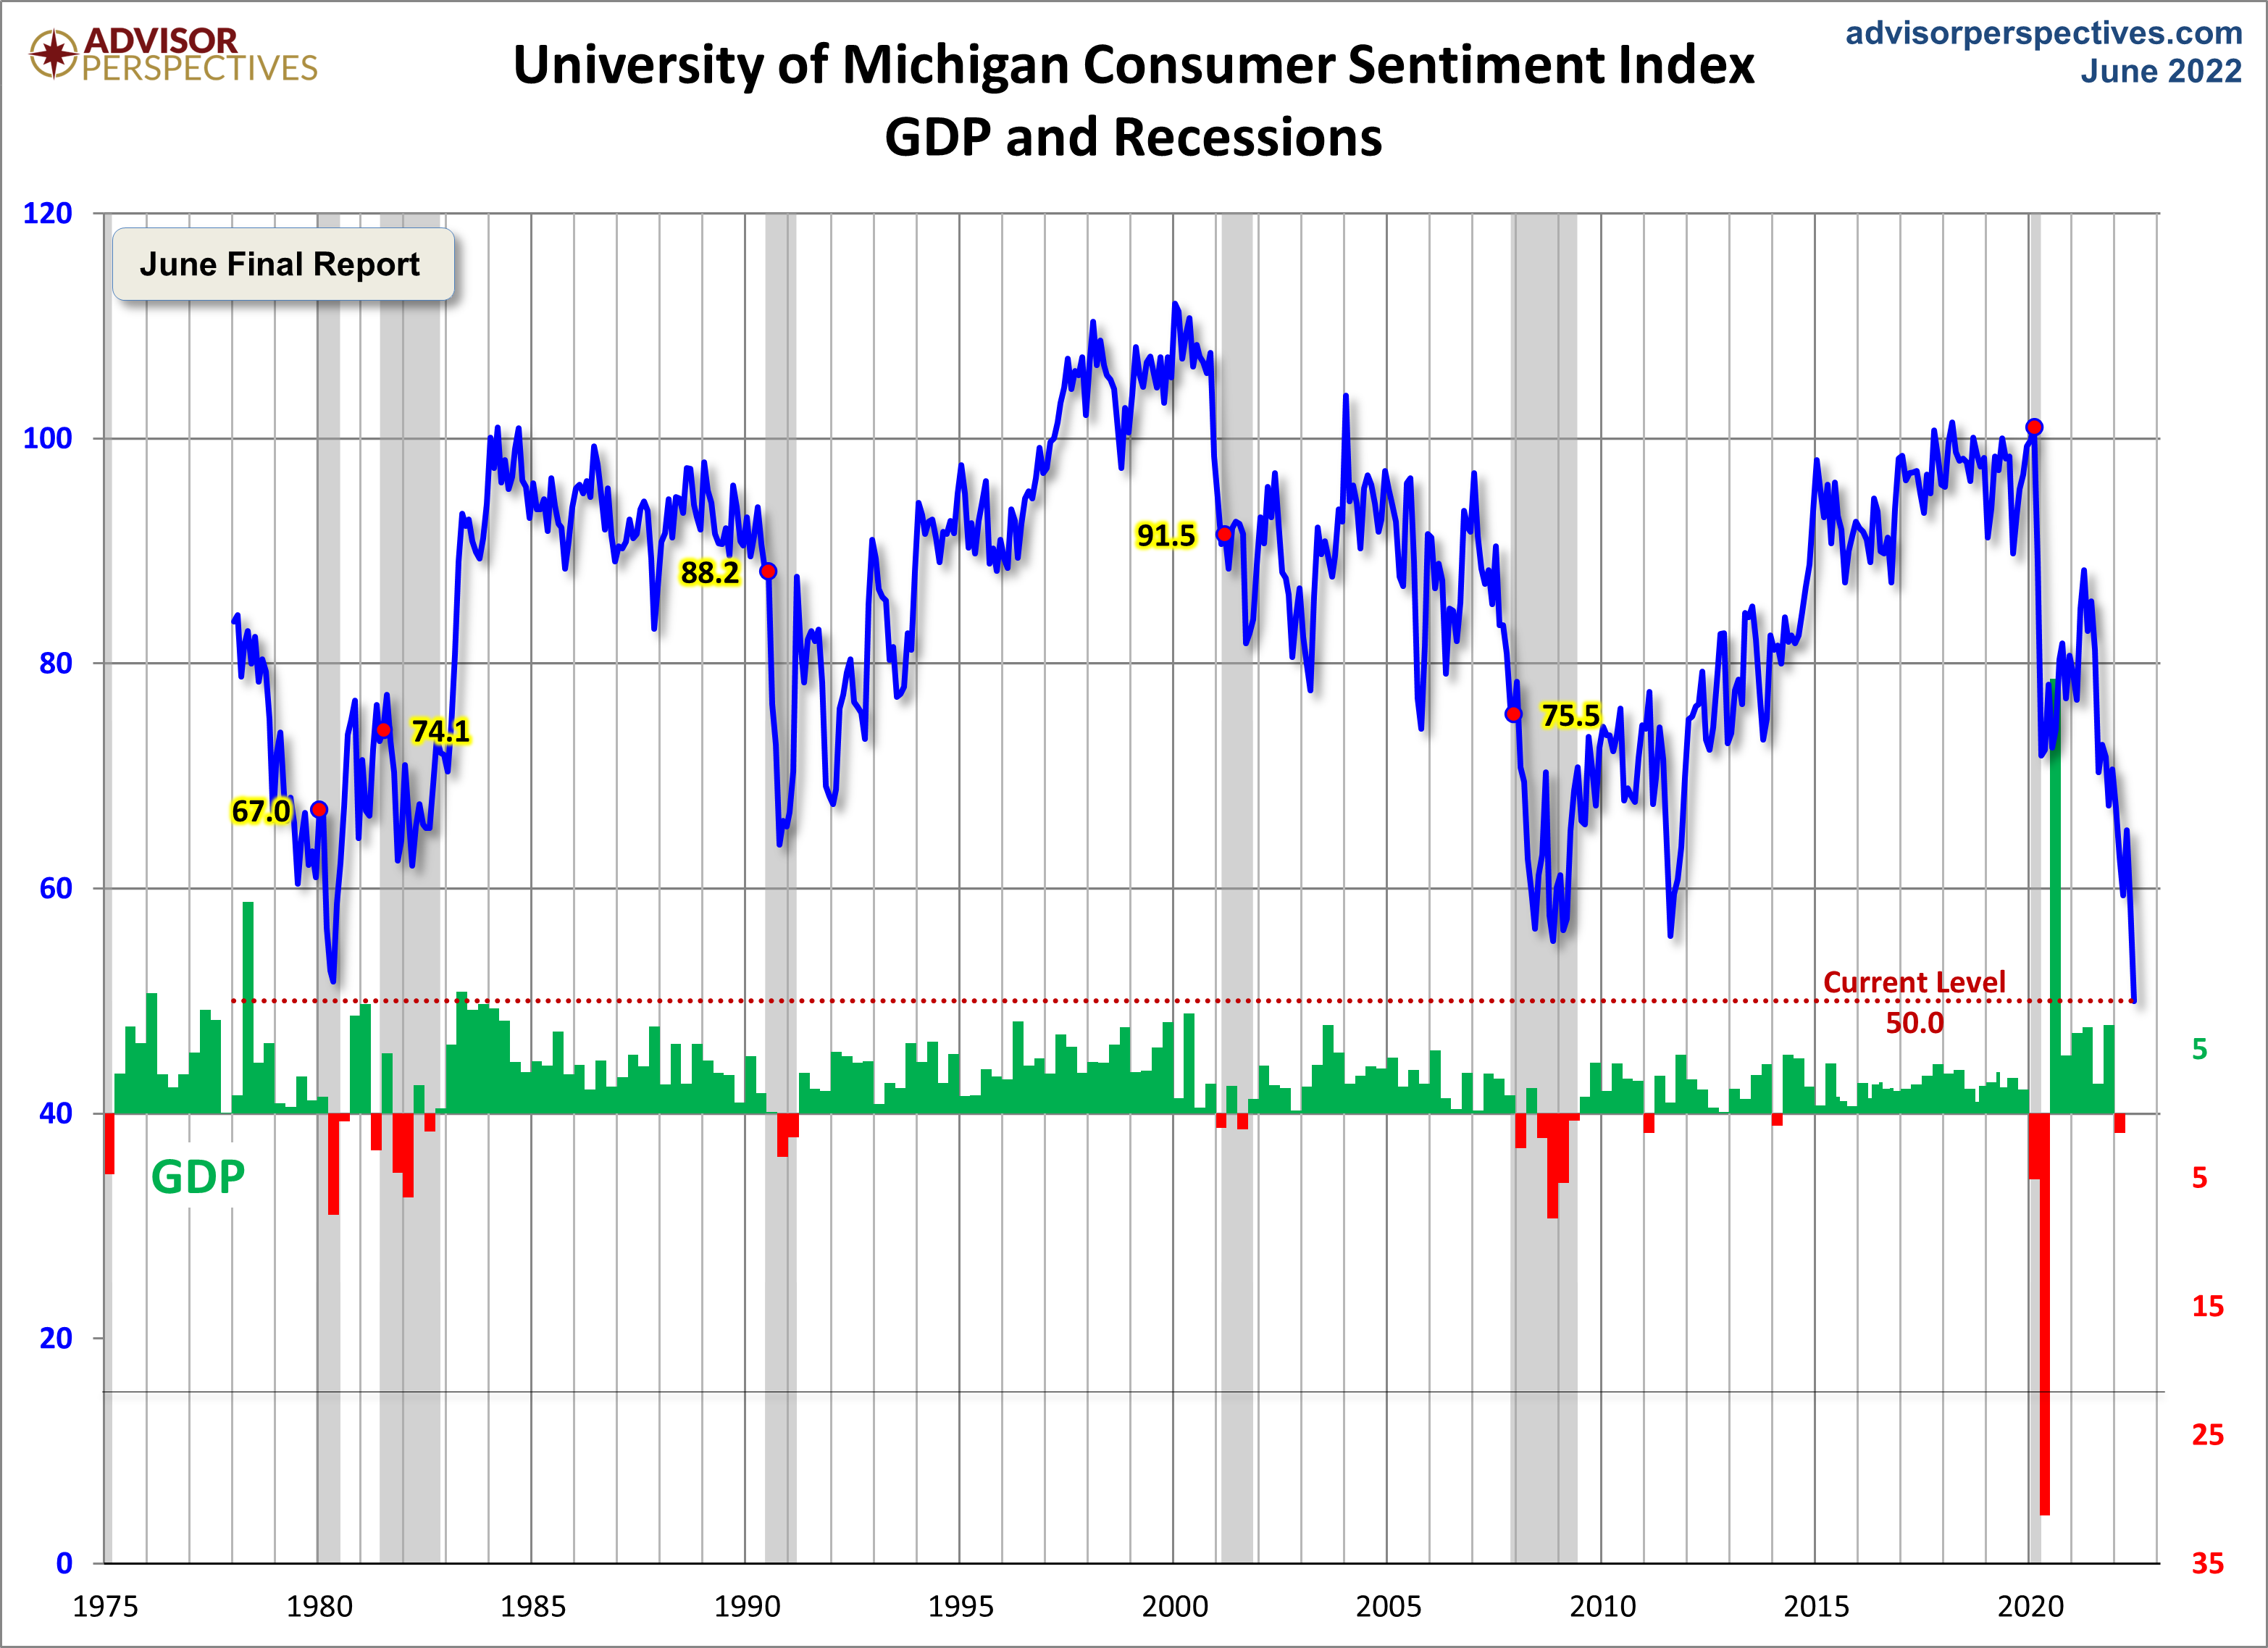
The University of Michigan Consumer Sentiment Index reached a record-low level of 50.0 in June. While, as I have previously stated, I don’t believe that confidence surveys should be overemphasized, I find this level to be notable for several reasons.
As mentioned previously, many other indicators discussed on this site indicate slow economic growth or economic contraction, if not outright (gravely) problematical economic conditions.
_____
The Special Note summarizes my overall thoughts about our economic situation
Below are those two charts, updated through the latest daily closing price.
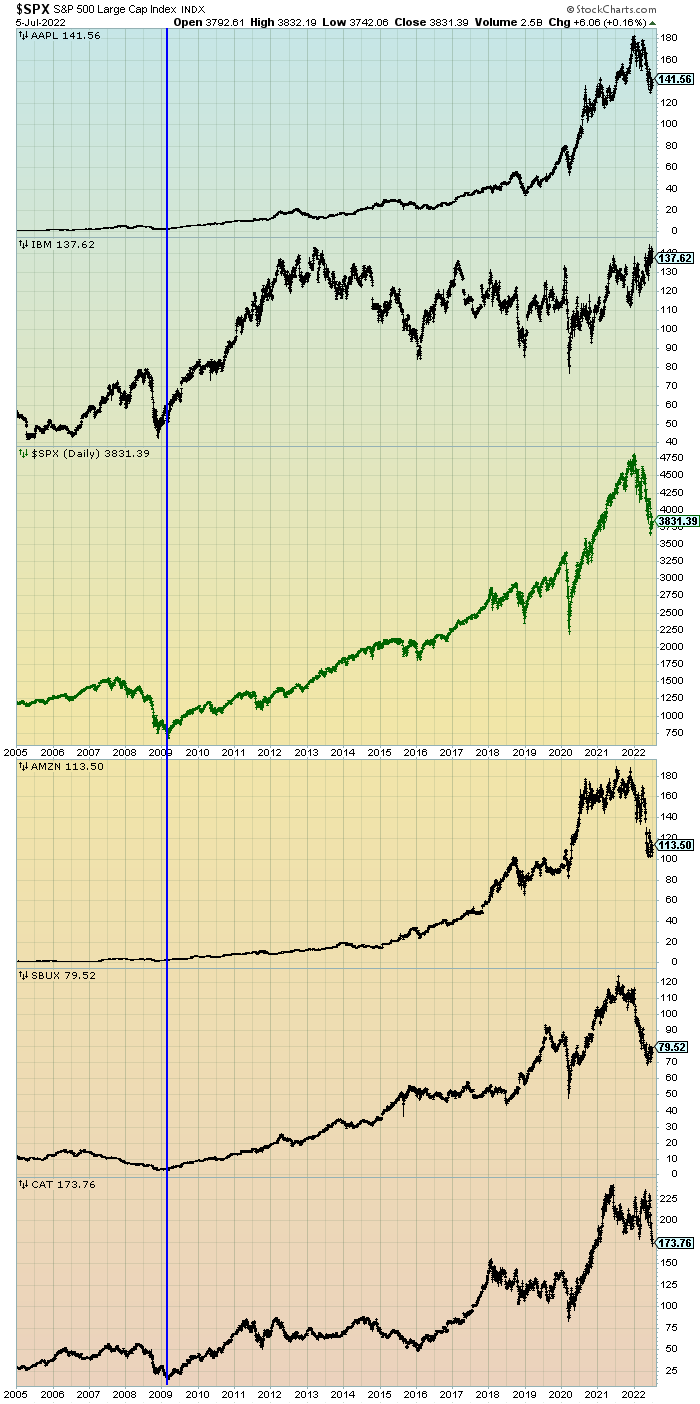
The first is a daily chart of the S&P500 (shown in green), as well as five prominent (AAPL, IBM, AMZN, SBUX, CAT) individual stocks, since 2005. There is a blue vertical line that is very close to the March 6, 2009 low. As one can see, both the S&P500 performance, as well as many stocks including the five shown, have performed strongly since the March 6, 2009 low:
(click on chart to enlarge image)(chart courtesy of StockCharts.com; chart creation and annotation by the author)
–
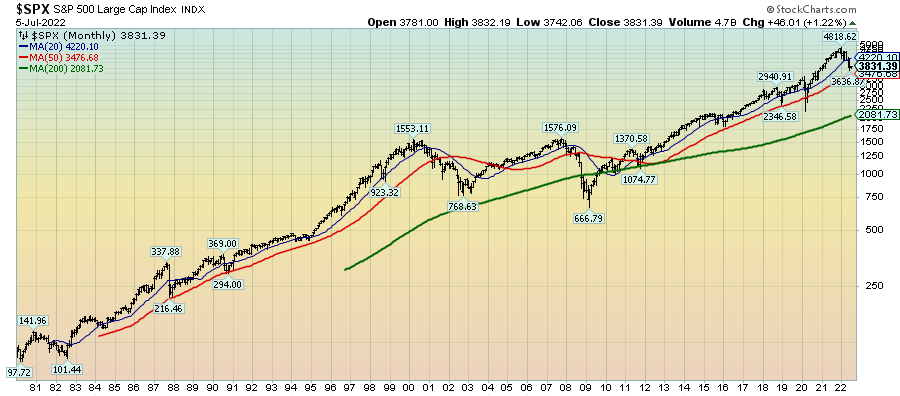
This next chart shows, on a monthly LOG basis, the S&P500 since 1980. I find this chart notable as it provides an interesting long-term perspective on the S&P500′s performance. The 20, 50, and 200-month moving averages are shown in blue, red, and green lines, respectively:
(click on chart to enlarge image)(chart courtesy of StockCharts.com; chart creation and annotation by the author)
_____
The Special Note summarizes my overall thoughts about our economic situation
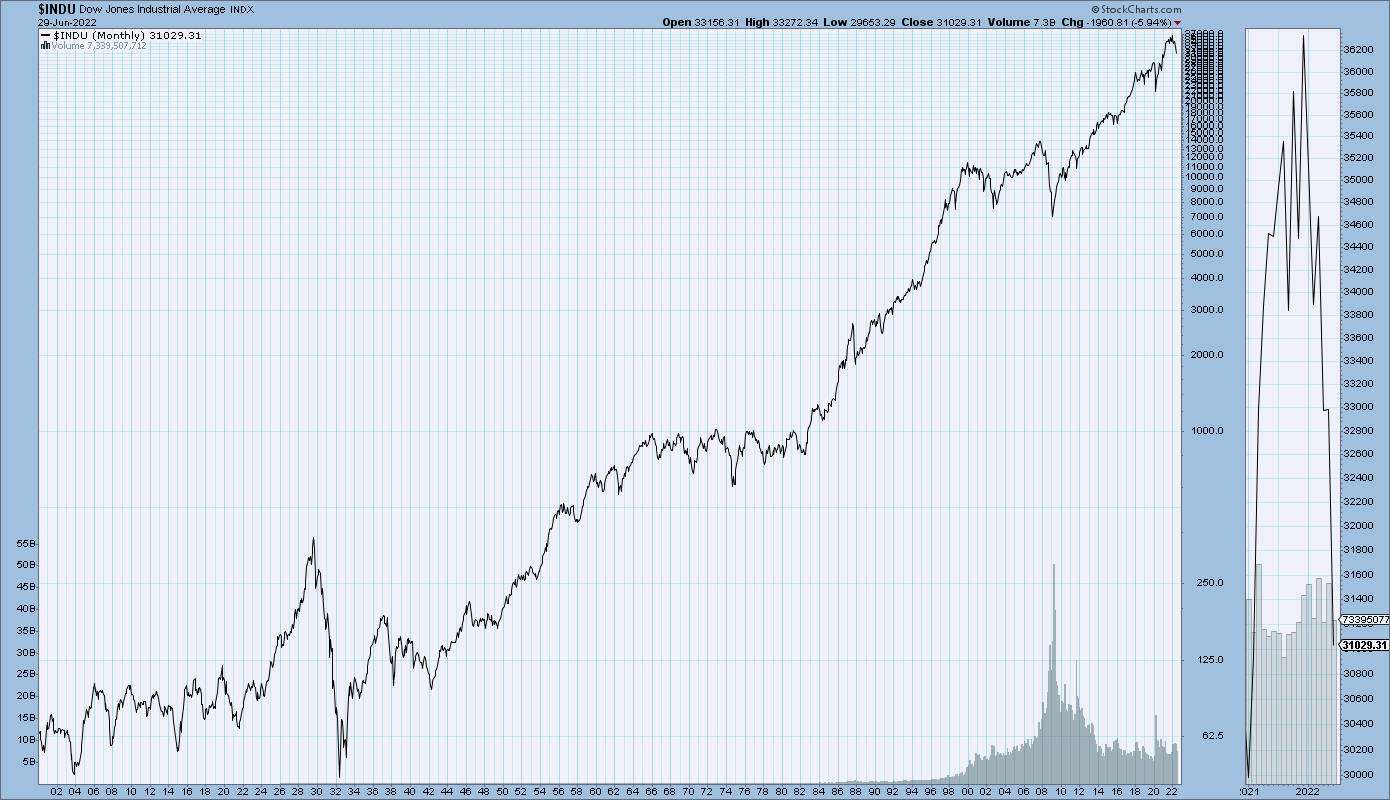
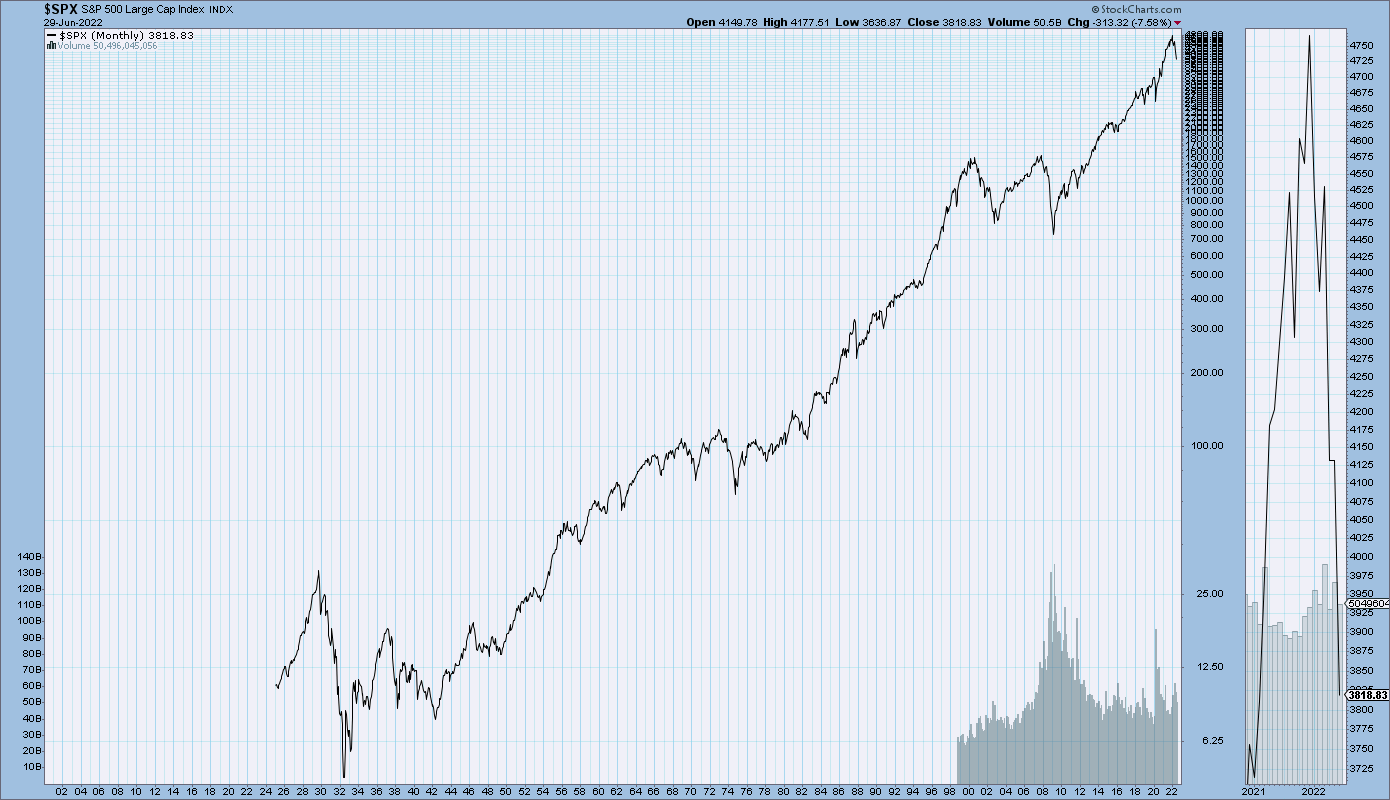
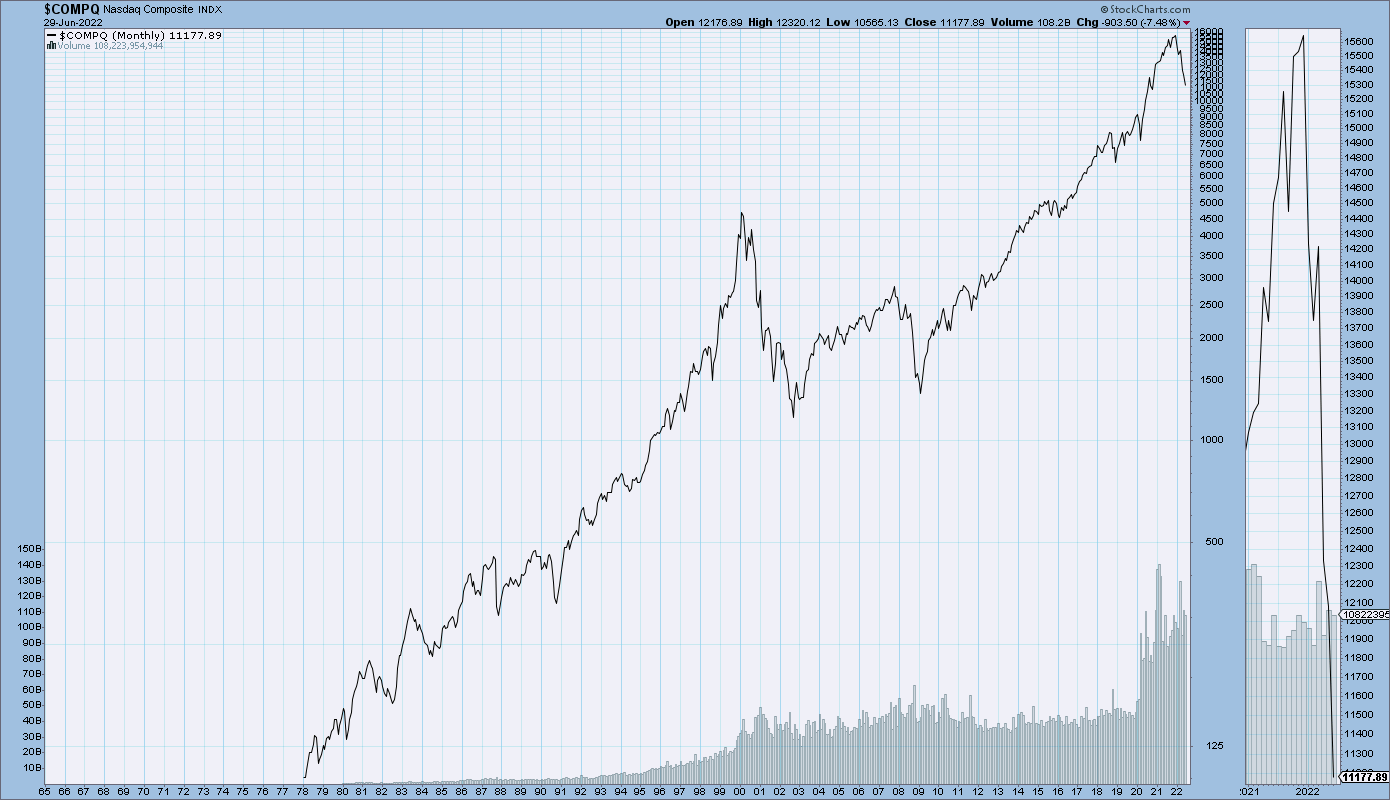
StockCharts.com maintains long-term historical charts of various major stock market indices, interest rates, currencies, commodities, and economic indicators.
As a long-term reference, below are charts depicting various stock market indices for the dates shown. All charts are depicted on a monthly basis using a LOG scale.
(click on charts to enlarge images)(charts courtesy of StockCharts.com)
The Dow Jones Industrial Average, from 1900 – June 29, 2022:
–
The Dow Jones Transportation Average, from 1900 – June 29, 2022:
–
The S&P500, from 1925 – June 29, 2022:
–
The Nasdaq Composite, from 1978 – June 29, 2022:
_____
The Special Note summarizes my overall thoughts about our economic situation
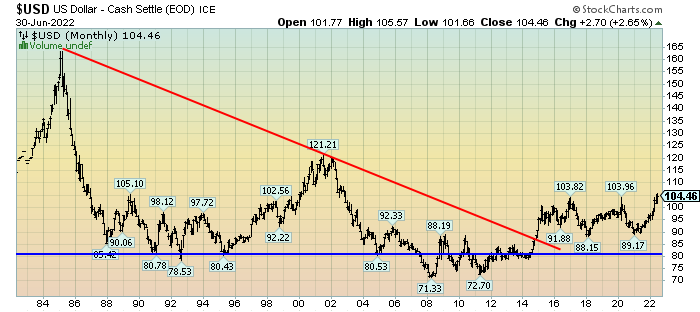
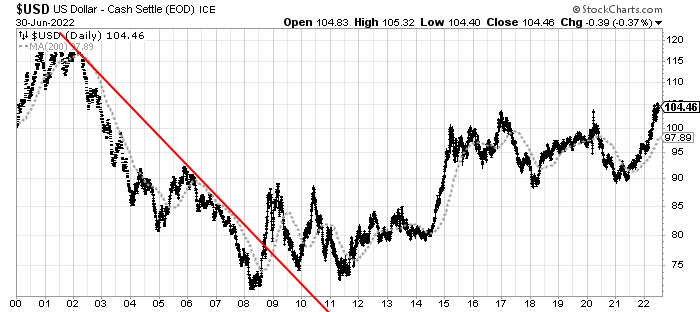
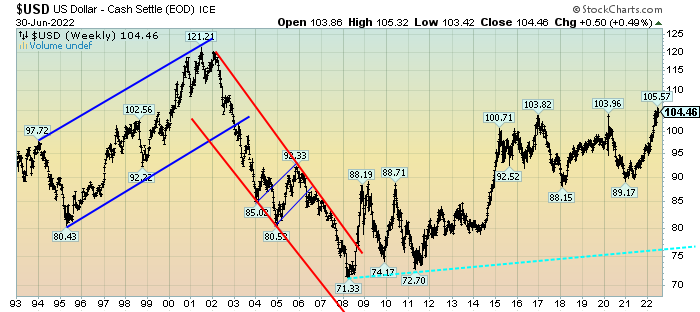
U.S. Dollar weakness is a foremost concern of mine. As such, I have extensively written about it, including commentary on the “A Substantial U.S. Dollar Decline And Consequences” page. I am very concerned that the actions being taken to “improve” our economic situation will dramatically weaken the Dollar. Should the Dollar substantially decline from here, as I expect, the negative consequences will far outweigh any benefits. The negative impact of a substantial Dollar decline can’t, in my opinion, be overstated.
The following three charts illustrate various technical analysis aspects of the U.S. Dollar, as depicted by the U.S. Dollar Index.
First, a look at the monthly U.S. Dollar from 1983. This clearly shows a long-term weakness, with the blue line showing technical support until 2007, and the red line representing a (past) trendline:
(charts courtesy of StockCharts.com; annotations by the author)
(click on charts to enlarge images)
–
Next, another chart, this one focused on the daily U.S. Dollar since 2000 on a LOG scale. The red line represents a (past) trendline. The gray dotted line is the 200-day M.A. (moving average):
–
Lastly, a chart of the Dollar on a weekly LOG scale. There are two clearly marked past channels, with possible technical support depicted by the dashed light blue line:
–
I will continue providing updates on this U.S. Dollar situation regularly as it deserves very close monitoring…
_____
The Special Note summarizes my overall thoughts about our economic situation
Various surveys, economic growth projections, and market risk indicators portrayed a short period (through mid-2020) of substantial U.S. economic decline, and now indicate sustained economic growth and financial stability for the foreseeable future.
However, there are various indications – many of which have been discussed on this site – that this very widely-held consensus is in many ways incorrect. There are many exceedingly problematical financial conditions that have existed prior to 2020, and continue to exist. As well, numerous economic dynamics continue to be exceedingly worrisome and many economic indicators have portrayed facets of weak growth or outright decline currently as well as prior to 2020.
Of paramount importance is the resulting level of risk and the future economic implications.
From an “all things considered” standpoint, I continue to believe the overall level of risk remains at a fantastic level – one that is far greater than that experienced at any time in the history of the United States.
Cumulatively, these highly problematical conditions will lead to future upheaval. The extent of the resolution of these problematical conditions will determine the ongoing viability of the financial system and economy as well as the resultant quality of living.
My analyses continues to indicate that the growing level of financial danger will lead to the next stock market crash that will also involve (as seen in 2008) various other markets as well. Key attributes of this next crash is its outsized magnitude (when viewed from an ultra-long term historical perspective) and the resulting economic impact. This next financial crash is of tremendous concern, as my analyses indicate it will lead to a Super Depression – i.e. an economy characterized by deeply embedded, highly complex, and difficult-to-solve problems.
_____
The Special Note summarizes my overall thoughts about our economic situation