Thursday, March 7, 2024

Chicago Fed National Financial Conditions Index (NFCI)

The St. Louis Fed’s Financial Stress Index (STLFSI4) is one index that is supposed to measure stress in the financial system. Its reading as of the March 7, 2024 update (reflecting data through March 1, 2024) is -.7760:
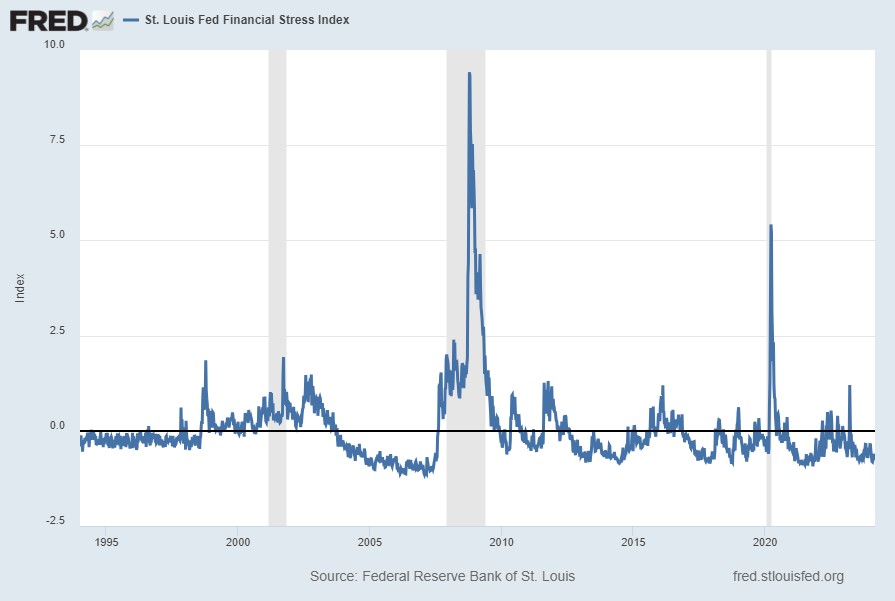
STLFSI4

source: Federal Reserve Bank of St. Louis, St. Louis Fed Financial Stress Index [STLFSI4], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed March 7, 2024: https://fred.stlouisfed.org/series/STLFSI4

Of course, there are a variety of other measures and indices that are supposed to measure financial stress and other related issues, both from the Federal Reserve as well as from private sources.

Two other indices that I regularly monitor include the Chicago Fed National Financial Conditions Index (NFCI) as well as the Chicago Fed Adjusted National Financial Conditions Index (ANFCI).

Here are summary descriptions of each, as seen in FRED:

The National Financial Conditions Index (NFCI) measures risk, liquidity and leverage in money markets and debt and equity markets as well as in the traditional and “shadow” banking systems. Positive values of the NFCI indicate financial conditions that are tighter than average, while negative values indicate financial conditions that are looser than average.

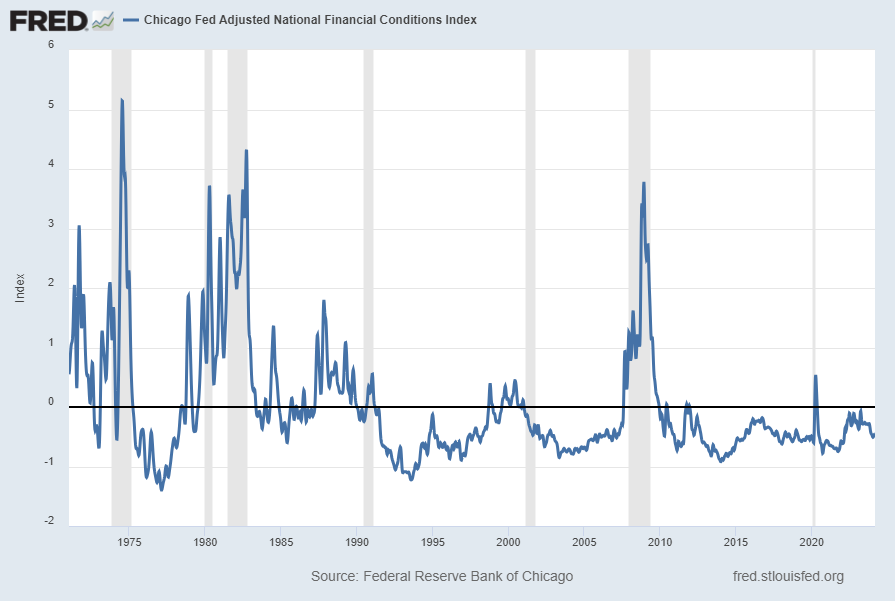
The adjusted NFCI (ANFCI). This index isolates a component of financial conditions uncorrelated with economic conditions to provide an update on how financial conditions compare with current economic conditions.

For further information, please visit the Federal Reserve Bank of Chicago’s web site:

http://www.chicagofed.org/webpages/publications/nfci/index.cfm

Below are the most recently updated charts of the NFCI and ANFCI, respectively.

The NFCI chart below was last updated on March 6, 2024 incorporating data from January 8, 1971 through March 1, 2024 on a weekly basis.  The March 1 value is -.46829:
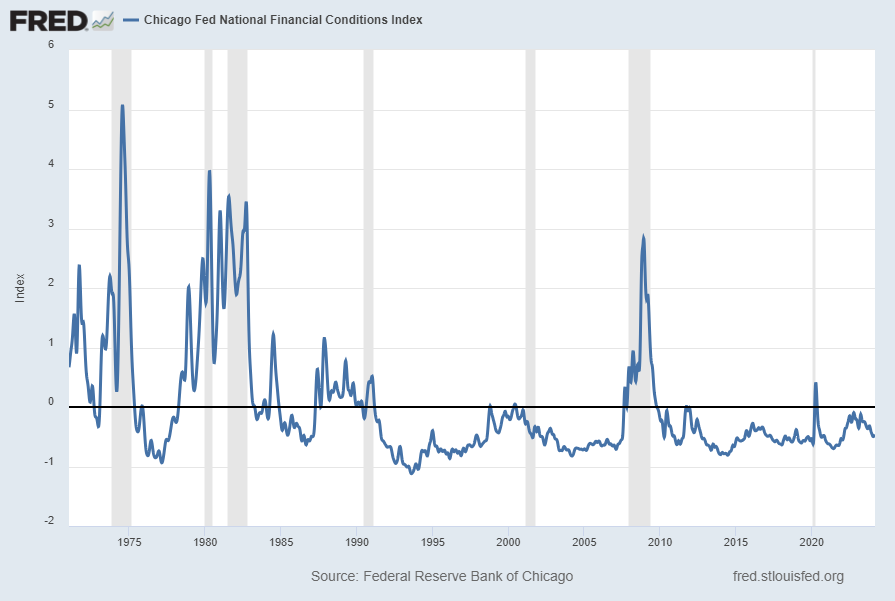
NFCI

Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis; accessed March 7, 2024:  
http://research.stlouisfed.org/fred2/series/NFCI

–

The ANFCI chart below was last updated on March 6, 2024 incorporating data from January 8, 1971 through March 1, 2024, on a weekly basis.  The March 1, 2024 value is -.45390:
ANFCI

Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis; accessed March 7, 2024:  
http://research.stlouisfed.org/fred2/series/ANFCI

_________

I post various indicators and indices because I believe they should be carefully monitored.  However, as those familiar with this site are aware, I do not necessarily agree with what they depict or imply.

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 5151.02 as this post is written

Wednesday, March 6, 2024

Charts Indicating Economic Weakness – March 2024

Throughout this site there are many discussions of economic indicators.  This post is the latest in a series of posts indicating facets of U.S. economic weakness or a notably low growth rate.

The level and trend of economic growth is especially notable at this time. As seen in various sources, recession estimates have been at high levels.

As seen in the January 2024 Wall Street Journal Economic Forecast Survey the consensus (average estimate) among various economists is for 2.65% GDP in 2023, 1.01% GDP in 2024, 1.99% GDP in 2025, and 2.01% in 2026.

Charts Indicating U.S. Economic Weakness

Below is a small sampling of charts that depict weak growth or contraction, and a brief comment for each:

The Yield Curve (T10Y2Y)

Many people believe that the Yield Curve is a leading economic indicator for the United States economy.

On March 1, 2010, I wrote a post on the issue, titled “The Yield Curve As A Leading Economic Indicator.”

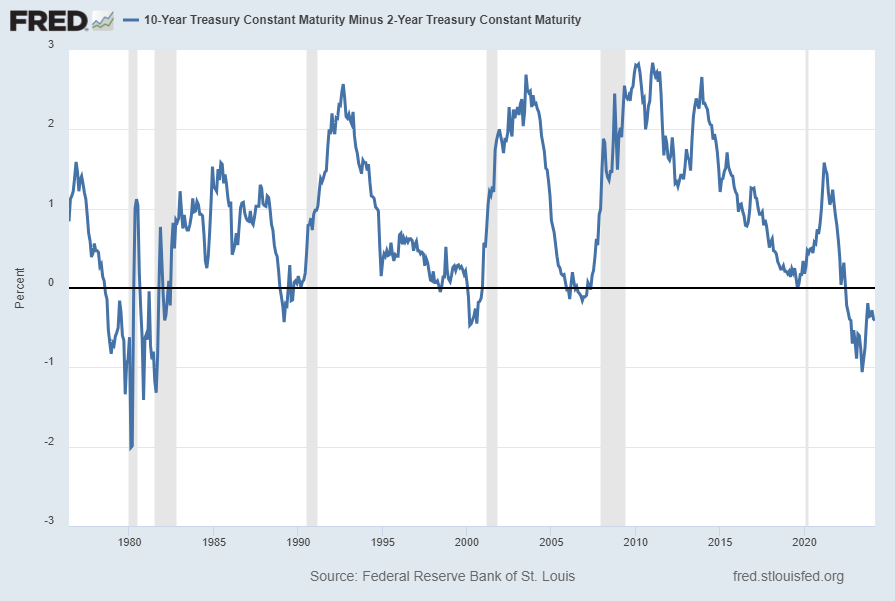
While I continue to have the stated reservations regarding the “Yield Curve” as an indicator, I do believe that it should be monitored.

The U.S. Yield Curve (one proxy seen below) is (all things considered) notably inverted when viewed from a long-term perspective. Below is the spread between the 10-Year Treasury Constant Maturity and the 2-Year Treasury Constant Maturity from June 1976 through the March 5, 2024 update, showing a value of -.41% [10-Year Treasury Yield (FRED DGS10) of 4.22% as of the March 4 update, 2-Year Treasury Yield (FRED DGS2) of 4.61% as of the March 4 update]:

T102Y

source: Federal Reserve Bank of St. Louis, 10-Year Treasury Constant Maturity Minus 2-Year Treasury Constant Maturity [T10Y2Y], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed March 6, 2024: https://fred.stlouisfed.org/series/T10Y2Y

__

Value of Manufacturers’ New Orders for Consumer Goods Industries (ACOGNO)

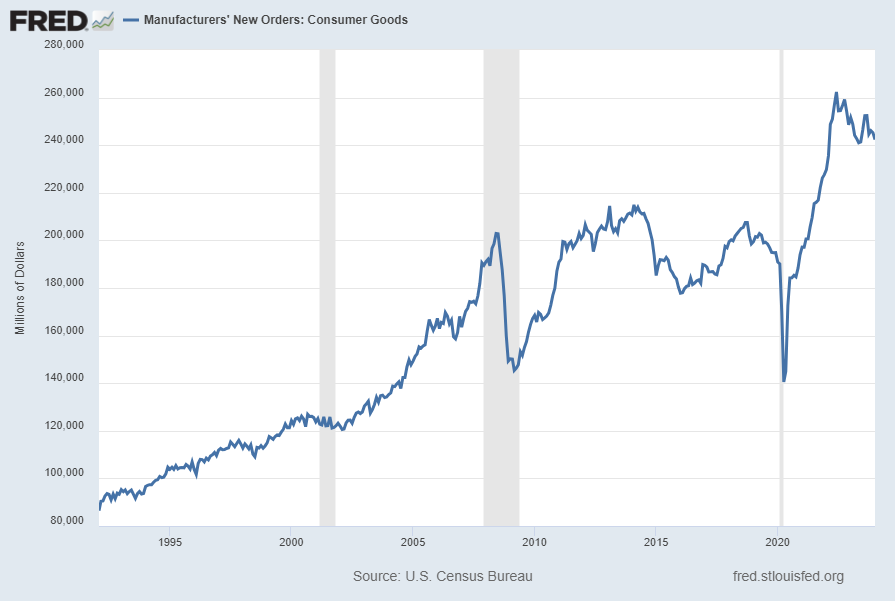
A measure for consumer goods exhibiting a recent peak is the “Value of Manufacturers’ New Orders for Consumer Goods Industries” (ACOGNO). Shown below is this measure with last value of 242,321 ($ Millions) through January 2024 (last updated March 5, 2024):

ACOGNO

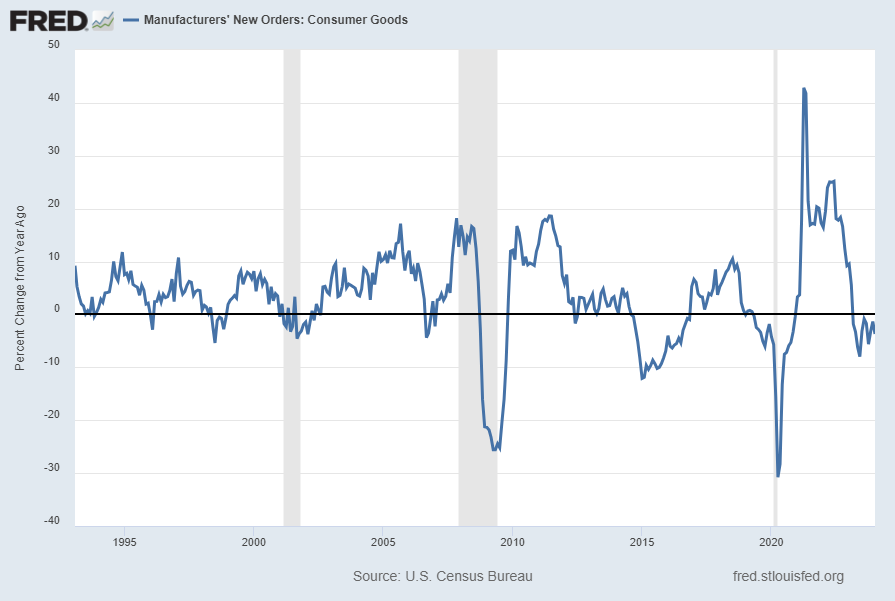
Displayed below is this same ACOGNO measure on a “Percent Change From Year Ago” basis with value -3.7%:

ACOGNO Percent Change From Year Ago

source:  U.S. Census Bureau, Value of Manufacturers’ New Orders for Consumer Goods Industries [ACOGNO], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed March 5, 2024:  https://fred.stlouisfed.org/series/ACOGNO

__

All Employees, Temporary Help Services (TEMPHELPS)

I have written extensively about many facets of employment and unemployment, as the current and future unemployment issue is of tremendous importance yet is in many ways misunderstood.

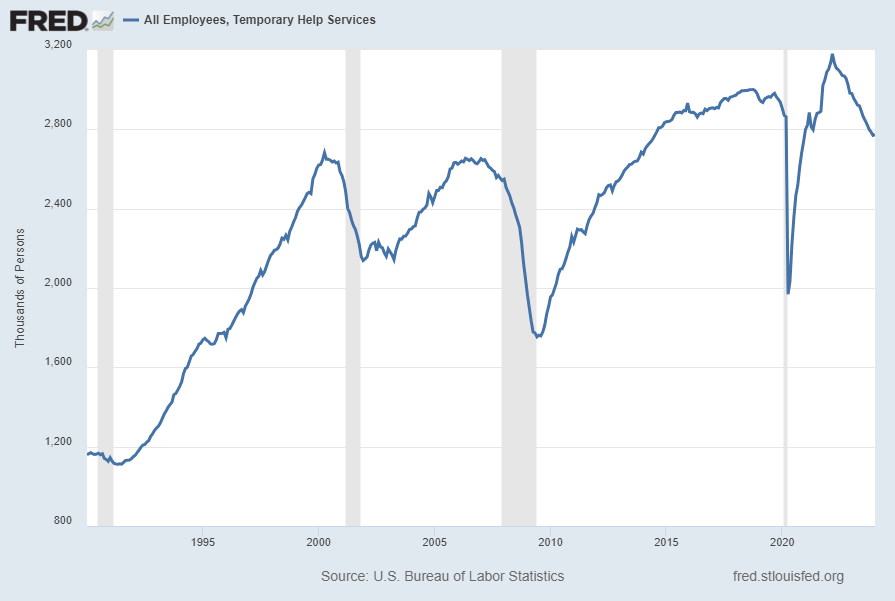
One theory regarding employment is that hiring cycles typically begin with an uptake in temporary employment. Conversely, due to various factors a reduction in temporary employees can be an (early) indicator of lessening labor demand.

Shown below is this measure with last value of 2,772.9 (Thousands) through January, last updated February 2, 2024:

TEMPHELPS

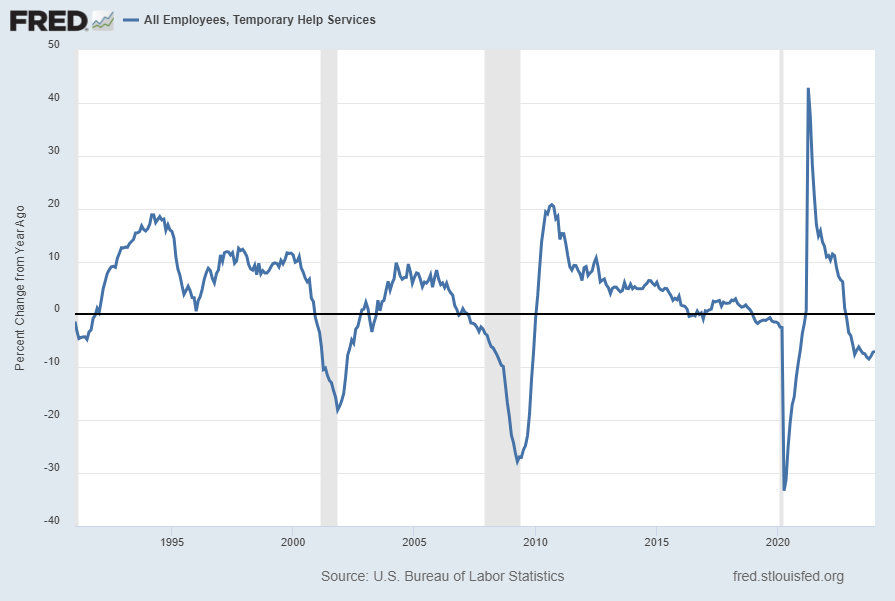
Below is this measure displayed on a “Percent Change From Year Ago” basis with value -7.0%:

TEMPHELPS Percent Change From Year Ago

source: U.S. Bureau of Labor Statistics, All Employees, Temporary Help Services [TEMPHELPS], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed March 5, 2024: https://fred.stlouisfed.org/series/TEMPHELPS

__

Job Openings (JTSJOL)

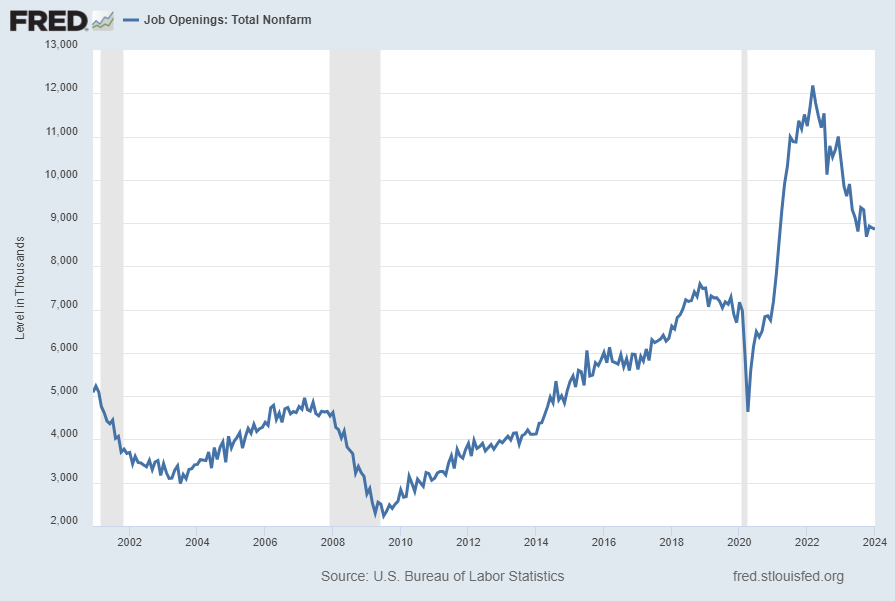
Job openings (Job Openings: Total Nonfarm [JTSJOL]), although still at a (very) high level, have recently declined significantly. This “Job Openings” measure had a value of 8,863 (Thousands) through January 2024 as of the March 6, 2024 update, as shown below:

JTSJOL

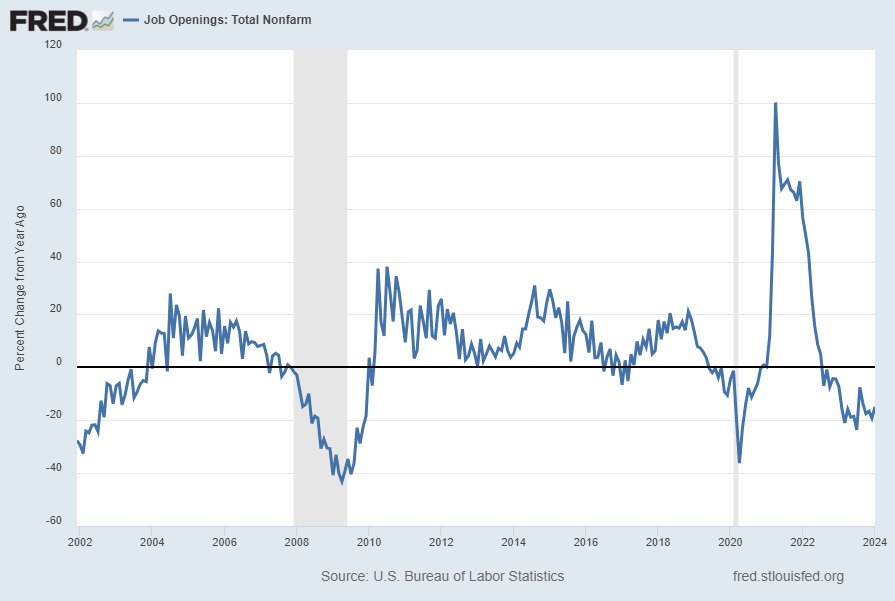
Below is this measure displayed on a “Percent Change From Year Ago” basis with value -15.0%:

JTSJOL Percent Change From Year Ago

source: U.S. Bureau of Labor Statistics, Job Openings: Total Nonfarm [JTSJOL], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed March 6, 2024: https://fred.stlouisfed.org/series/JTSJOL

__

Other Indicators

As mentioned previously, many other indicators discussed on this site indicate weak economic growth or economic contraction, if not outright (gravely) problematical economic conditions.

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 5120.16 as this post is written
Monday, March 4, 2024

VIX Charts Since The Year 2000 – March 4, 2024 Update

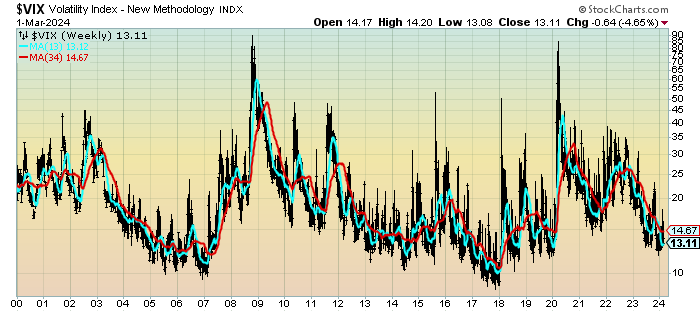
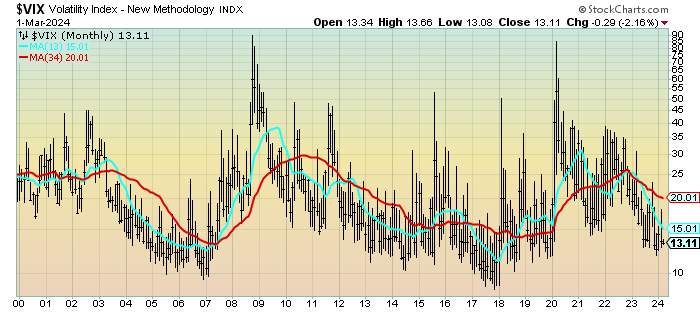
For reference purposes, below are two charts of the VIX from year 2000 through the March 1, 2024 close, which had a value of 13.11.

Here is the VIX Weekly chart, depicted on a LOG scale, with the 13- and 34-week moving averages, seen in the cyan and red lines, respectively:

(click on chart to enlarge image)(chart courtesy of StockCharts.com; chart creation and annotation by the author)

VIX Weekly LOG 13.11

–

Here is the VIX Monthly chart, depicted on a LOG scale, with the 13- and 34-month moving average, seen in the cyan and red lines, respectively:

(click on chart to enlarge image)(chart courtesy of StockCharts.com; chart creation and annotation by the author)

VIX Monthly LOG 13.11

____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 5137.08 as this post is written
S&P500 Charts Since 2009 And 1980 – March 4, 2024 Update

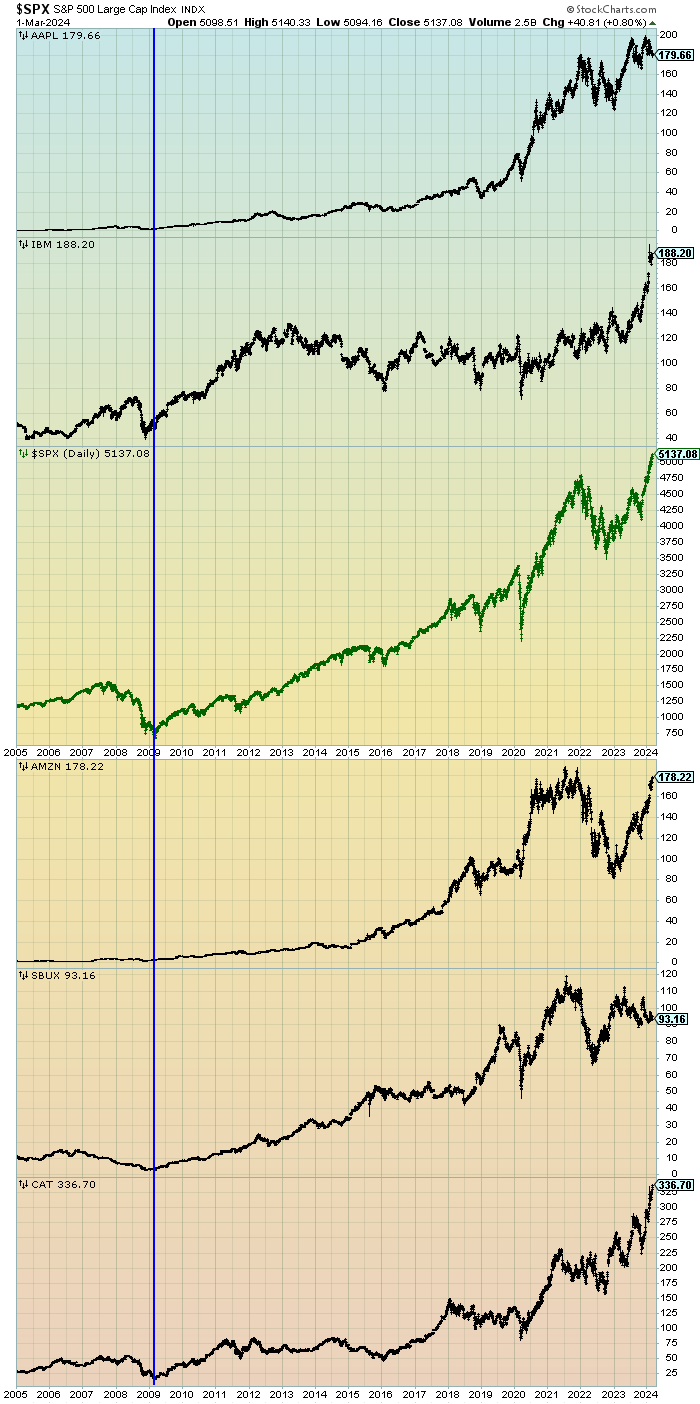
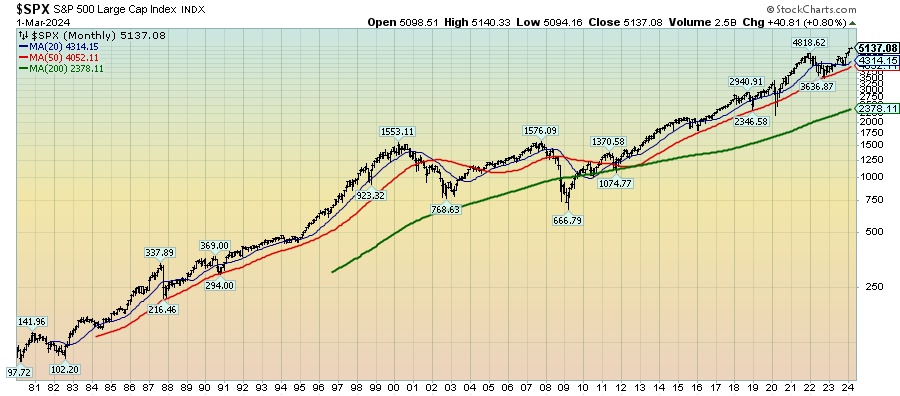
In the March 9, 2012 post (“Charts of Equities’ Performance Since March 9, 2009 And January 1, 1980“) I highlighted two charts for reference purposes.

Below are those two charts, updated through the latest daily closing price.

The first is a daily chart of the S&P500 (shown in green), as well as five prominent (AAPL, IBM, AMZN, SBUX, CAT) individual stocks, since 2005. There is a blue vertical line that is very close to the March 6, 2009 low. As one can see, both the S&P500 performance, as well as many stocks including the five shown, have performed strongly since the March 6, 2009 low:

(click on chart to enlarge image)(chart courtesy of StockCharts.com; chart creation and annotation by the author)

S&P500 and prominent stocks since 2005

–

This next chart shows, on a monthly LOG basis, the S&P500 since 1980.  I find this chart notable as it provides an interesting long-term perspective on the S&P500′s performance.  The 20, 50, and 200-month moving averages are shown in blue, red, and green lines, respectively:

(click on chart to enlarge image)(chart courtesy of StockCharts.com; chart creation and annotation by the author)

S&P500 monthly since 1980

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 5137.08 as this post is written
Long-Term Charts Of U.S. Equity Indexes As Of March 1, 2024

StockCharts.com maintains long-term historical charts of various major stock market indices, interest rates, currencies, commodities, and economic indicators.

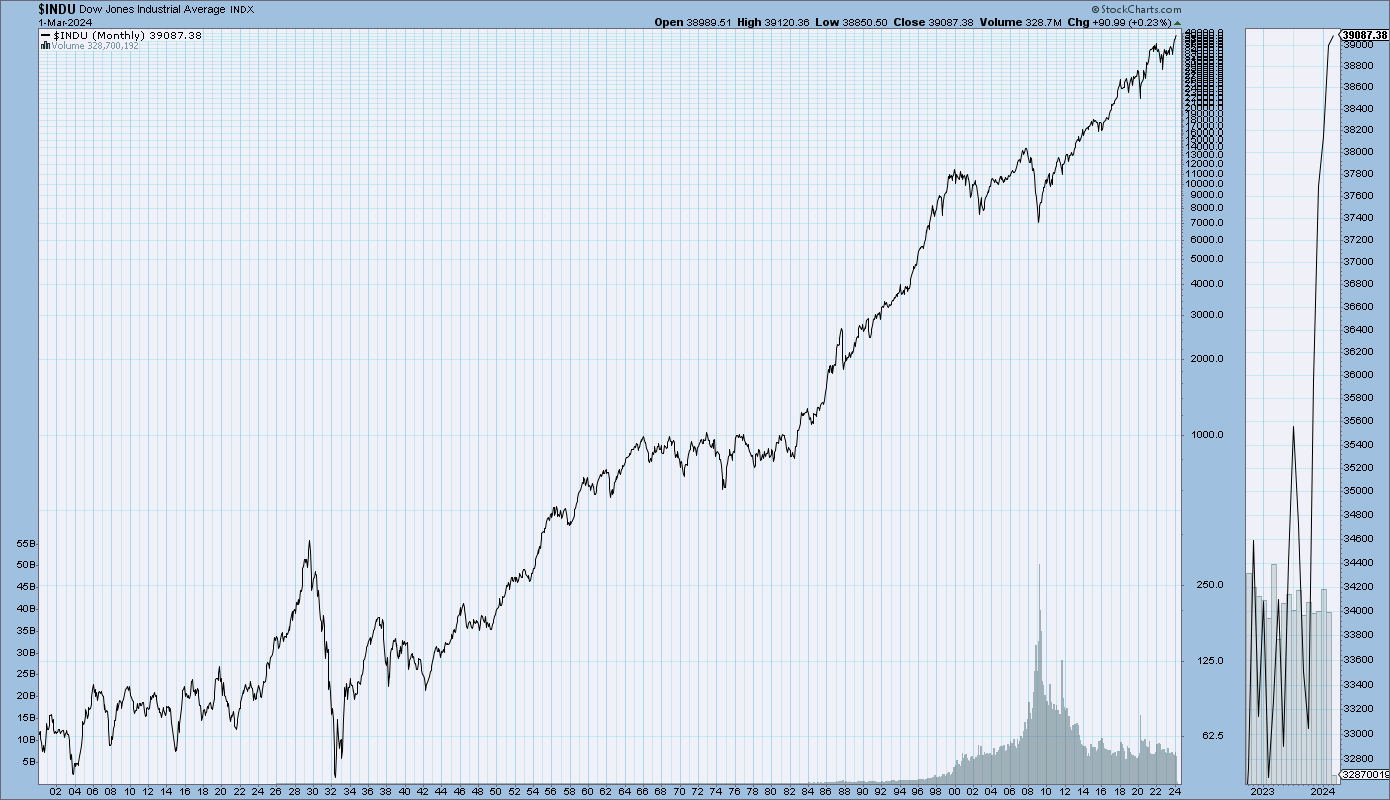
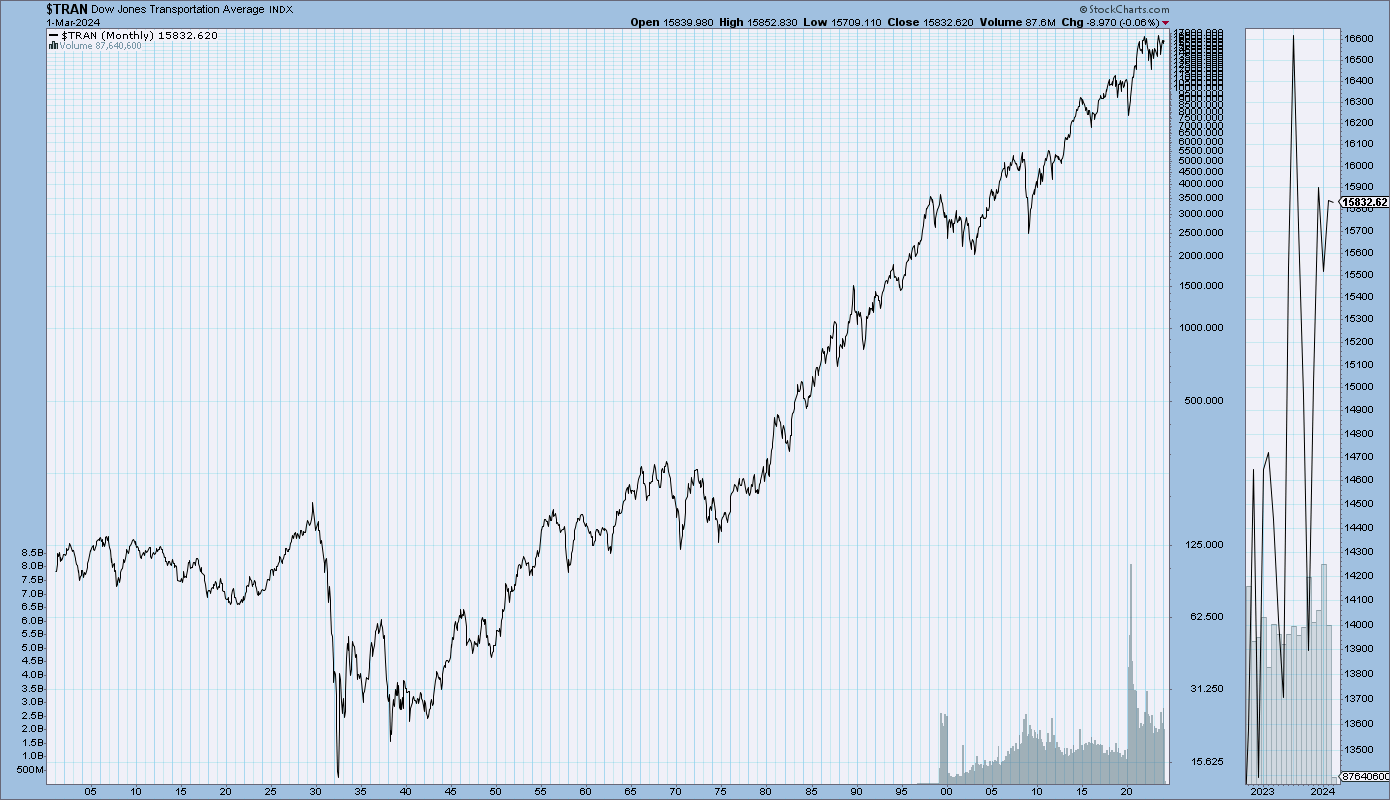
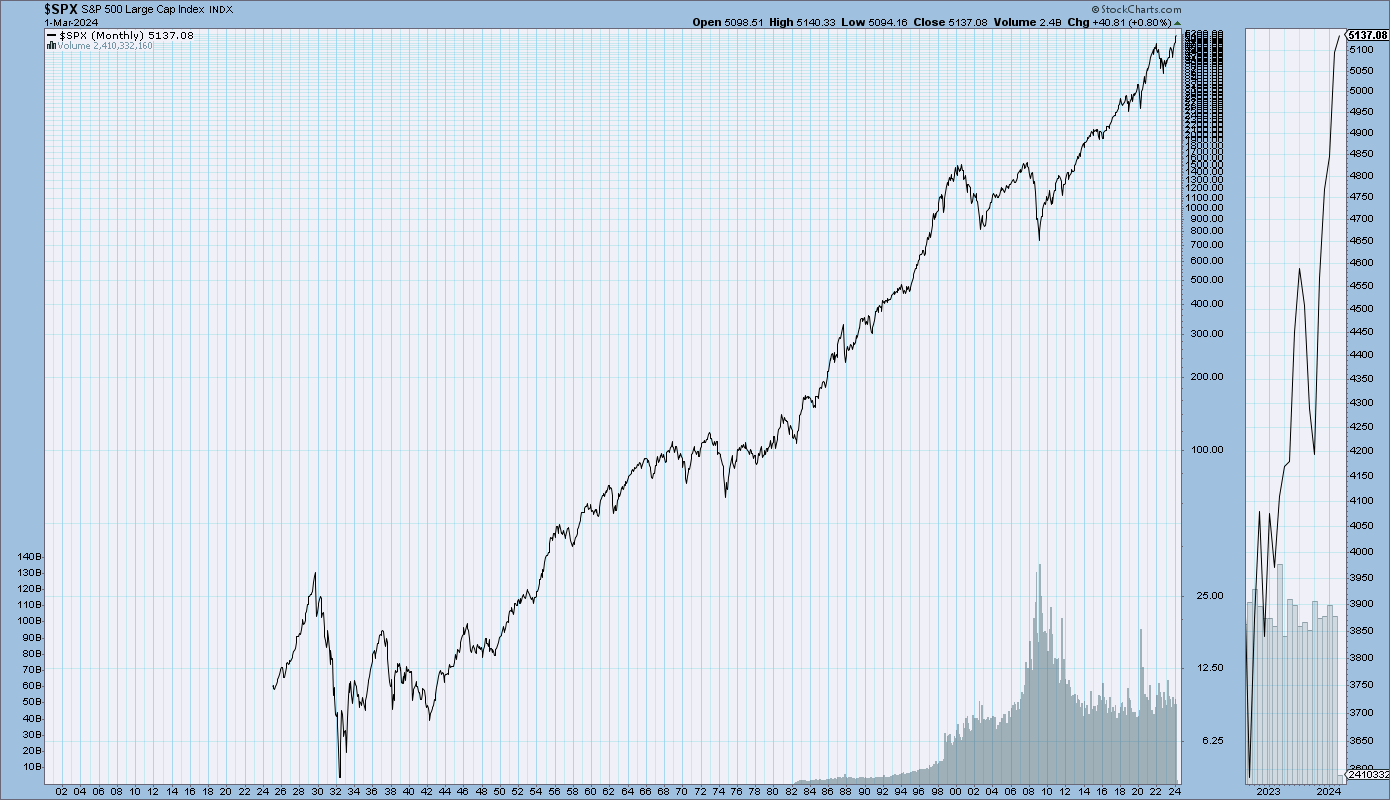
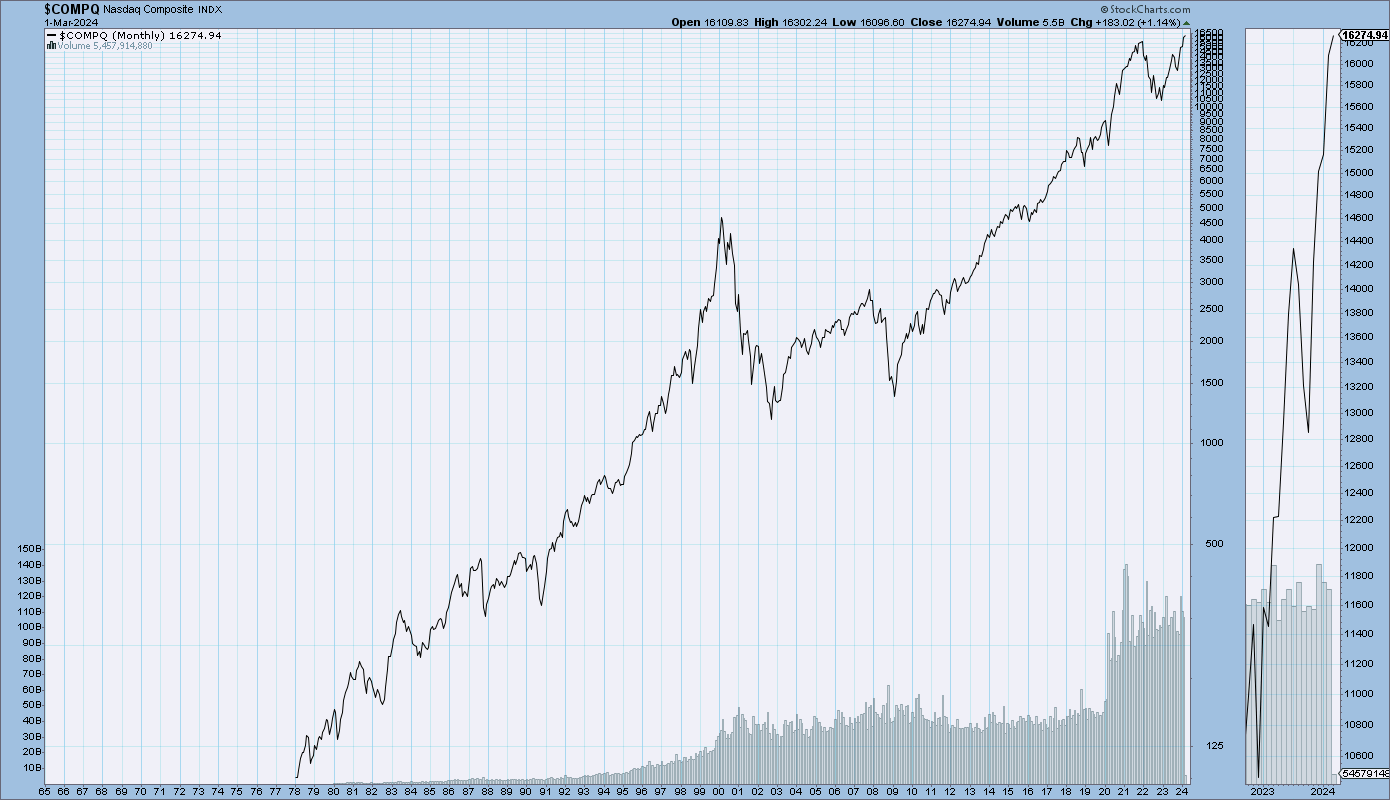
As a long-term reference, below are charts depicting various stock market indices for the dates shown.  All charts are depicted on a monthly basis using a LOG scale.

(click on charts to enlarge images)(charts courtesy of StockCharts.com)

The Dow Jones Industrial Average, from 1900 – March 1, 2024:

DJIA since 1900

–

The Dow Jones Transportation Average, from 1900 – March 1, 2024:

DJTA since 1900

–

The S&P500, from 1925 – March 1, 2024:

S&P500 since 1925

–

The Nasdaq Composite, from 1978 – March 1, 2024:

Nasdaq Composite since 1978

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 5137.08 as this post is written
Friday, March 1, 2024

Consumer Confidence Surveys – As Of March 1, 2024

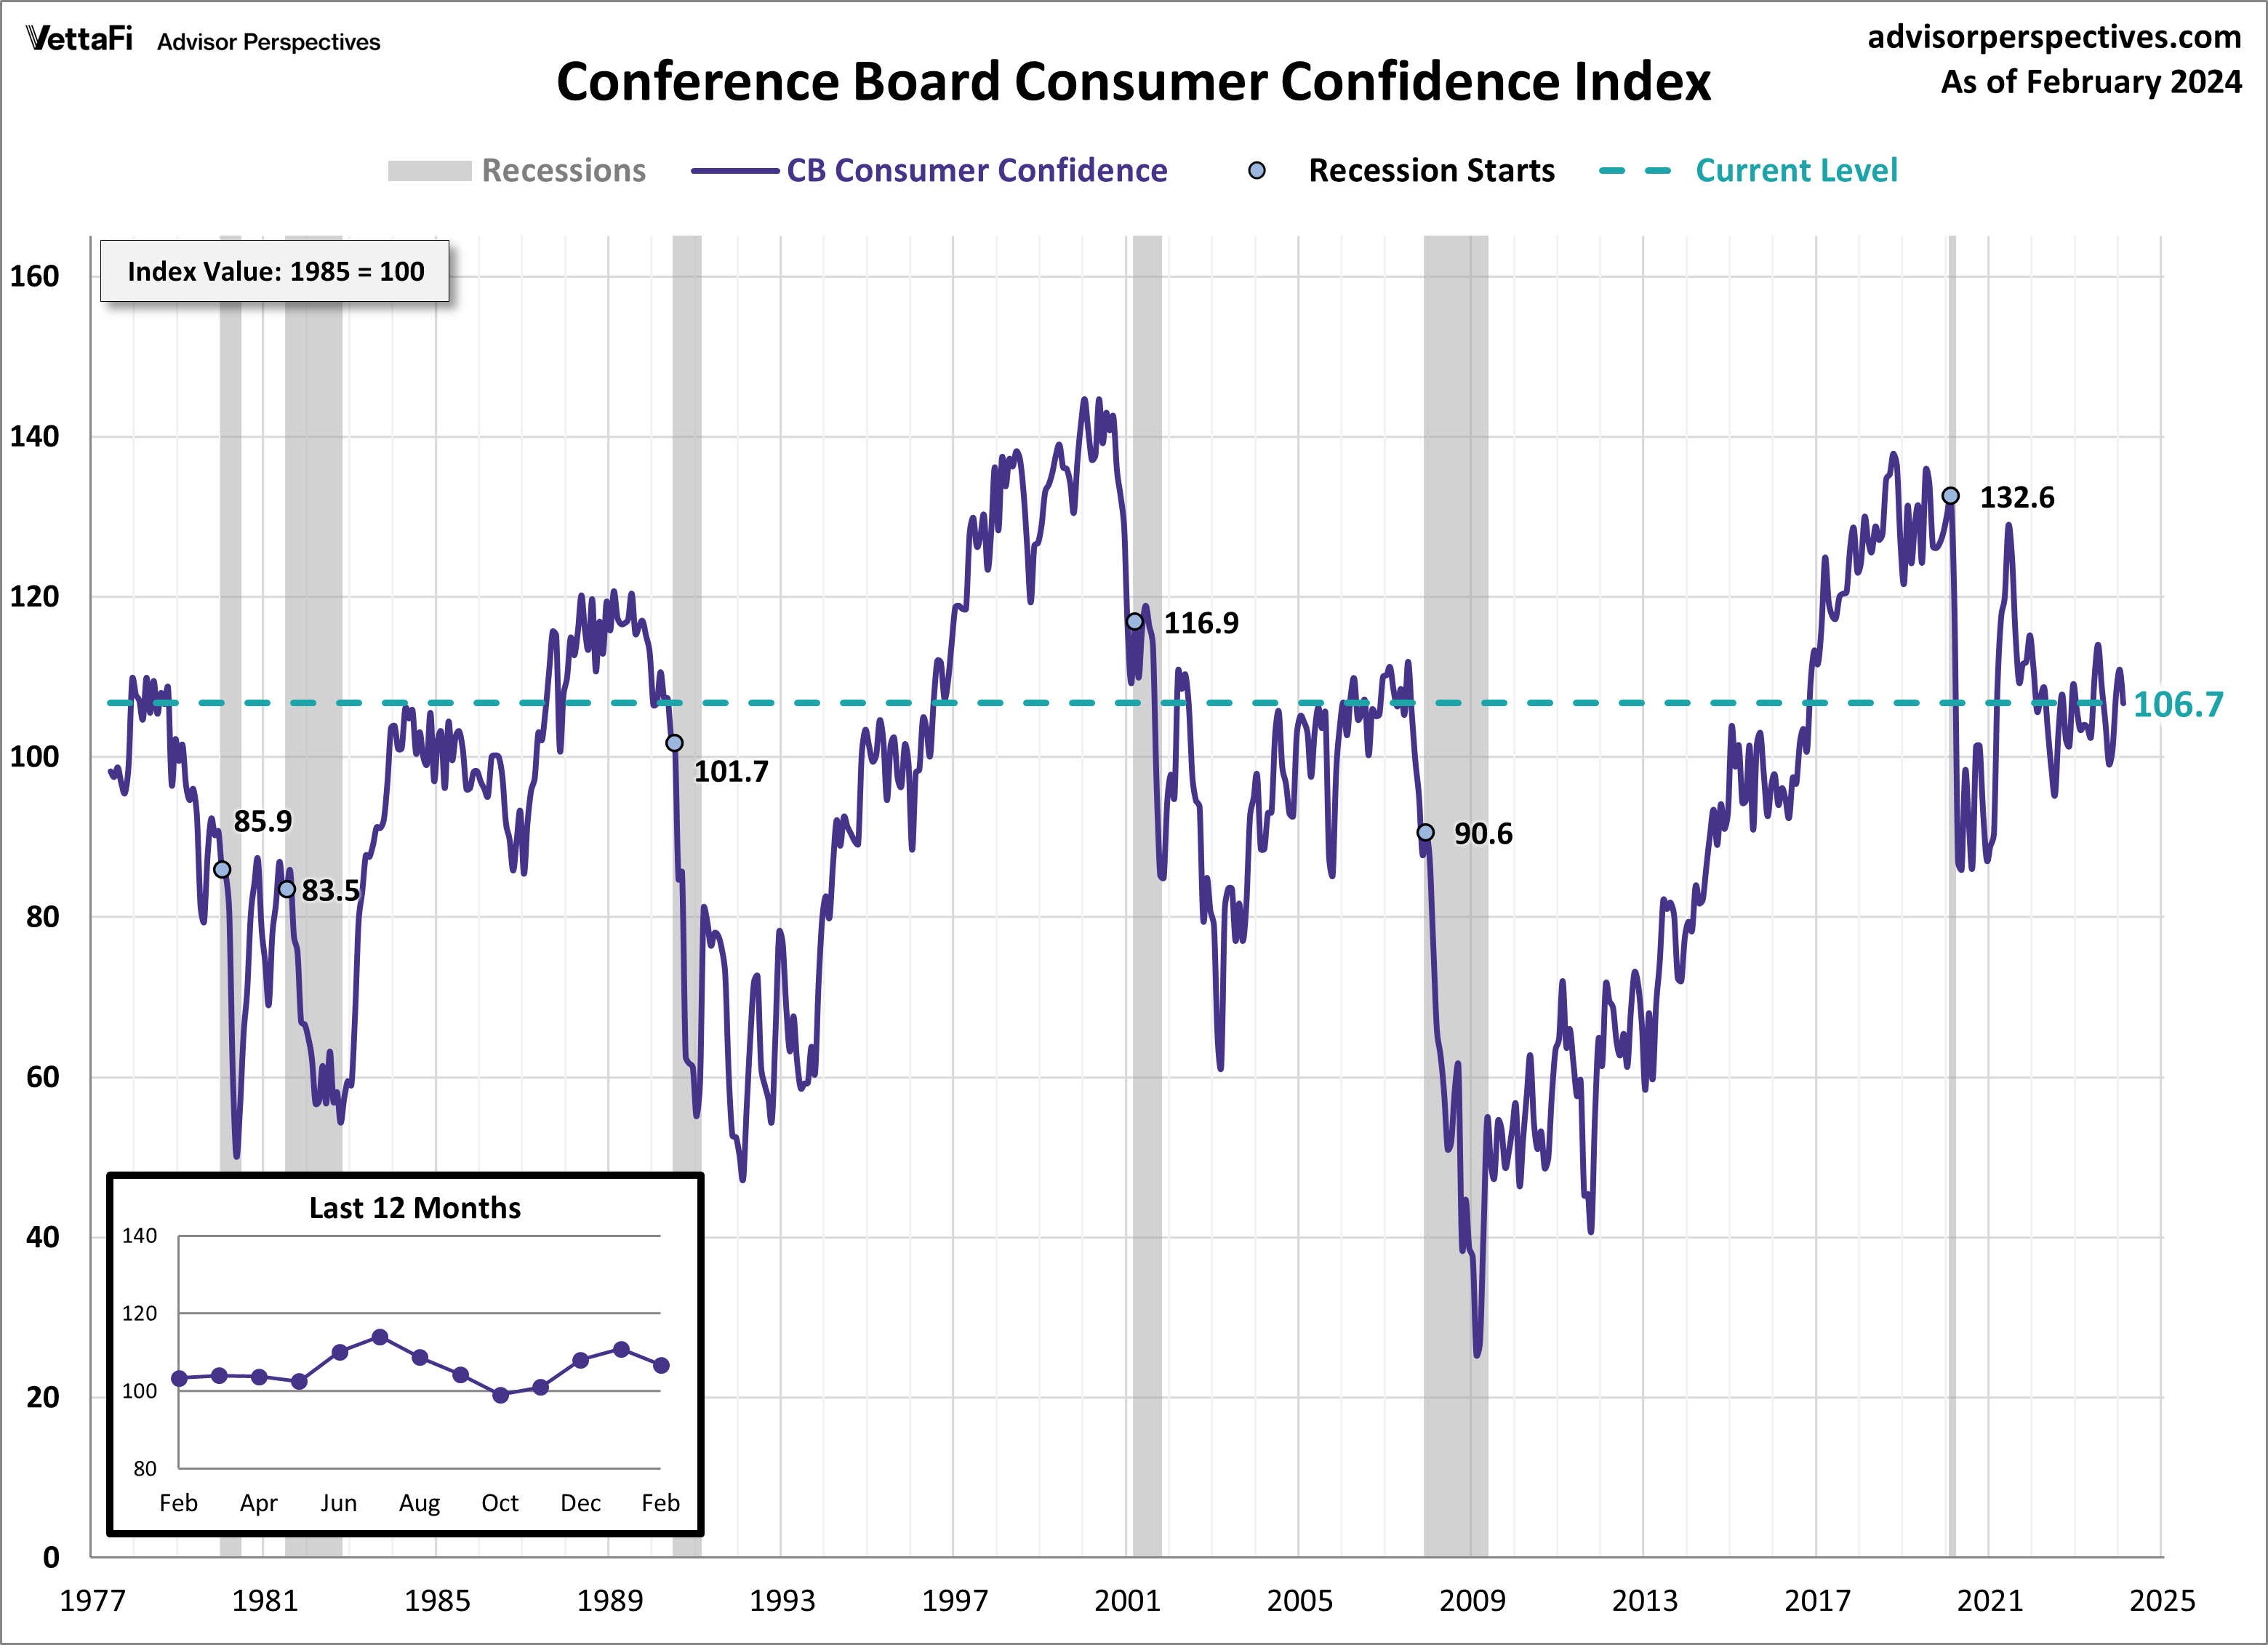
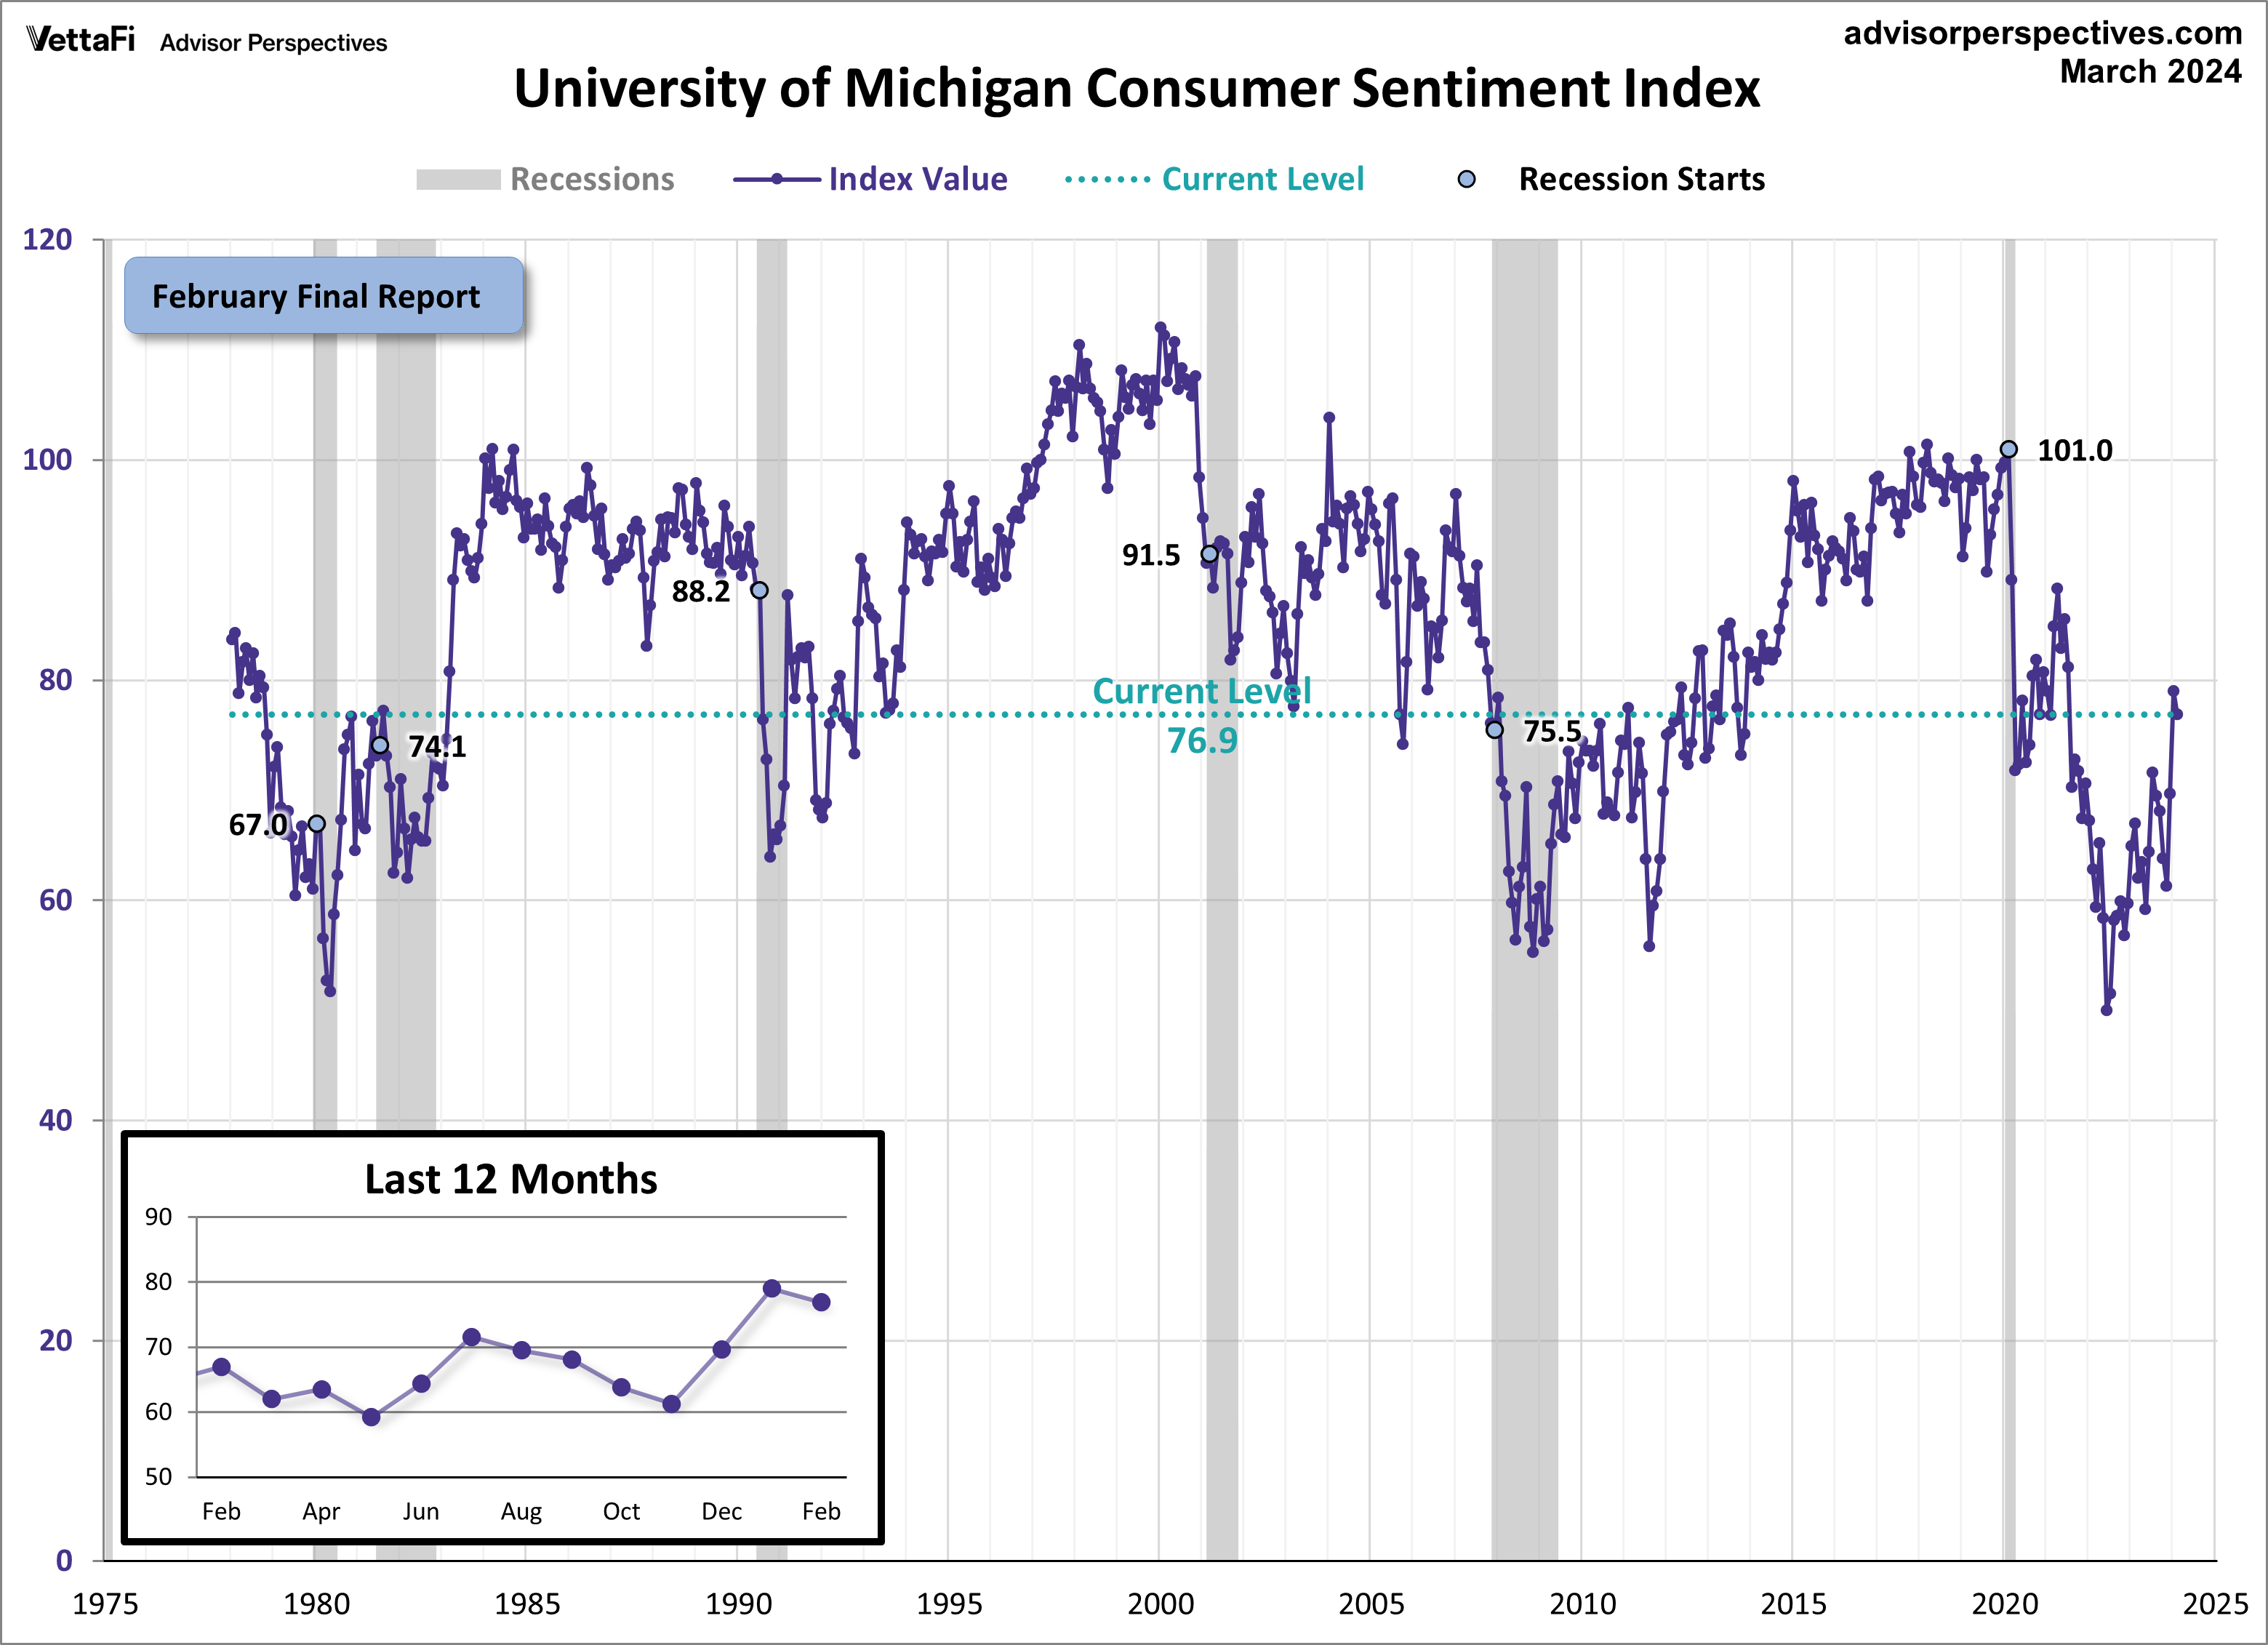
Advisor Perspectives had a post of March 1, 2024 (“Michigan Consumer Sentiment Moves Sideways in February“) that displays the latest Conference Board Consumer Confidence and University of Michigan Consumer Sentiment Index charts.  They are presented below:

(click on charts to enlarge images)

Conference Board Consumer Confidence 106.7

–

University of Michigan Consumer Sentiment Index 76.9

–

While I don’t believe that confidence surveys should be overemphasized, I find these readings and trends to be notable, especially in light of a variety of other highly disconcerting measures highlighted throughout this site.

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 5123.35 as this post is written
U.S. Dollar Decline – March 1, 2024 Update

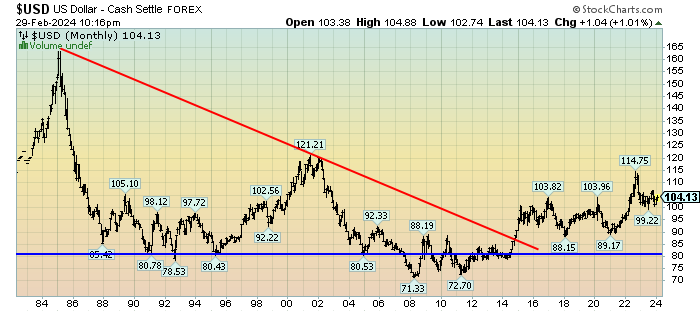
U.S. Dollar weakness is a foremost concern of mine.  As such, I have extensively written about it, including commentary on the “A Substantial U.S. Dollar Decline And Consequences” page.  I am very concerned that the actions being taken to “improve” our economic situation will dramatically weaken the Dollar.  Should the Dollar substantially decline from here, as I expect, the negative consequences will far outweigh any benefits.  The negative impact of a substantial Dollar decline can’t, in my opinion, be overstated.

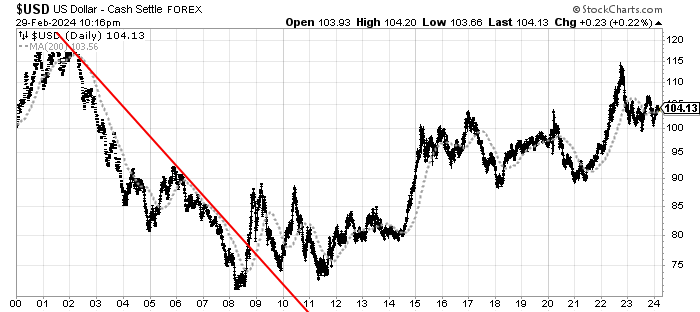
The following three charts illustrate various technical analysis aspects of the U.S. Dollar, as depicted by the U.S. Dollar Index.

First, a look at the monthly U.S. Dollar from 1983.  This clearly shows a long-term weakness, with the blue line showing technical support until 2007, and the red line representing a (past) trendline:

(charts courtesy of StockCharts.com; annotations by the author)

(click on charts to enlarge images)

U.S. Dollar Monthly 104.13

–

Next, another chart, this one focused on the daily U.S. Dollar since 2000 on a LOG scale.  The red line represents a (past) trendline.  The gray dotted line is the 200-day M.A. (moving average):

U.S. Dollar 200dma 104.13

–

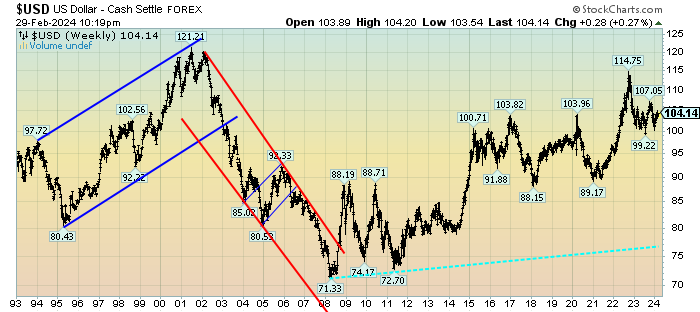
Lastly, a chart of the Dollar on a weekly LOG scale.  There are two clearly marked past channels, with possible technical support depicted by the dashed light blue line:

U.S. Dollar Weekly 104.14

–

I will continue providing updates on this U.S. Dollar situation regularly as it deserves very close monitoring…

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 5096.27 as this post is written
Problems Within The U.S. Economic Situation – March 1, 2024

Various surveys, economic growth projections, and market risk indicators indicate sustained economic growth and financial stability for the foreseeable future.

However, there are various indications – many of which have been discussed on this site – that this very widely-held consensus is in many ways incorrect.  There are many exceedingly problematical financial conditions that have existed prior to 2020, and continue to exist.  As well, numerous economic dynamics continue to be exceedingly worrisome and many economic indicators have portrayed facets of weak growth or outright decline currently as well as prior to 2020.

Of paramount importance is the resulting level of risk and the future economic implications.

From an “all things considered” standpoint, I continue to believe the overall level of risk remains at a fantastic level – one that is far greater than that experienced at any time in the history of the United States.

Cumulatively, these highly problematical conditions will lead to future upheaval.  The extent of the resolution of these problematical conditions will determine the ongoing viability of the financial system and economy as well as the resultant quality of living.

As I have previously written in “The U.S. Economic Situation” updates:

My analyses continues to indicate that the growing level of financial danger will lead to the next stock market crash that will also involve (as seen in 2008) various other markets as well.  Key attributes of this next crash is its outsized magnitude (when viewed from an ultra-long term historical perspective) and the resulting economic impact.  This next financial crash is of tremendous concern, as my analyses indicate it will lead to a Super Depression – i.e. an economy characterized by deeply embedded, highly complex, and difficult-to-solve problems.

_____

The Special Note summarizes my overall thoughts about our economic situation

SPX at 5096.27 as this post is written