As many are aware, Standard & Poor’s publishes earnings estimates for the S&P500. (My posts concerning their estimates can be found under the S&P500 Earnings label)
For reference purposes, the most current estimates are reflected below, and are as of February 7, 2024:
Year 2023 estimates add to the following:
-From a “bottom up” perspective, operating earnings of $211.61/share
-From a “bottom up” perspective, “as reported” earnings of $190.65/share
Year 2024 estimates add to the following:
-From a “bottom up” perspective, operating earnings of $240.40/share
-From a “bottom up” perspective, “as reported” earnings of $217.83/share
_____
I post various economic forecasts because I believe they should be carefully monitored. However, as those familiar with this site are aware, I do not agree with many of the consensus estimates and much of the commentary in these forecast surveys.
_____
The Special Note summarizes my overall thoughts about our economic situation
The survey shows, among many measures, the following median expectations:
Real GDP: (annual average level)
full-year 2024: 2.4%
full-year 2025: 1.8%
full-year 2026: 2.2%
full-year 2027: 1.7%
Unemployment Rate: (annual average level)
for 2024: 3.9%
for 2025: 4.1%
for 2026: 4.1%
for 2027: 4.0%
–
Regarding the risk of a negative quarter in real GDP in any of the next few quarters, mean estimates are 17.3%, 23.9%, 25.6%, 25.6%, and 25.2% for each of the quarters from Q1 2024 through Q1 2025, respectively.
As well, there are also a variety of time frames shown (present quarter through the year 2033) with the median expected inflation (annualized) of each. Inflation is measured in Headline and Core CPI and Headline and Core PCE. Over all time frames expectations are shown to be in the 1.9% to 3.1% range.
_____
I post various economic forecasts because I believe they should be carefully monitored. However, as those familiar with this site are aware, I do not agree with many of the consensus estimates and much of the commentary in these forecast surveys.
_____
The Special Note summarizes my overall thoughts about our economic situation
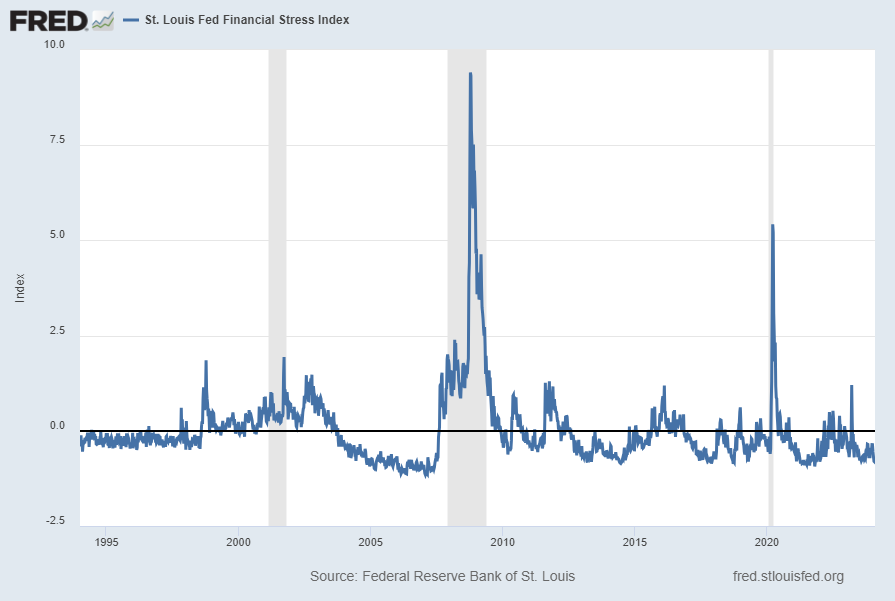
The St. Louis Fed’s Financial Stress Index (STLFSI4) is one index that is supposed to measure stress in the financial system. Its reading as of the February 8, 2024 update (reflecting data through February 2, 2024) is -.7332:
source: Federal Reserve Bank of St. Louis, St. Louis Fed Financial Stress Index [STLFSI4], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed February 8, 2024: https://fred.stlouisfed.org/series/STLFSI4
Of course, there are a variety of other measures and indices that are supposed to measure financial stress and other related issues, both from the Federal Reserve as well as from private sources.
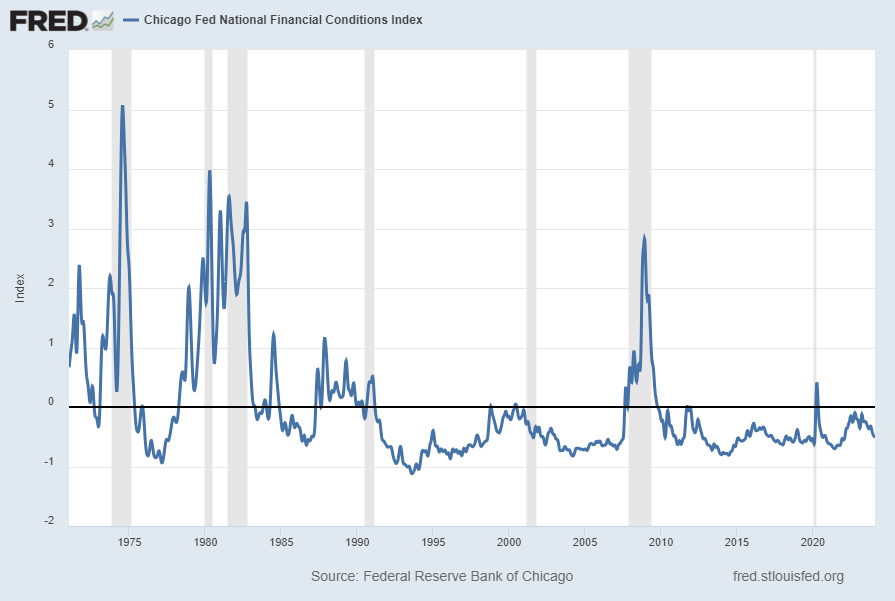
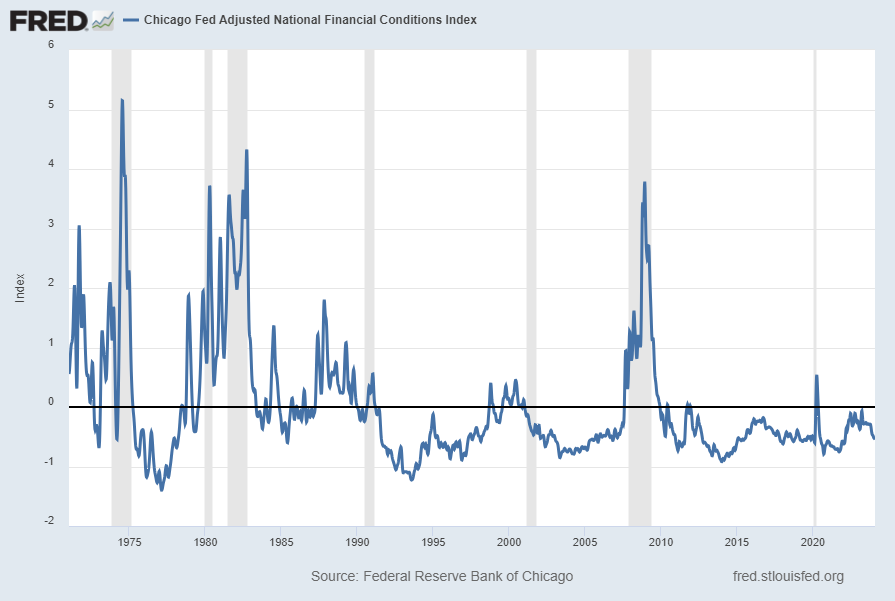
Two other indices that I regularly monitor include the Chicago Fed National Financial Conditions Index (NFCI) as well as the Chicago Fed Adjusted National Financial Conditions Index (ANFCI).
Here are summary descriptions of each, as seen in FRED:
The National Financial Conditions Index (NFCI) measures risk, liquidity and leverage in money markets and debt and equity markets as well as in the traditional and “shadow” banking systems. Positive values of the NFCI indicate financial conditions that are tighter than average, while negative values indicate financial conditions that are looser than average.
The adjusted NFCI (ANFCI). This index isolates a component of financial conditions uncorrelated with economic conditions to provide an update on how financial conditions compare with current economic conditions.
For further information, please visit the Federal Reserve Bank of Chicago’s web site:
Below are the most recently updated charts of the NFCI and ANFCI, respectively.
The NFCI chart below was last updated on February 7, 2024 incorporating data from January 8, 1971 through February 2, 2024 on a weekly basis. The February 2 value is -.49078:
The ANFCI chart below was last updated on February 7, 2024 incorporating data from January 8, 1971 through February 2, 2024, on a weekly basis. The February 2, 2024 value is -.49532:
I post various indicators and indices because I believe they should be carefully monitored. However, as those familiar with this site are aware, I do not necessarily agree with what they depict or imply.
_____
The Special Note summarizes my overall thoughts about our economic situation
My overall analysis indicates a continuing elevated and growing level of financial danger which contains many worldwide and U.S.-specific “stresses” of a very complex nature. I have written numerous posts on this site concerning both ongoing and recent “negative developments.” These developments, as well as other exceedingly problematical conditions, have presented a highly perilous economic environment that endangers the overall financial system.
Also of ongoing immense importance is the existence of various immensely large asset bubbles, a subject of which I have extensively written. While all of these asset bubbles are wildly pernicious and will have profound adverse future implications, hazards presented by the bond market bubble are especially notable.
Predicting the specific timing and extent of a stock market crash is always difficult, and the immense complexity of today’s economic situation makes such a prediction even more challenging. With that being said, my analyses continue to indicate that a near-term exceedingly large (from an ultra long-term perspective) stock market crash – that would also involve (as seen in 2008) various other markets – will occur. [note: the “next crash” and its aftermath has paramount significance and implications, as discussed in the post of January 6, 2012 titled “The Next Crash And Its Significance“ and various subsequent posts in the “Economic Depression” label]
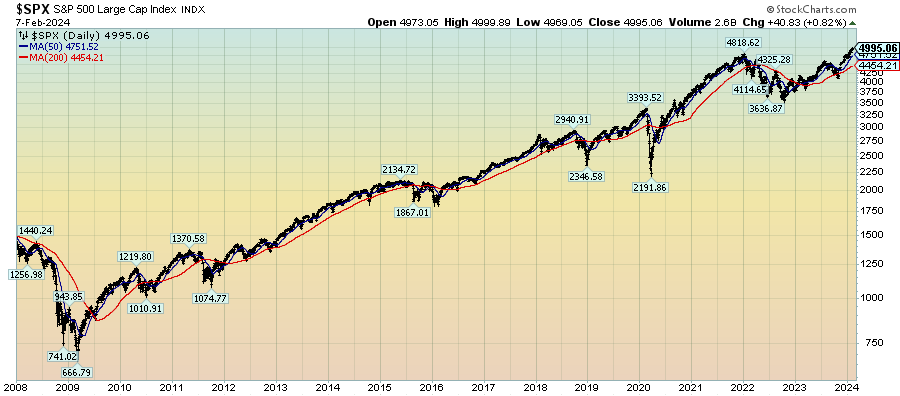
As reference, below is a daily chart since 2008 of the S&P500 (through February 7, 2024 with a last price of 4995.06), depicted on a LOG scale, indicating both the 50dma and 200dma as well as price labels:
(click on chart to enlarge image)(chart courtesy of StockCharts.com; chart creation and annotation by the author)
_____
The Special Note summarizes my overall thoughts about our economic situation
Throughout this site there are many discussions of economic indicators. This post is the latest in a series of posts indicating facets of U.S. economic weakness or a notably low growth rate.
The level and trend of economic growth is especially notable at this time. As seen in various sources, recession estimates have been at high levels.
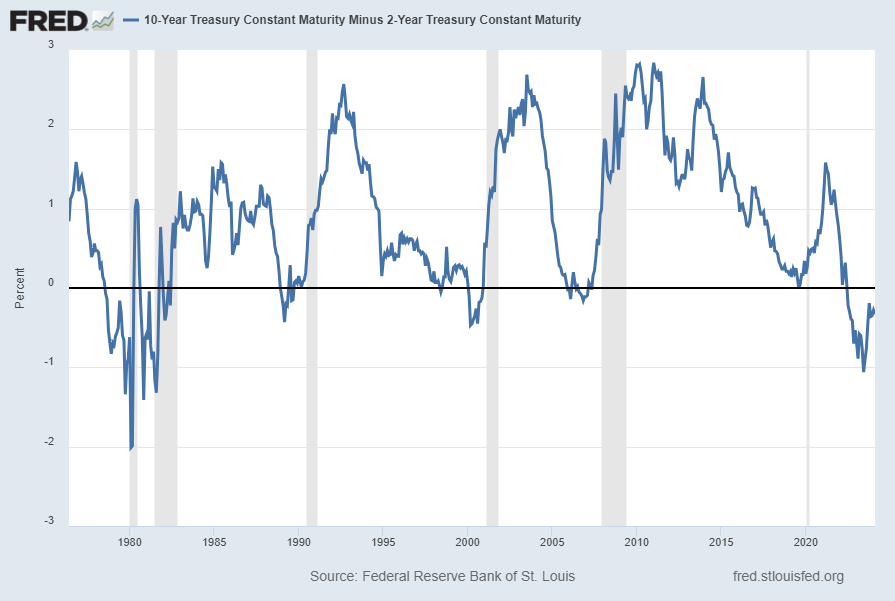
While I continue to have the stated reservations regarding the “Yield Curve” as an indicator, I do believe that it should be monitored.
The U.S. Yield Curve (one proxy seen below) is (all things considered) notably inverted when viewed from a long-term perspective. Below is the spread between the 10-Year Treasury Constant Maturity and the 2-Year Treasury Constant Maturity from June 1976 through the February 2, 2024 update, showing a value of -.33% [10-Year Treasury Yield (FRED DGS10) of 3.87% as of the February 2 update, 2-Year Treasury Yield (FRED DGS2) of 4.20% as of the February 2 update]:
source: Federal Reserve Bank of St. Louis, 10-Year Treasury Constant Maturity Minus 2-Year Treasury Constant Maturity [T10Y2Y], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed February 5, 2024: https://fred.stlouisfed.org/series/T10Y2Y
__
Job Openings (JTSJOL)
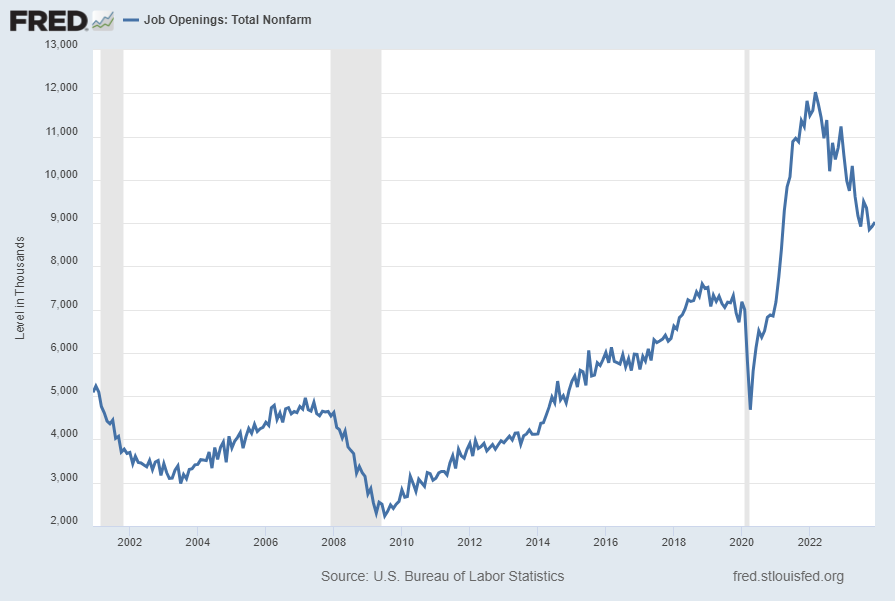
Job openings (Job Openings: Total Nonfarm [JTSJOL]), although still at a (very) high level, have recently declined significantly. This “Job Openings” measure had a value of 9,026 (Thousands) through December 2023 as of the January 30, 2024 update, as shown below:
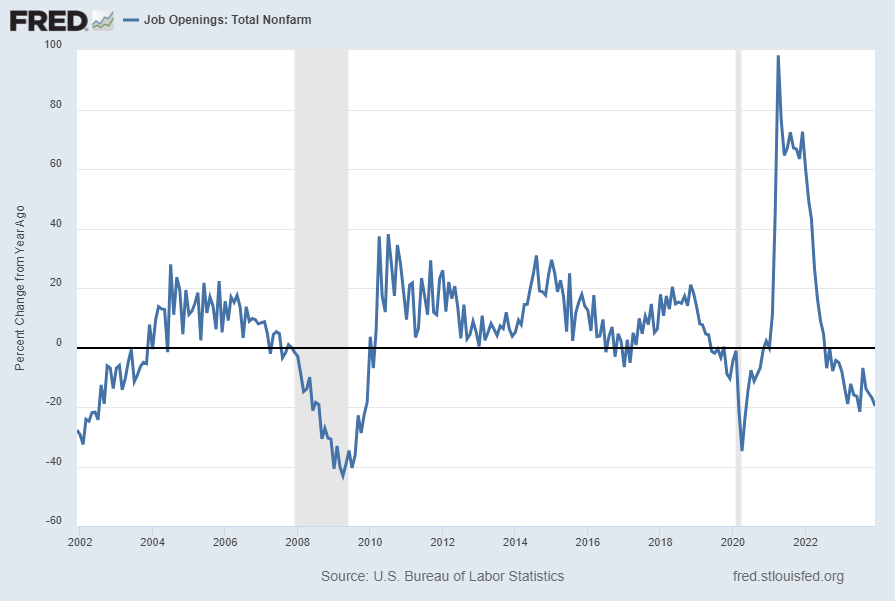
Below is this measure displayed on a “Percent Change From Year Ago” basis with value -19.7%:
source: U.S. Bureau of Labor Statistics, Job Openings: Total Nonfarm [JTSJOL], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed February 4, 2024: https://fred.stlouisfed.org/series/JTSJOL
__
Average Weekly Hours of All Employees, Total Private (AWHAETP)
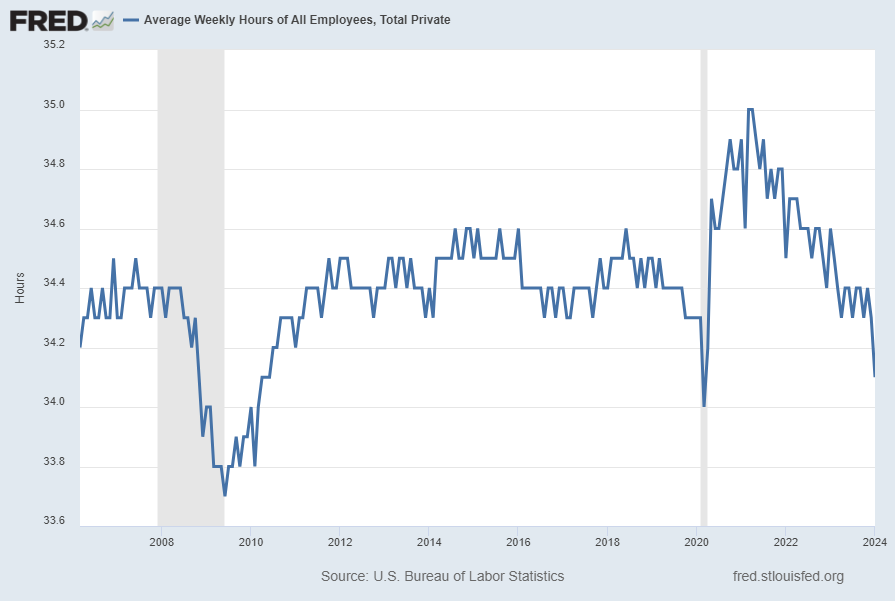
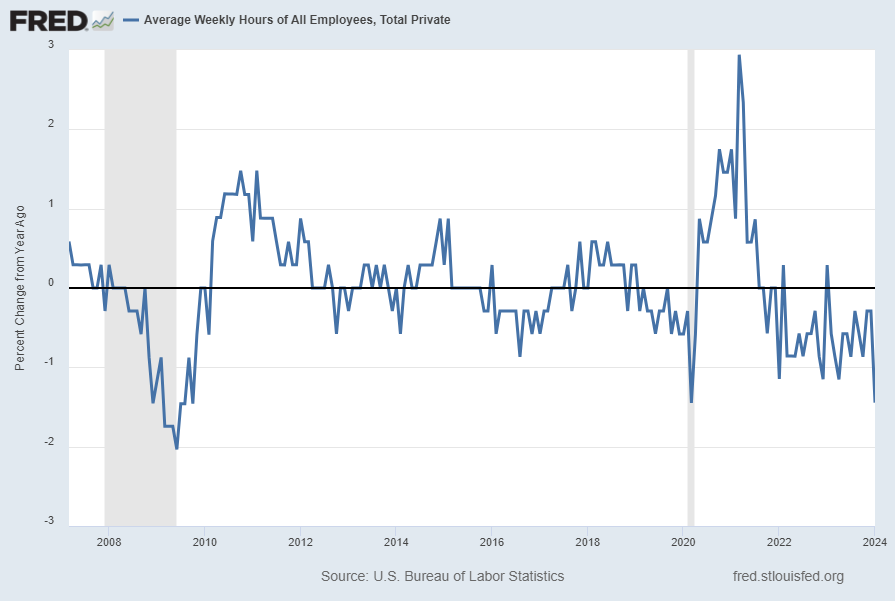
Average Weekly Hours of All Employees continues a significant downward progression. This “Average Weekly Hours” measure had a value of 34.1 (Hours) through January 2024 as of the February 2, 2024 update:
Below is this measure displayed on a “Percent Change From Year Ago” basis with value -1.4%:
source: U.S. Bureau of Labor Statistics, Average Weekly Hours of All Employees, Total Private [AWHAETP], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed February 4, 2024: https://fred.stlouisfed.org/series/AWHAETP
__
Total Federal Receipts (MTSR133FMS)
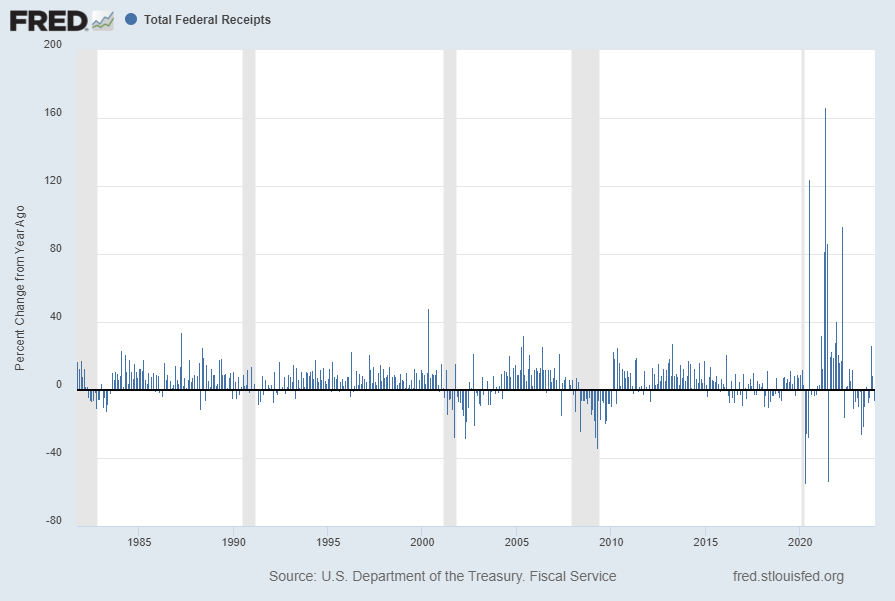
“Total Federal Receipts,” as measured on a “Percent Change From Year Ago” basis, has (since 2020) been volatile for various reasons. The current value, last updated January 11, 2024, is -5.6%:
source: U.S. Department of the Treasury. Fiscal Service, Total Federal Receipts [MTSR133FMS], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed February 4, 2024: https://fred.stlouisfed.org/series/MTSR133FMS
__
Other Indicators
As mentioned previously, many other indicators discussed on this site indicate weak economic growth or economic contraction, if not outright (gravely) problematical economic conditions.
_____
The Special Note summarizes my overall thoughts about our economic situation
There are a variety of economic models that are supposed to predict the probabilities of recession.
While I don’t agree with the methodologies employed or probabilities of impending economic weakness as depicted by the following two models, I think the results of these models should be monitored.
Please note that each of these models is updated regularly, and the results of these – as well as other recession models – can fluctuate significantly.
Currently (last updated February 4, 2024 using data through January 2024) this “Yield Curve” model shows a 61.473% probability of a recession in the United States twelve months ahead. For comparison purposes, it showed a 62.9365% probability through December 2023, and a chart going back to 1960 is seen at the “Probability Of U.S. Recession Predicted by Treasury Spread.” (pdf)
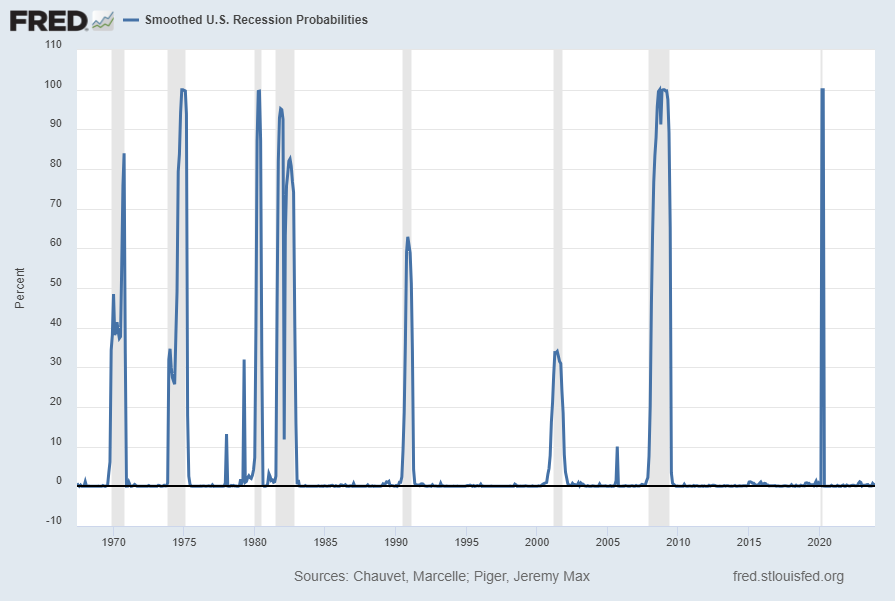
Smoothed recession probabilities for the United States are obtained from a dynamic-factor markov-switching model applied to four monthly coincident variables: non-farm payroll employment, the index of industrial production, real personal income excluding transfer payments, and real manufacturing and trade sales. This model was originally developed in Chauvet, M., “An Economic Characterization of Business Cycle Dynamics with Factor Structure and Regime Switching,” International Economic Review, 1998, 39, 969-996. (http://faculty.ucr.edu/~chauvet/ier.pdf)
This model, last updated on February 1, 2024 currently shows a .74% probability using data through December 2023.
Here is the FRED chart:
Data Source: Piger, Jeremy Max and Chauvet, Marcelle, Smoothed U.S. Recession Probabilities [RECPROUSM156N], retrieved from FRED, Federal Reserve Bank of St. Louis, accessed February 5, 2024: http://research.stlouisfed.org/fred2/series/RECPROUSM156N
–
The two models featured above can be compared against measures seen in recent posts. For instance, as seen in the January 14, 2024 post titled “The January 2024 Wall Street Journal Economic Forecast Survey“ economists surveyed averaged a 39% probability of a U.S. recession within the next 12 months.
_____
The Special Note summarizes my overall thoughts about our economic situation
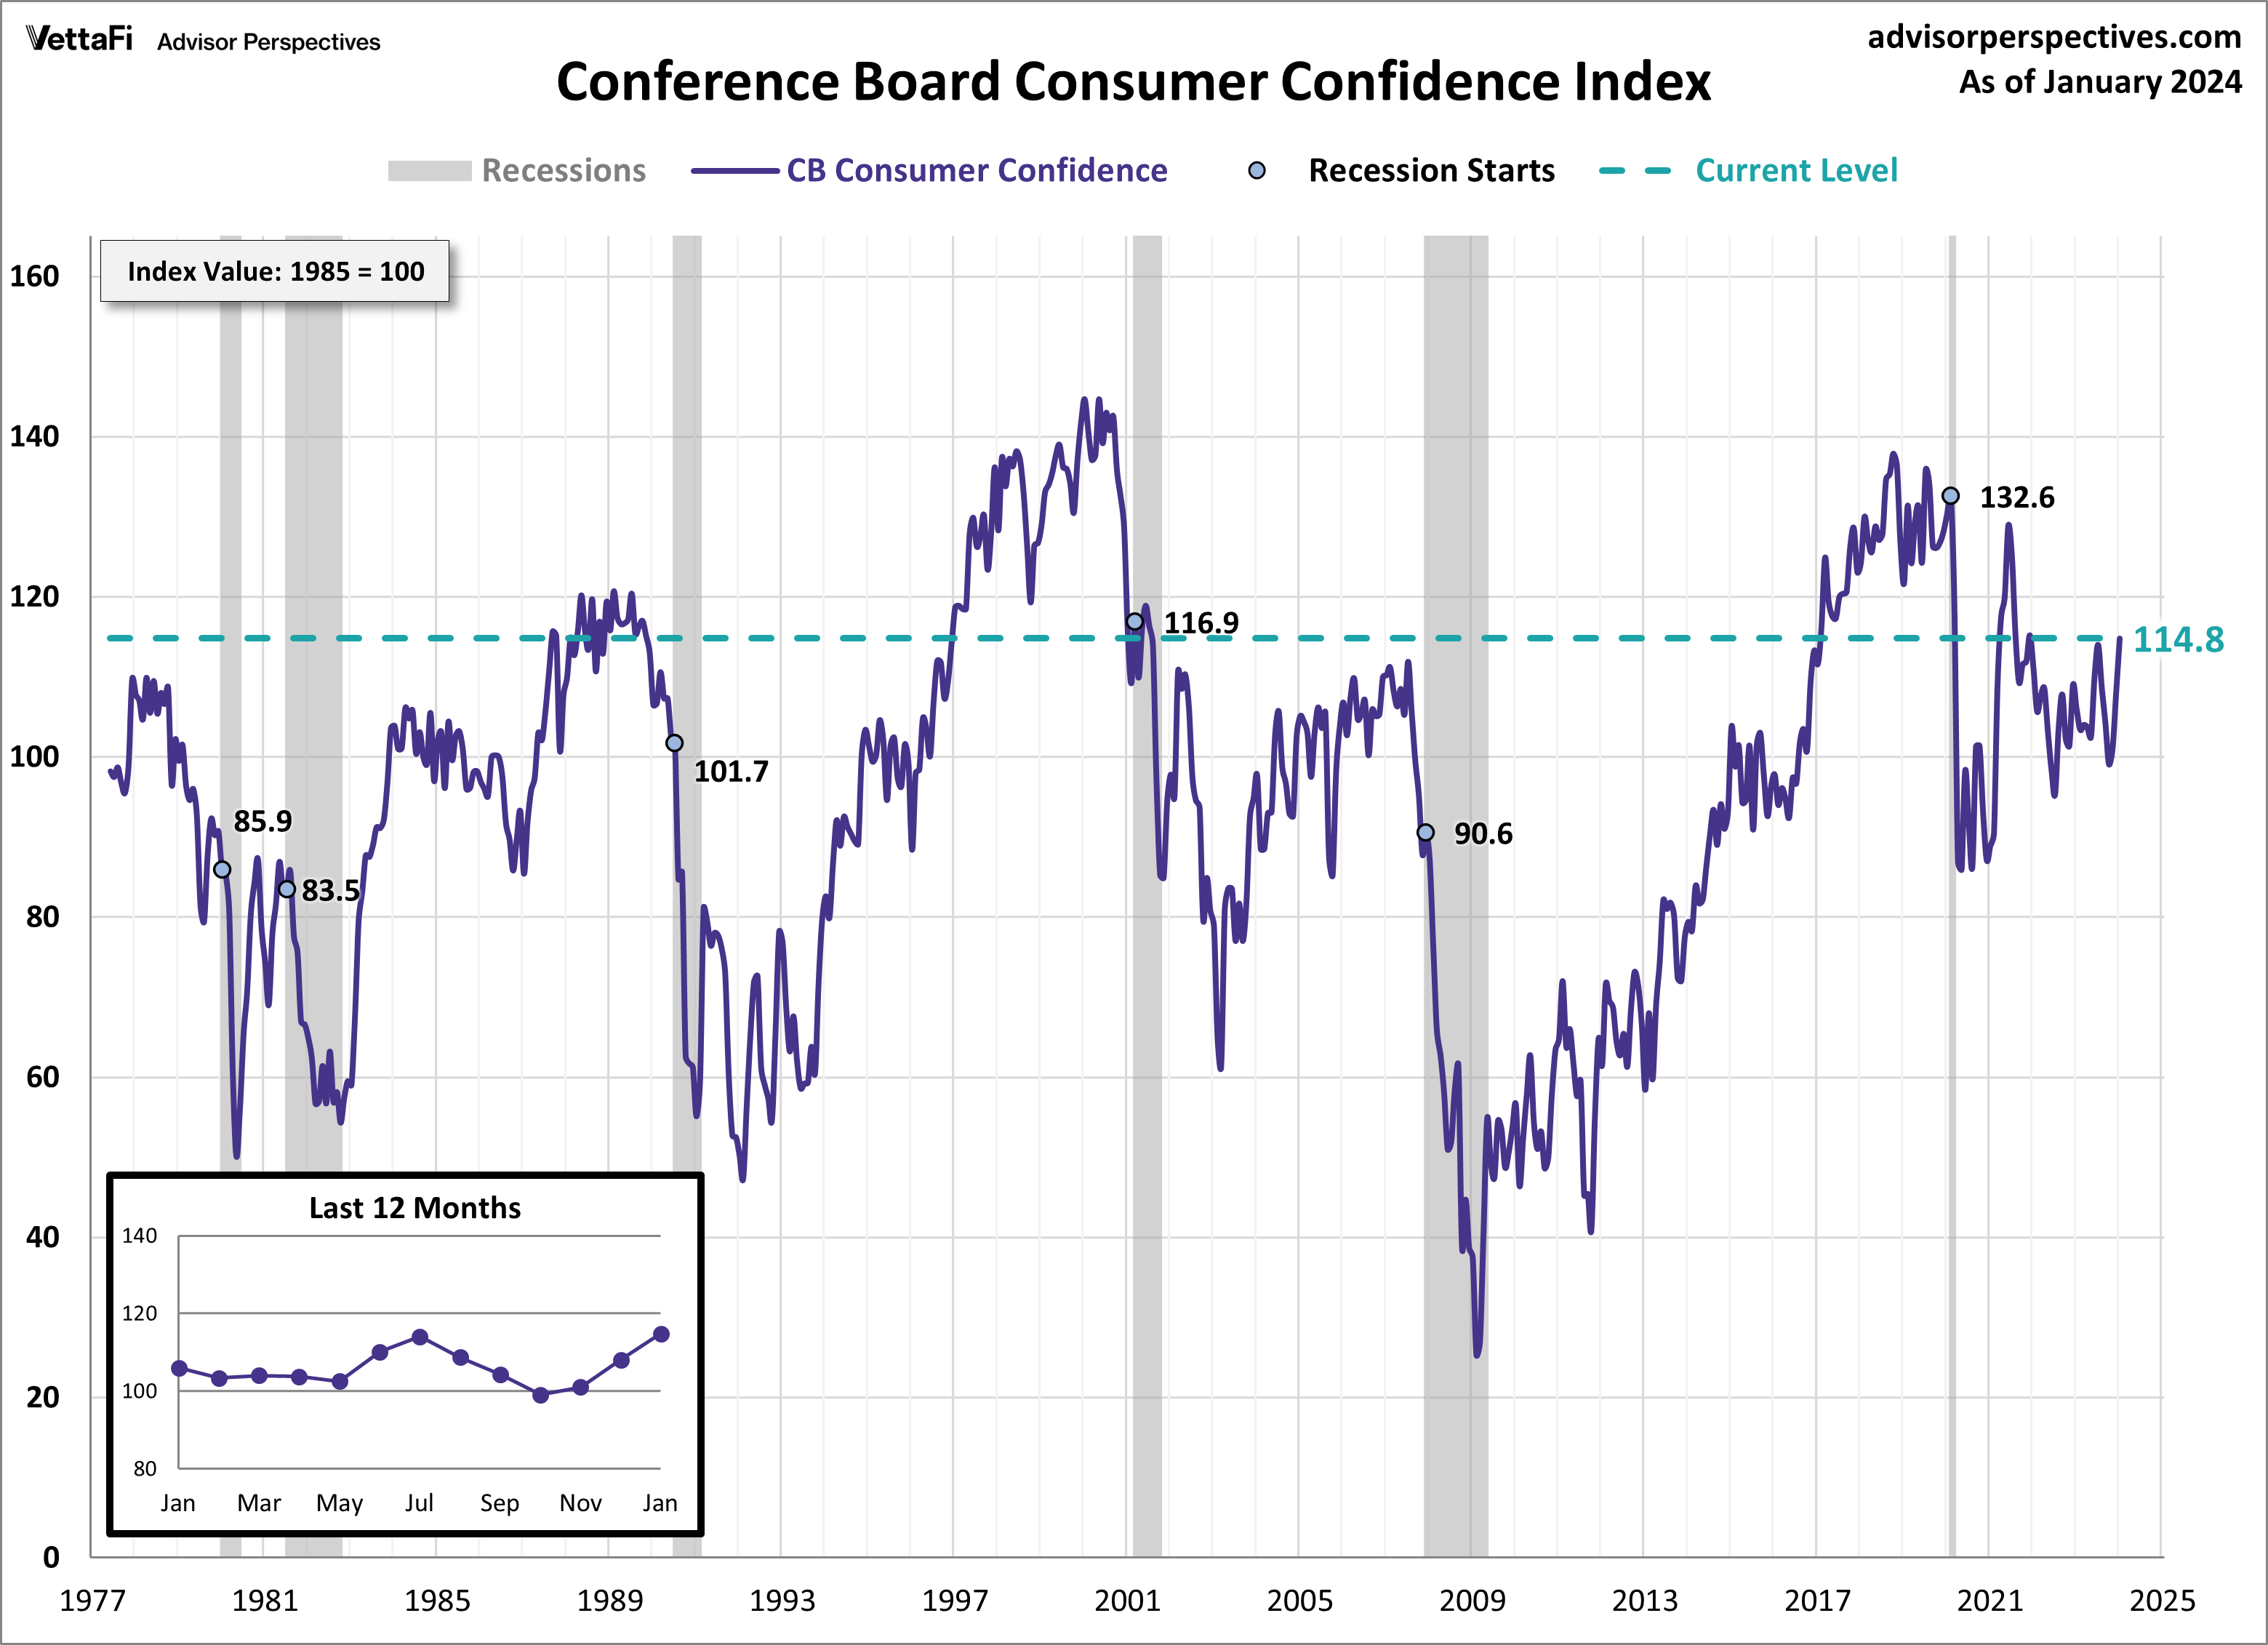
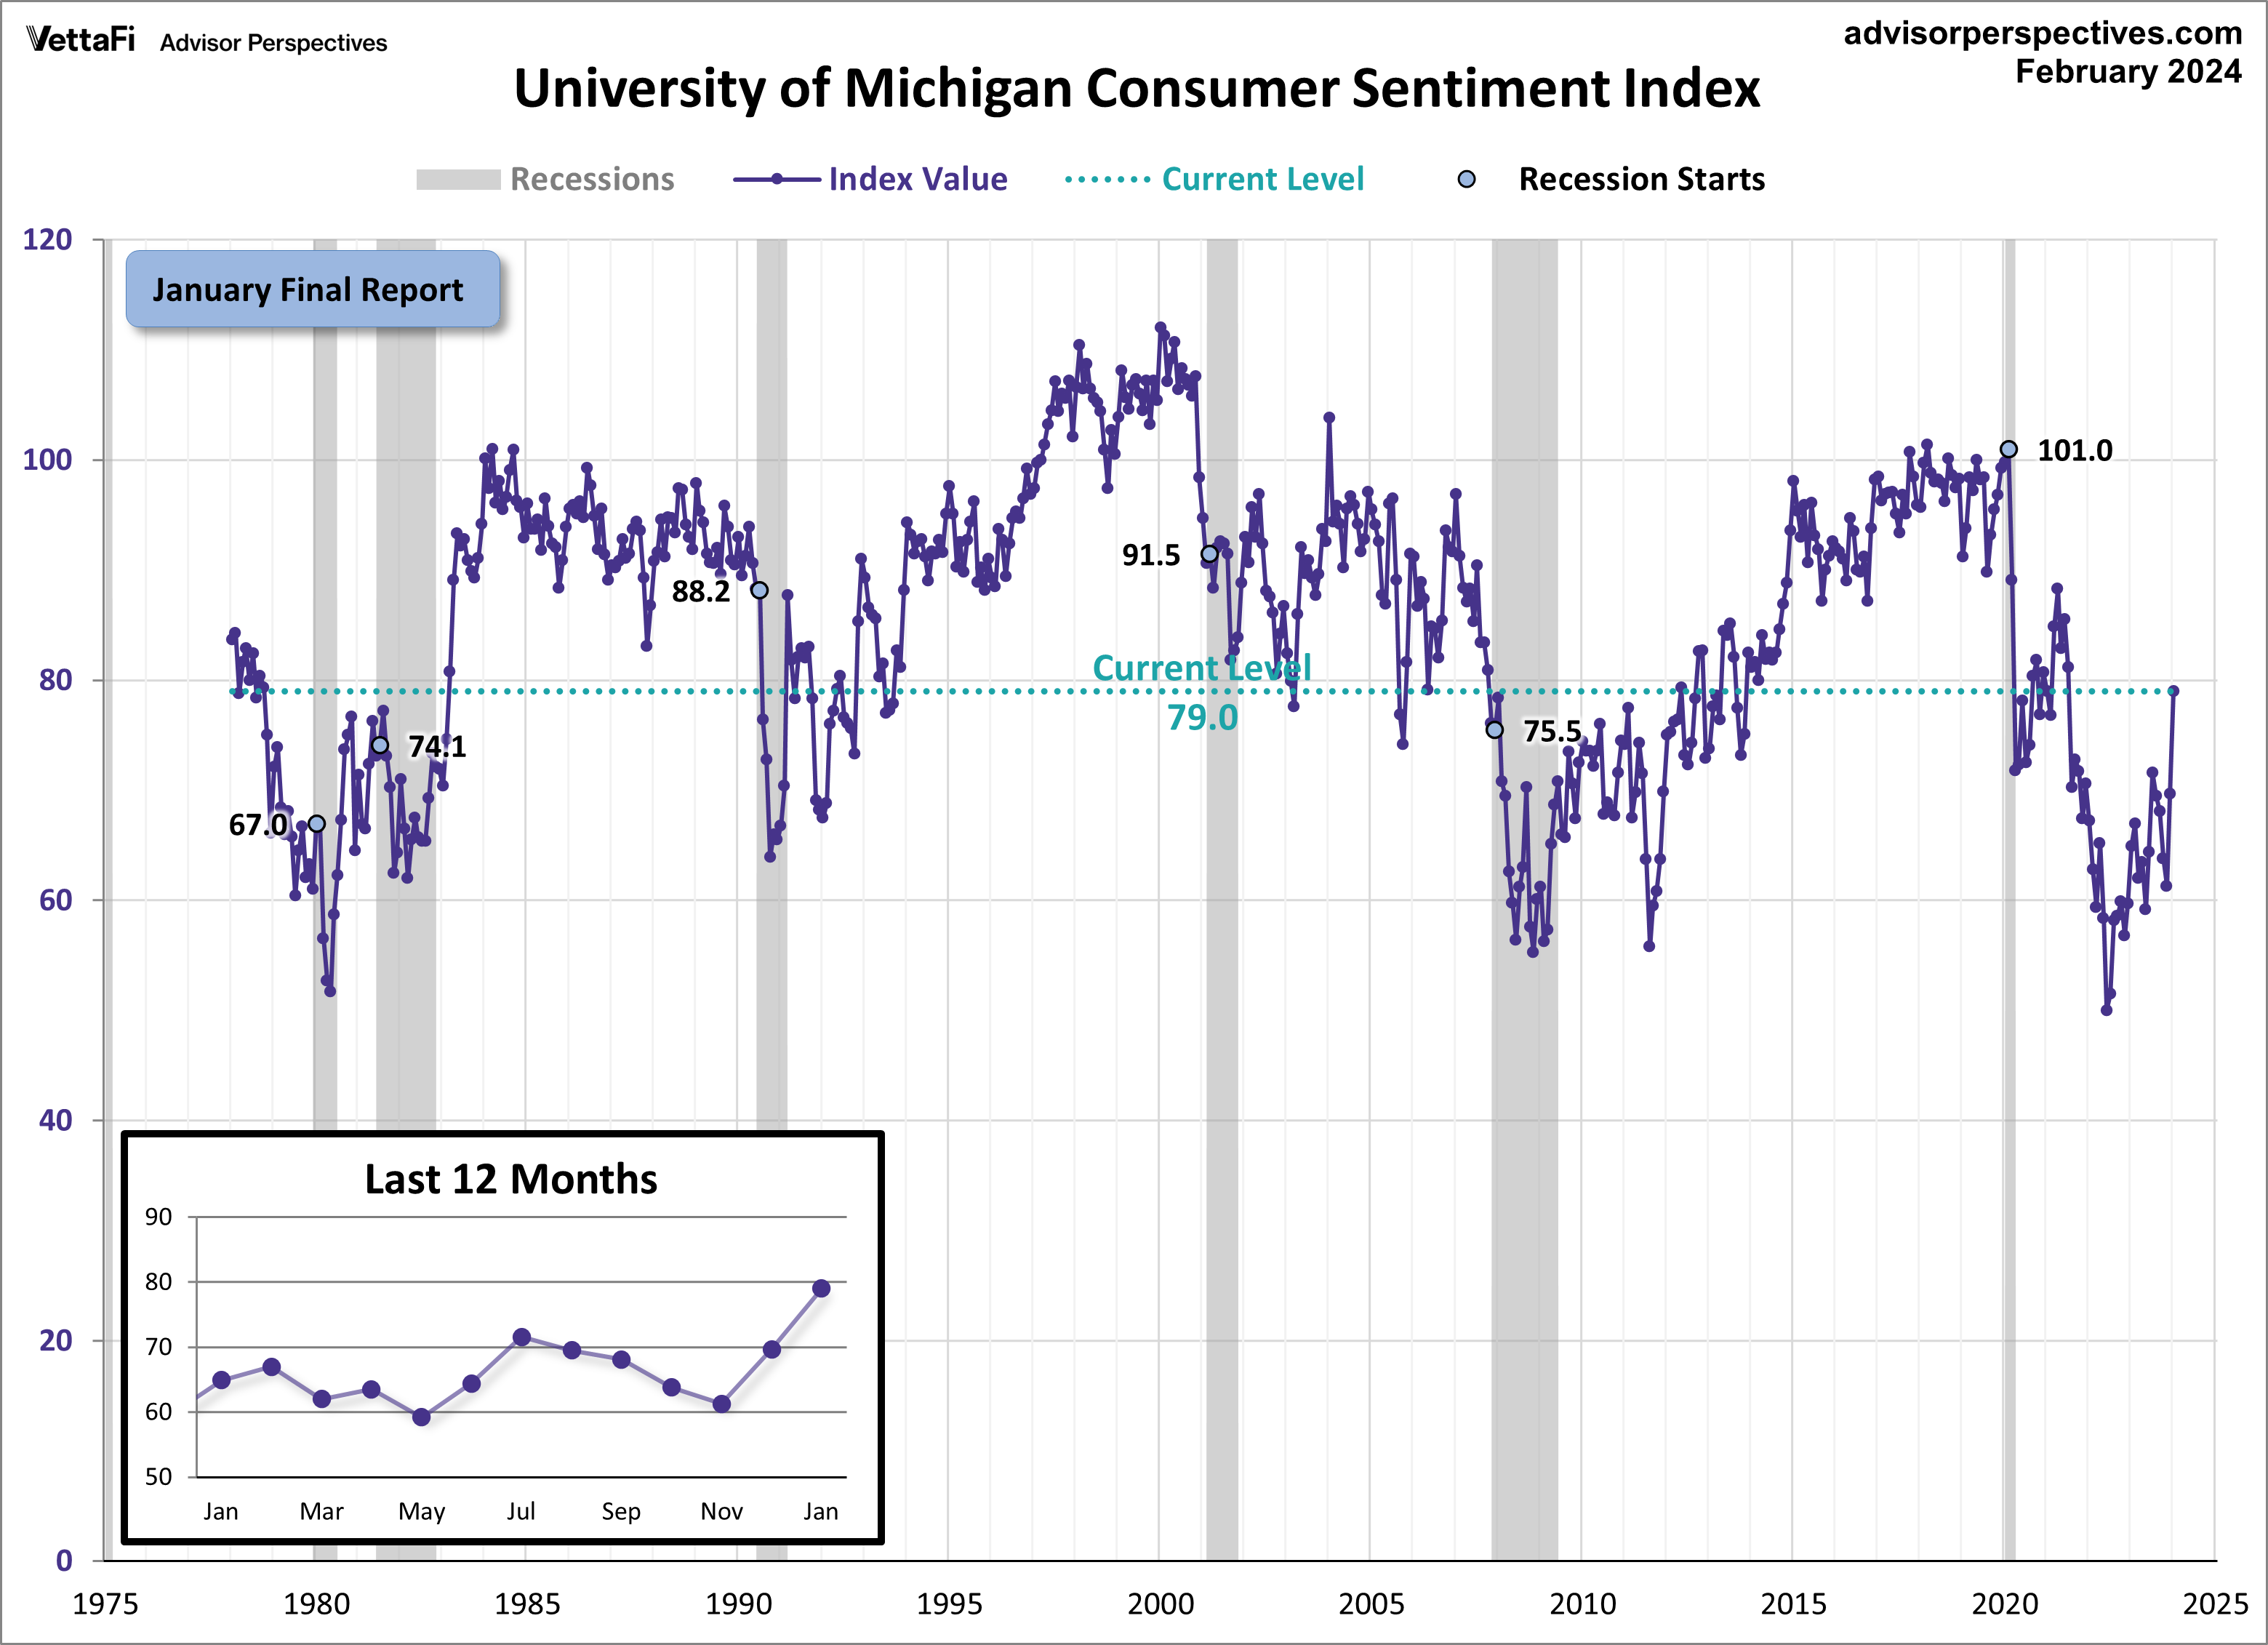
Advisor Perspectives had a post of February 2, 2024 (“Michigan Consumer Sentiment Soars In January“) that displays the latest Conference Board Consumer Confidence and University of Michigan Consumer Sentiment Index charts. They are presented below:
(click on charts to enlarge images)
–
–
While I don’t believe that confidence surveys should be overemphasized, I find these readings and trends to be notable, especially in light of a variety of other highly disconcerting measures highlighted throughout this site.
_____
The Special Note summarizes my overall thoughts about our economic situation
For reference purposes, below are five charts that display growth in payroll employment, as depicted by the Total Nonfarm Payroll measures (FRED data series PAYEMS).
PAYEMS, which is seasonally adjusted, is defined in Financial Reserve Economic Data [FRED] as:
All Employees: Total Nonfarm, commonly known as Total Nonfarm Payroll, is a measure of the number of U.S. workers in the economy that excludes proprietors, private household employees, unpaid volunteers, farm employees, and the unincorporated self-employed. This measure accounts for approximately 80 percent of the workers who contribute to Gross Domestic Product (GDP).
This measure provides useful insights into the current economic situation because it can represent the number of jobs added or lost in an economy. Increases in employment might indicate that businesses are hiring which might also suggest that businesses are growing. Additionally, those who are newly employed have increased their personal incomes, which means (all else constant) their disposable incomes have also increased, thus fostering further economic expansion.
Generally, the U.S. labor force and levels of employment and unemployment are subject to fluctuations due to seasonal changes in weather, major holidays, and the opening and closing of schools. The Bureau of Labor Statistics (BLS) adjusts the data to offset the seasonal effects to show non-seasonal changes: for example, women’s participation in the labor force; or a general decline in the number of employees, a possible indication of a downturn in the economy. To closely examine seasonal and non-seasonal changes, the BLS releases two monthly statistical measures: the seasonally adjusted All Employees: Total Nonfarm (PAYEMS) and All Employees: Total Nonfarm (PAYNSA), which is not seasonally adjusted.
The series comes from the ‘Current Employment Statistics (Establishment Survey).’
The source code is: CES0000000001
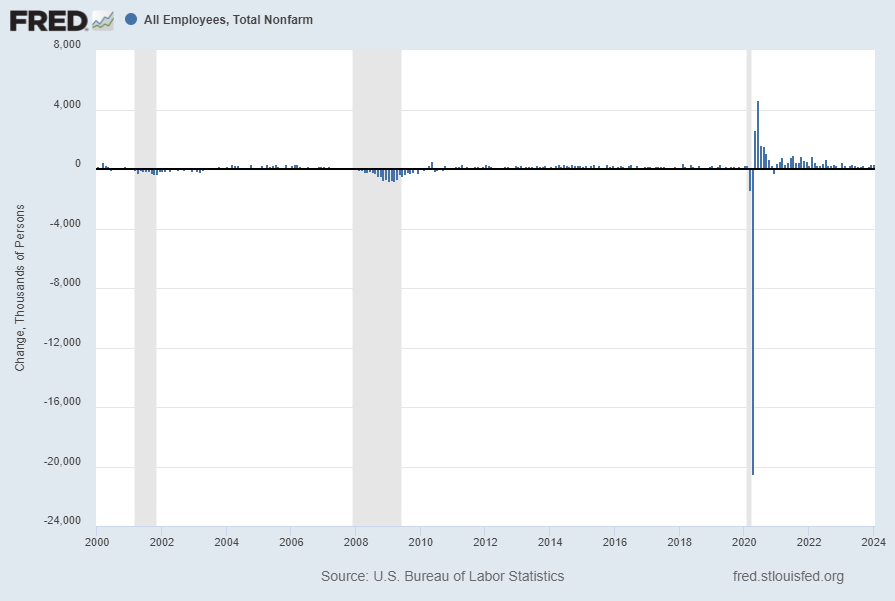
The first chart shows the monthly change in Total Nonfarm Payroll from the year 2000 through the current January 2024 report (January 2024 value of 353 (Thousands)):
(click on charts to enlarge images)
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis: All Employees: Total Nonfarm [PAYEMS] ; U.S. Department of Labor: Bureau of Labor Statistics; accessed February 2, 2024; https://fred.stlouisfed.org/series/PAYEMS
The second chart shows a longer-term chart of the same month-over-month change in Total Nonfarm Payroll (reports of February 1939 through the present report of January 2024):
The third chart shows the aggregate number of Total Nonfarm Payroll, from the reports of January 1939 – January 2024 (January 2024 value of 157.700 million):
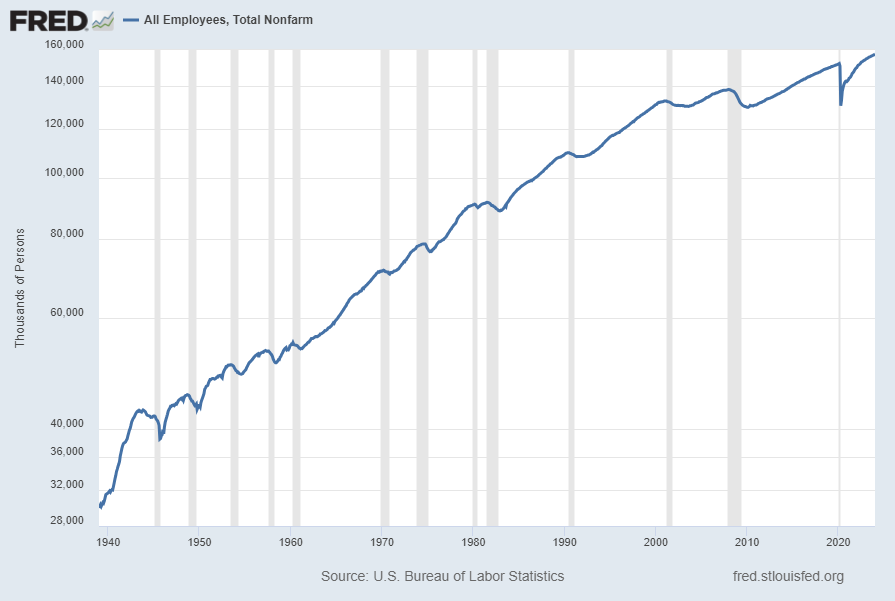
The fourth chart shows this same measure of aggregate number of Total Nonfarm Payroll as seen above but presented on a LOG scale:
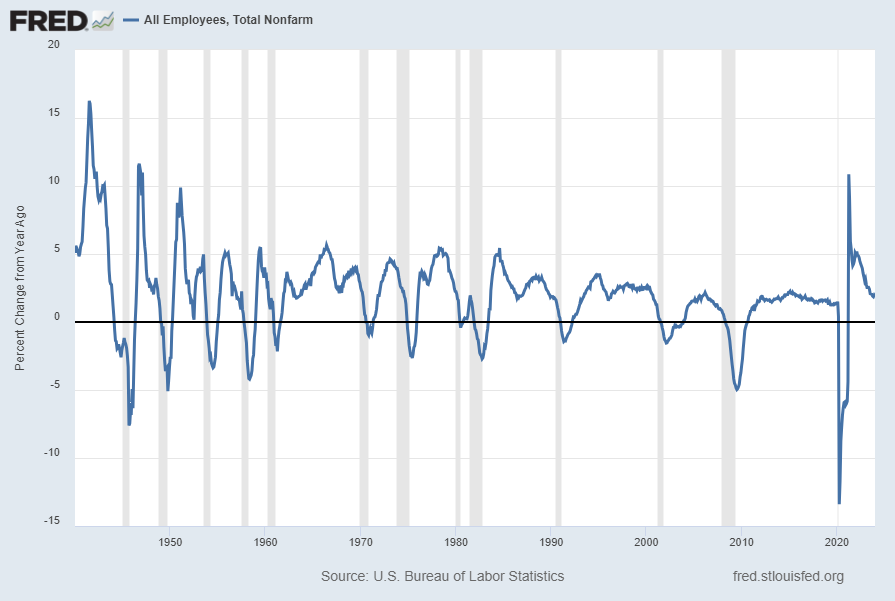
Lastly, the fifth chart shows the Total Nonfarm Payroll number on a “Percent Change from Year Ago” basis from January 1940 – January 2024: (January 2024 value of 1.9%)
_________
I post various indicators and indices because I believe they should be carefully monitored. However, as those familiar with this site are aware, I do not necessarily agree with what they depict or imply.
_____
The Special Note summarizes my overall thoughts about our economic situation