Friday, December 5, 2014

U-3 And U-6 Unemployment Rate Long-Term Reference Charts As Of December 5, 2014

Shortly after each monthly employment report I have been posting a continual series titled “3 Critical Unemployment Charts.”
Of course, there are many other employment charts that can be displayed as well.
For reference purposes, below are the U-3 and U-6 Unemployment Rate charts from a long-term historical perspective.  Both charts are from the St. Louis Fed site.  The U-3 measure is what is commonly referred to as the official unemployment rate; whereas the U-6 rate is officially (per Bureau of Labor Statistics) defined as:
Total unemployed, plus all persons marginally attached to the labor force, plus total employed part time for economic reasons, as a percent of the civilian labor force plus all persons marginally attached to the labor force
Of note, many economic observers use the U-6 rate as a (closer) proxy of the actual unemployment rate rather than that depicted by the U-3 measure.
Here is the U-3 chart, currently showing a 5.8% unemployment rate:
(click on charts to enlarge images)(charts updated as of 12-5-14)
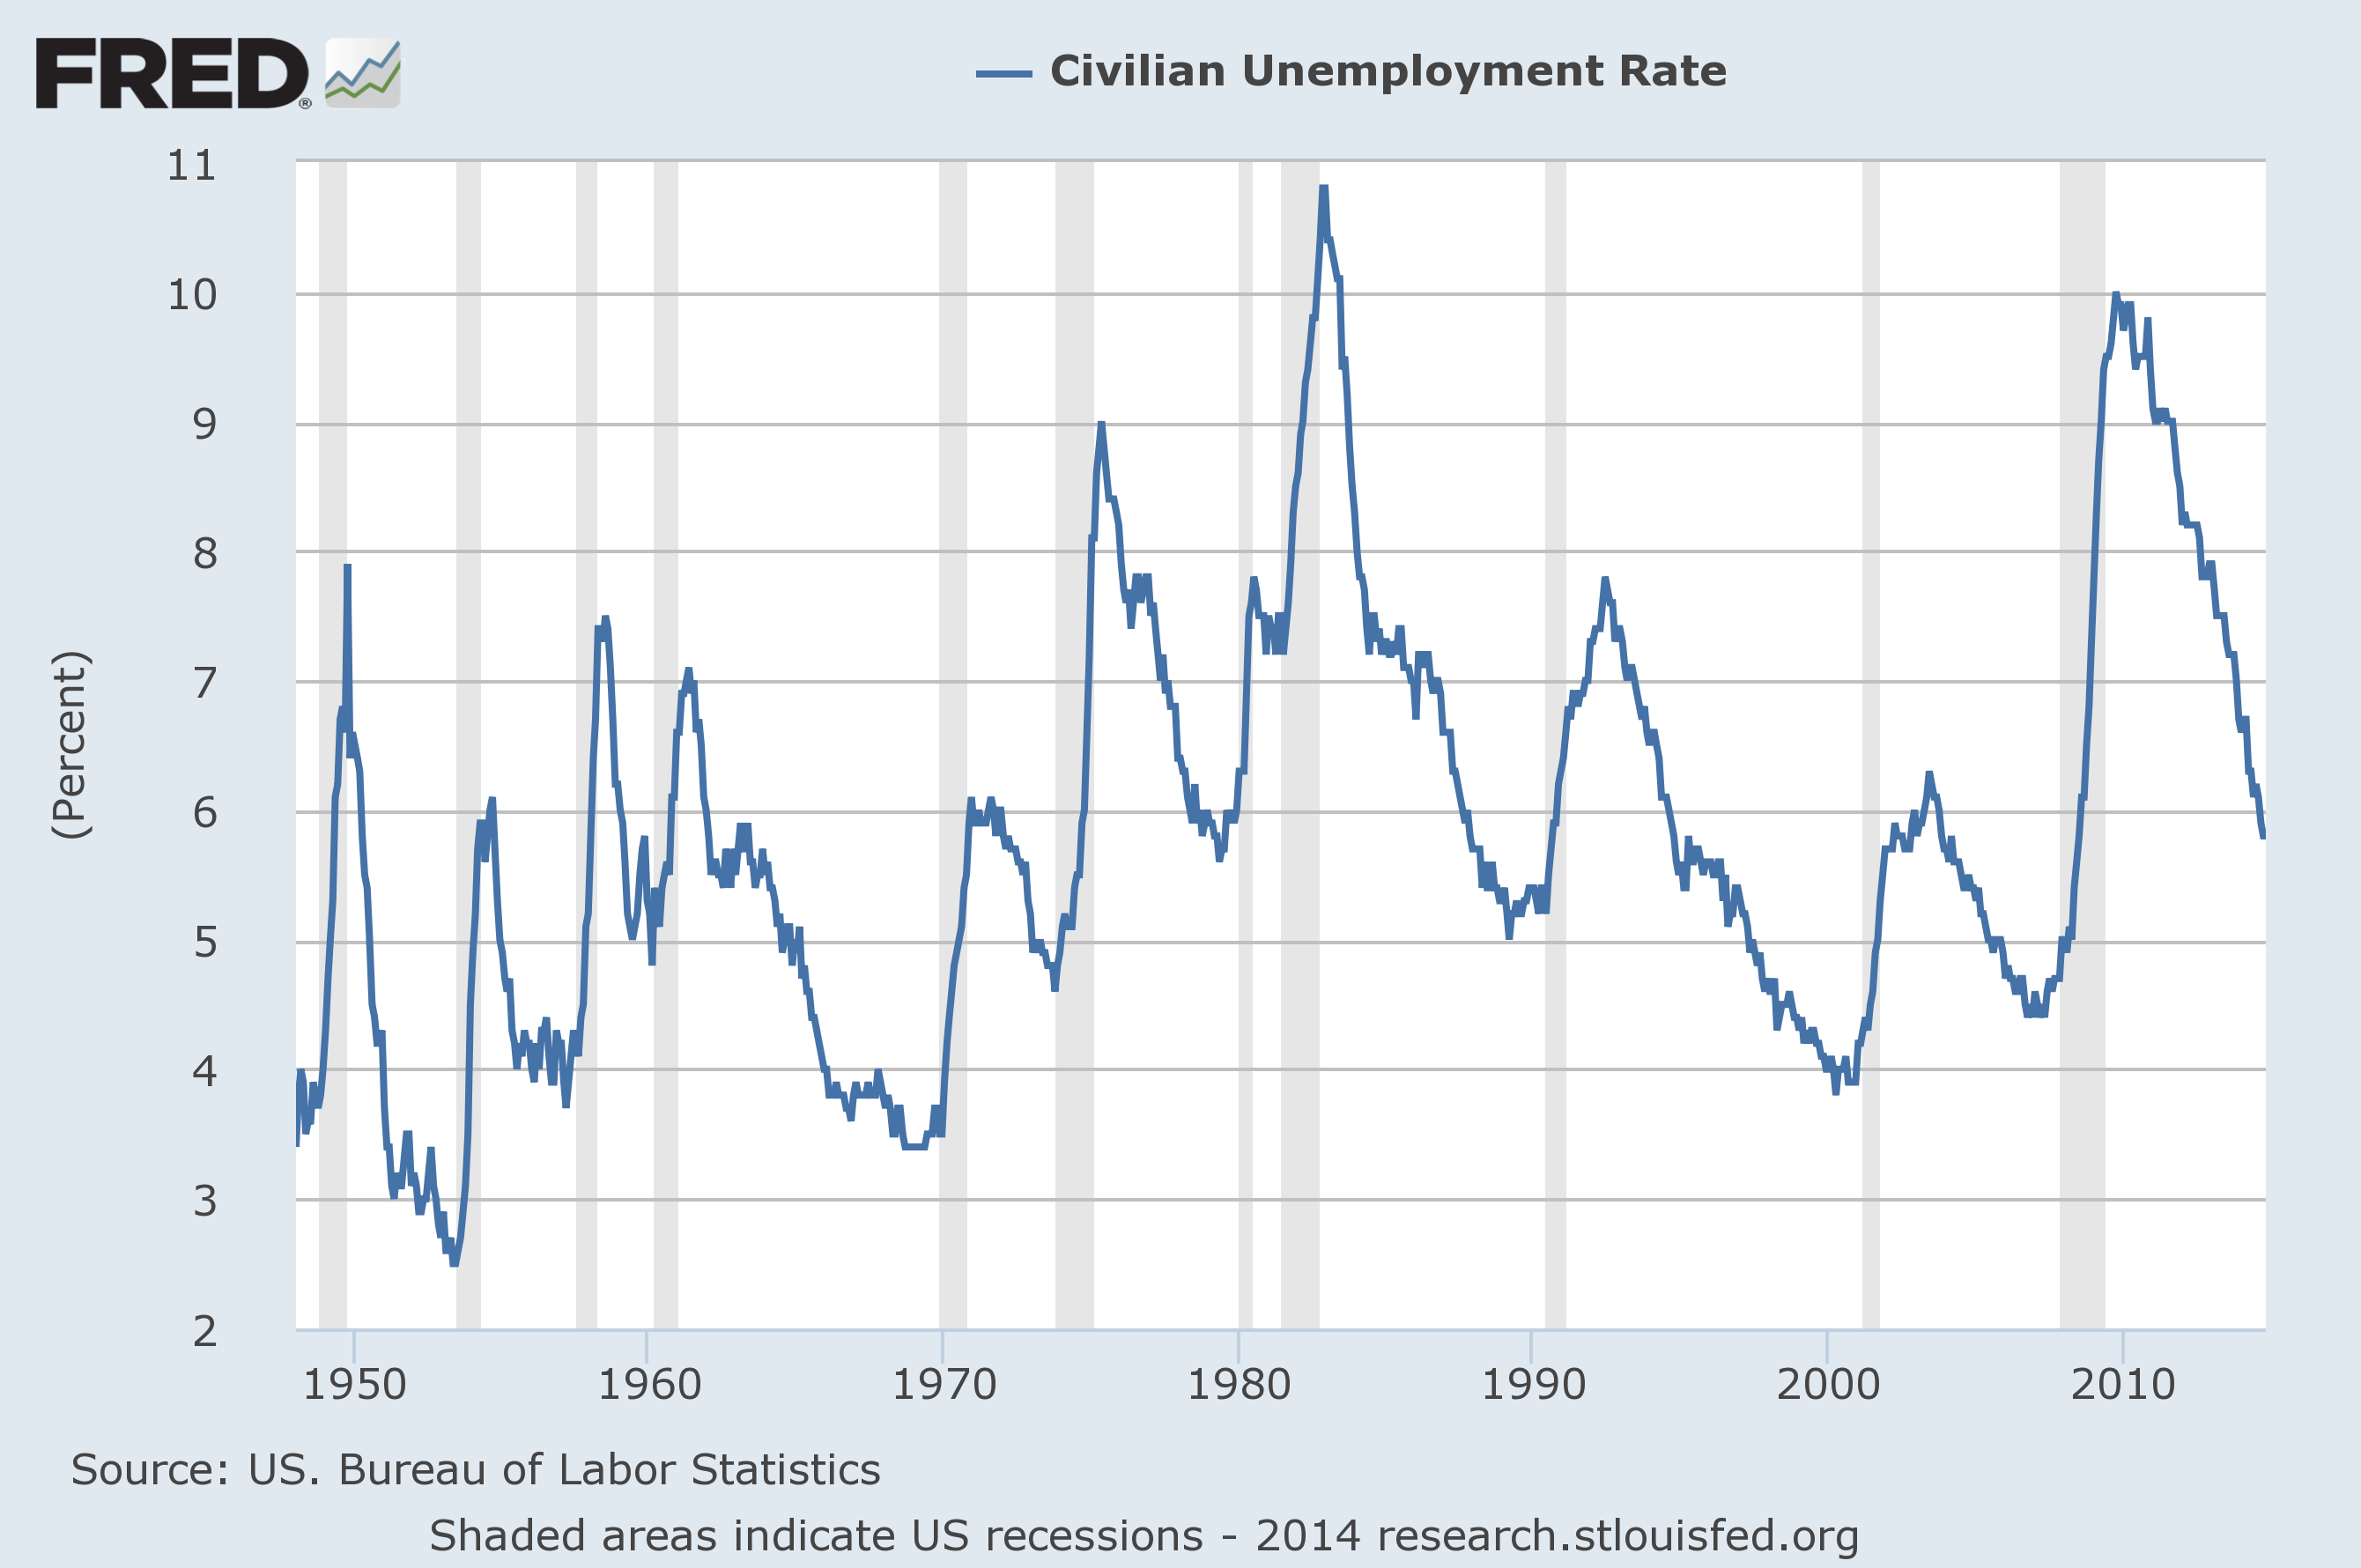
unemployment rate
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis: Civilian Unemployment Rate [UNRATE] ; U.S. Department of Labor: Bureau of Labor Statistics; accessed December 5, 2014;
–
Here is the U-6 chart, currently showing a 11.4% unemployment rate:
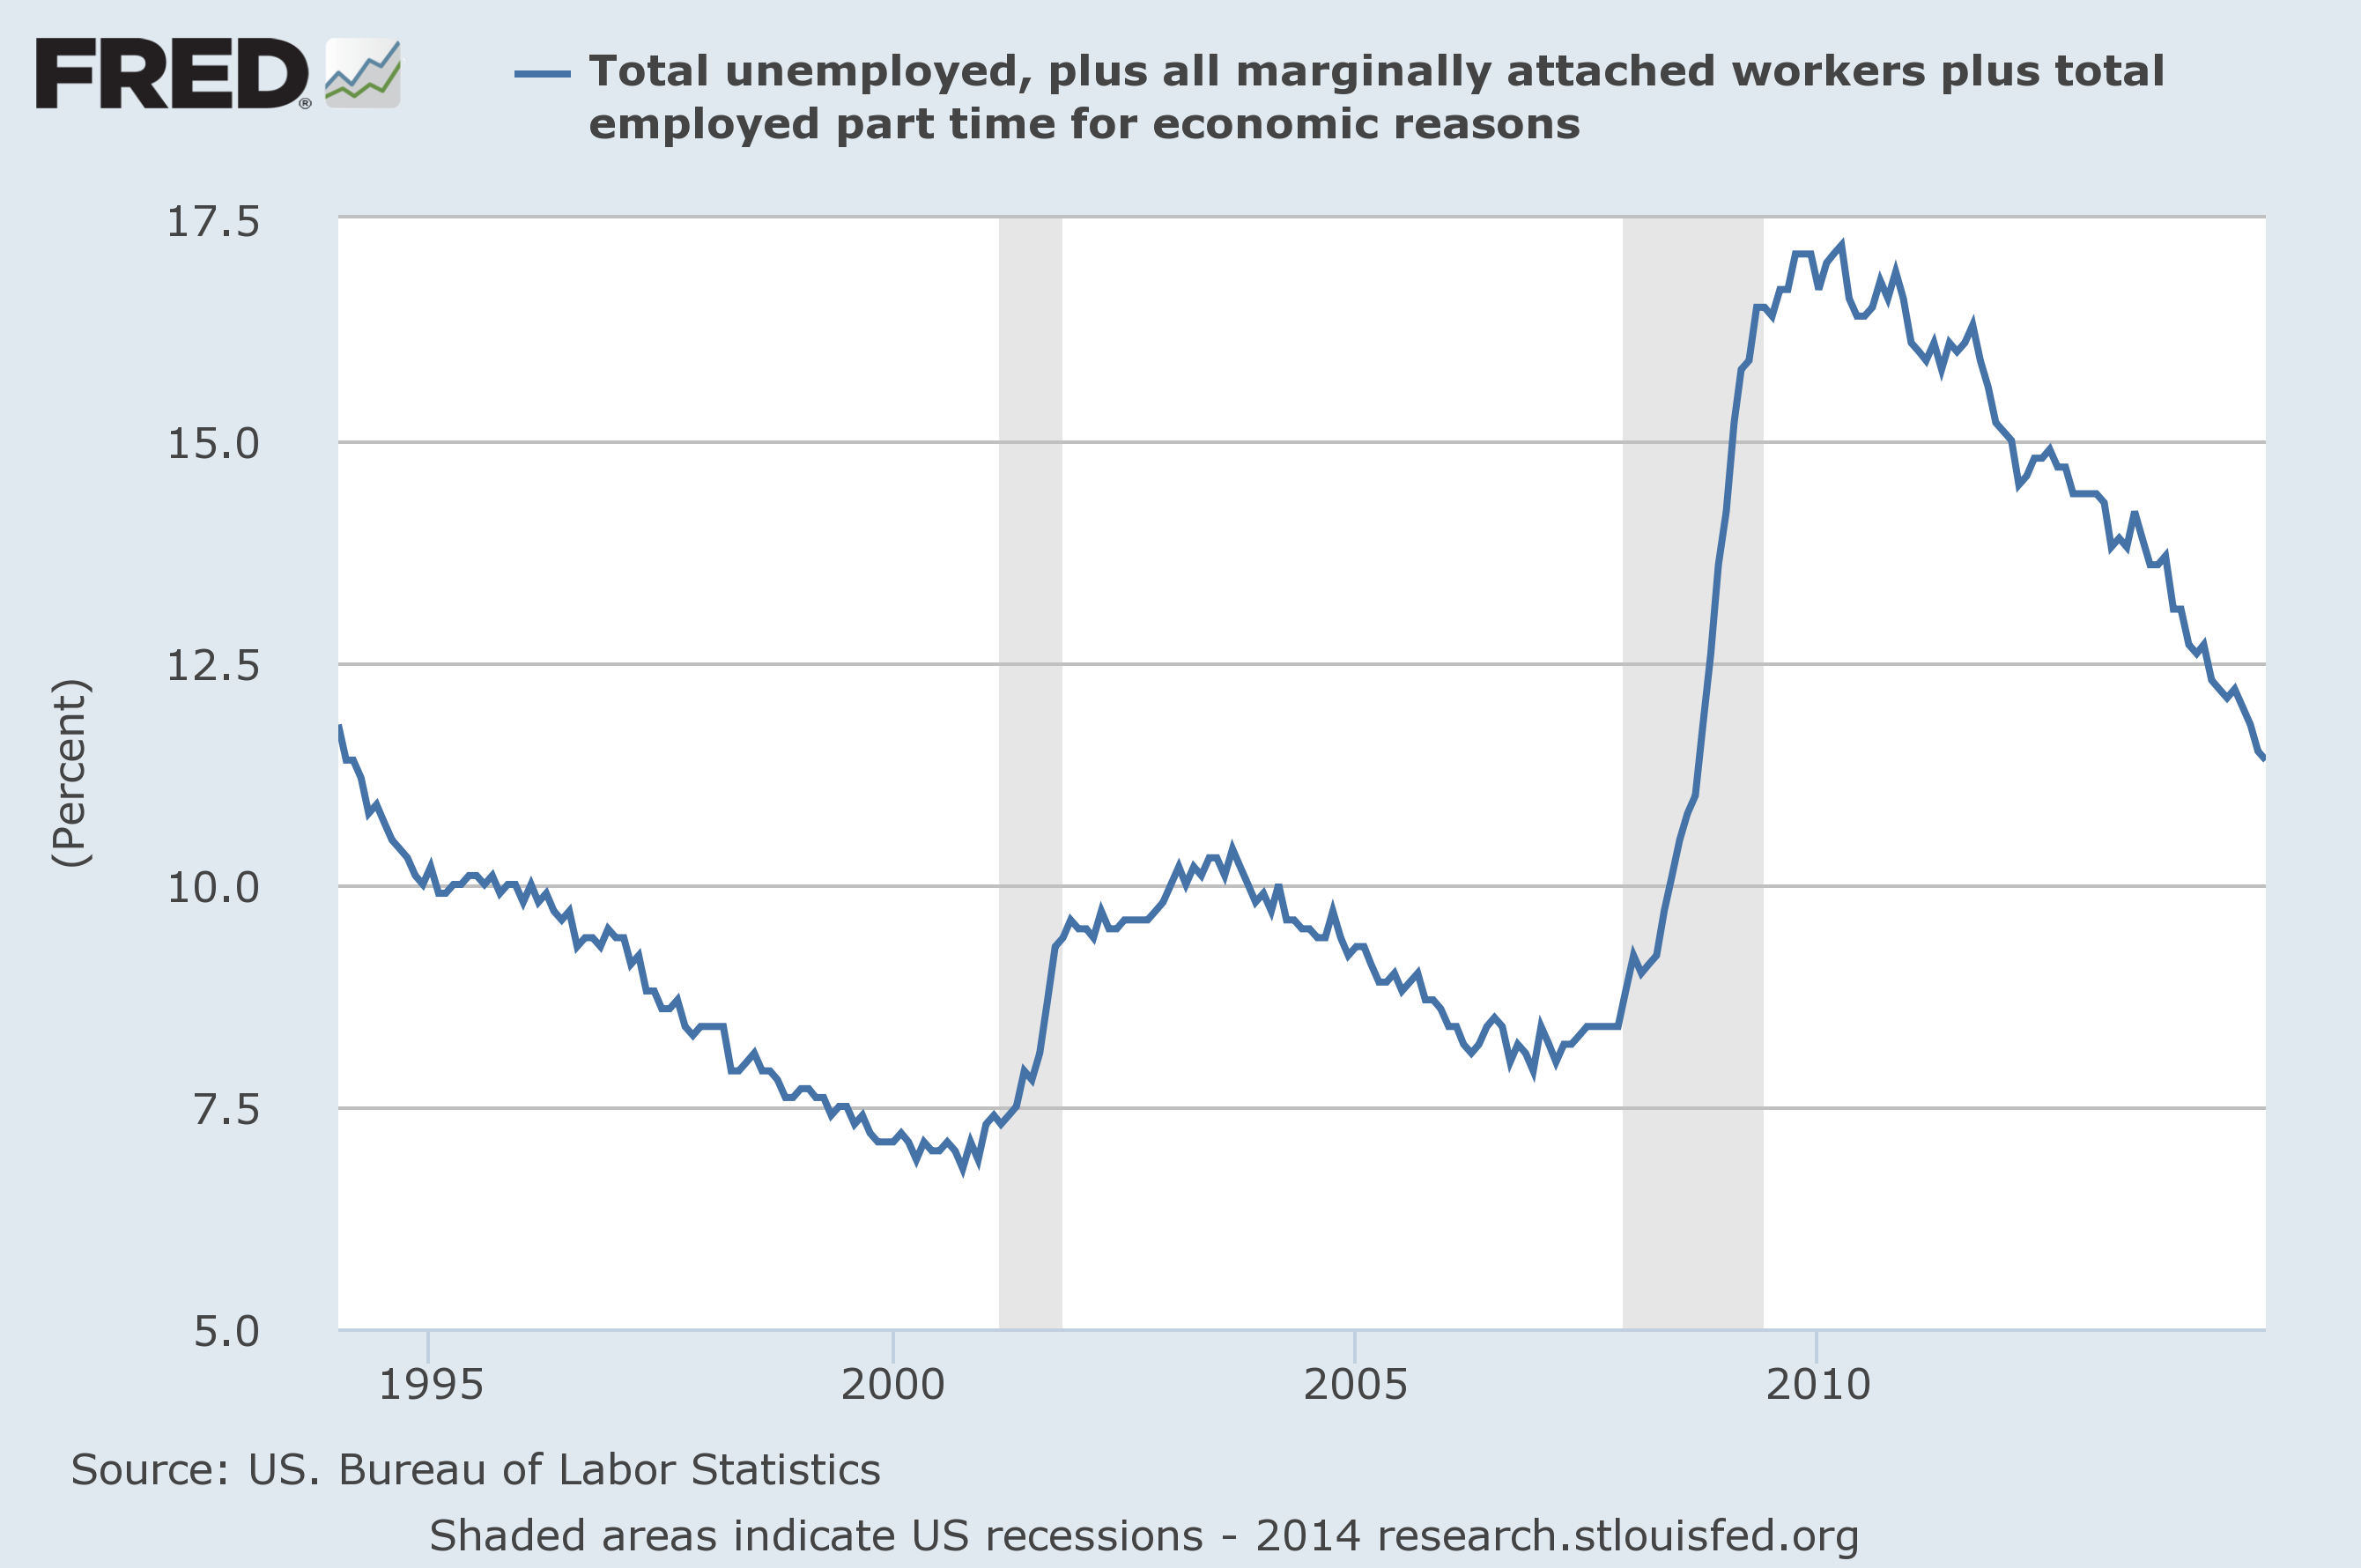
U-6 unemployment rate
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis: Total unemployed, plus all marginally attached workers plus total employed part time for economic reasons  [U6RATE] ; U.S. Department of Labor: Bureau of Labor Statistics; accessed December 5, 2014;
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 2075.85 as this post is written

3 Critical Unemployment Charts – December 2014

As I have commented previously, as in the October 6, 2009 post (“A Note About Unemployment Statistics”), in my opinion the official methodologies used to measure the various job loss and unemployment statistics do not provide an accurate depiction; they serve to understate the severity of unemployment.
However, even if one chooses to look at the official statistics, the following charts provide an interesting (and disconcerting) long-term perspective of certain aspects of the officially-stated unemployment situation.
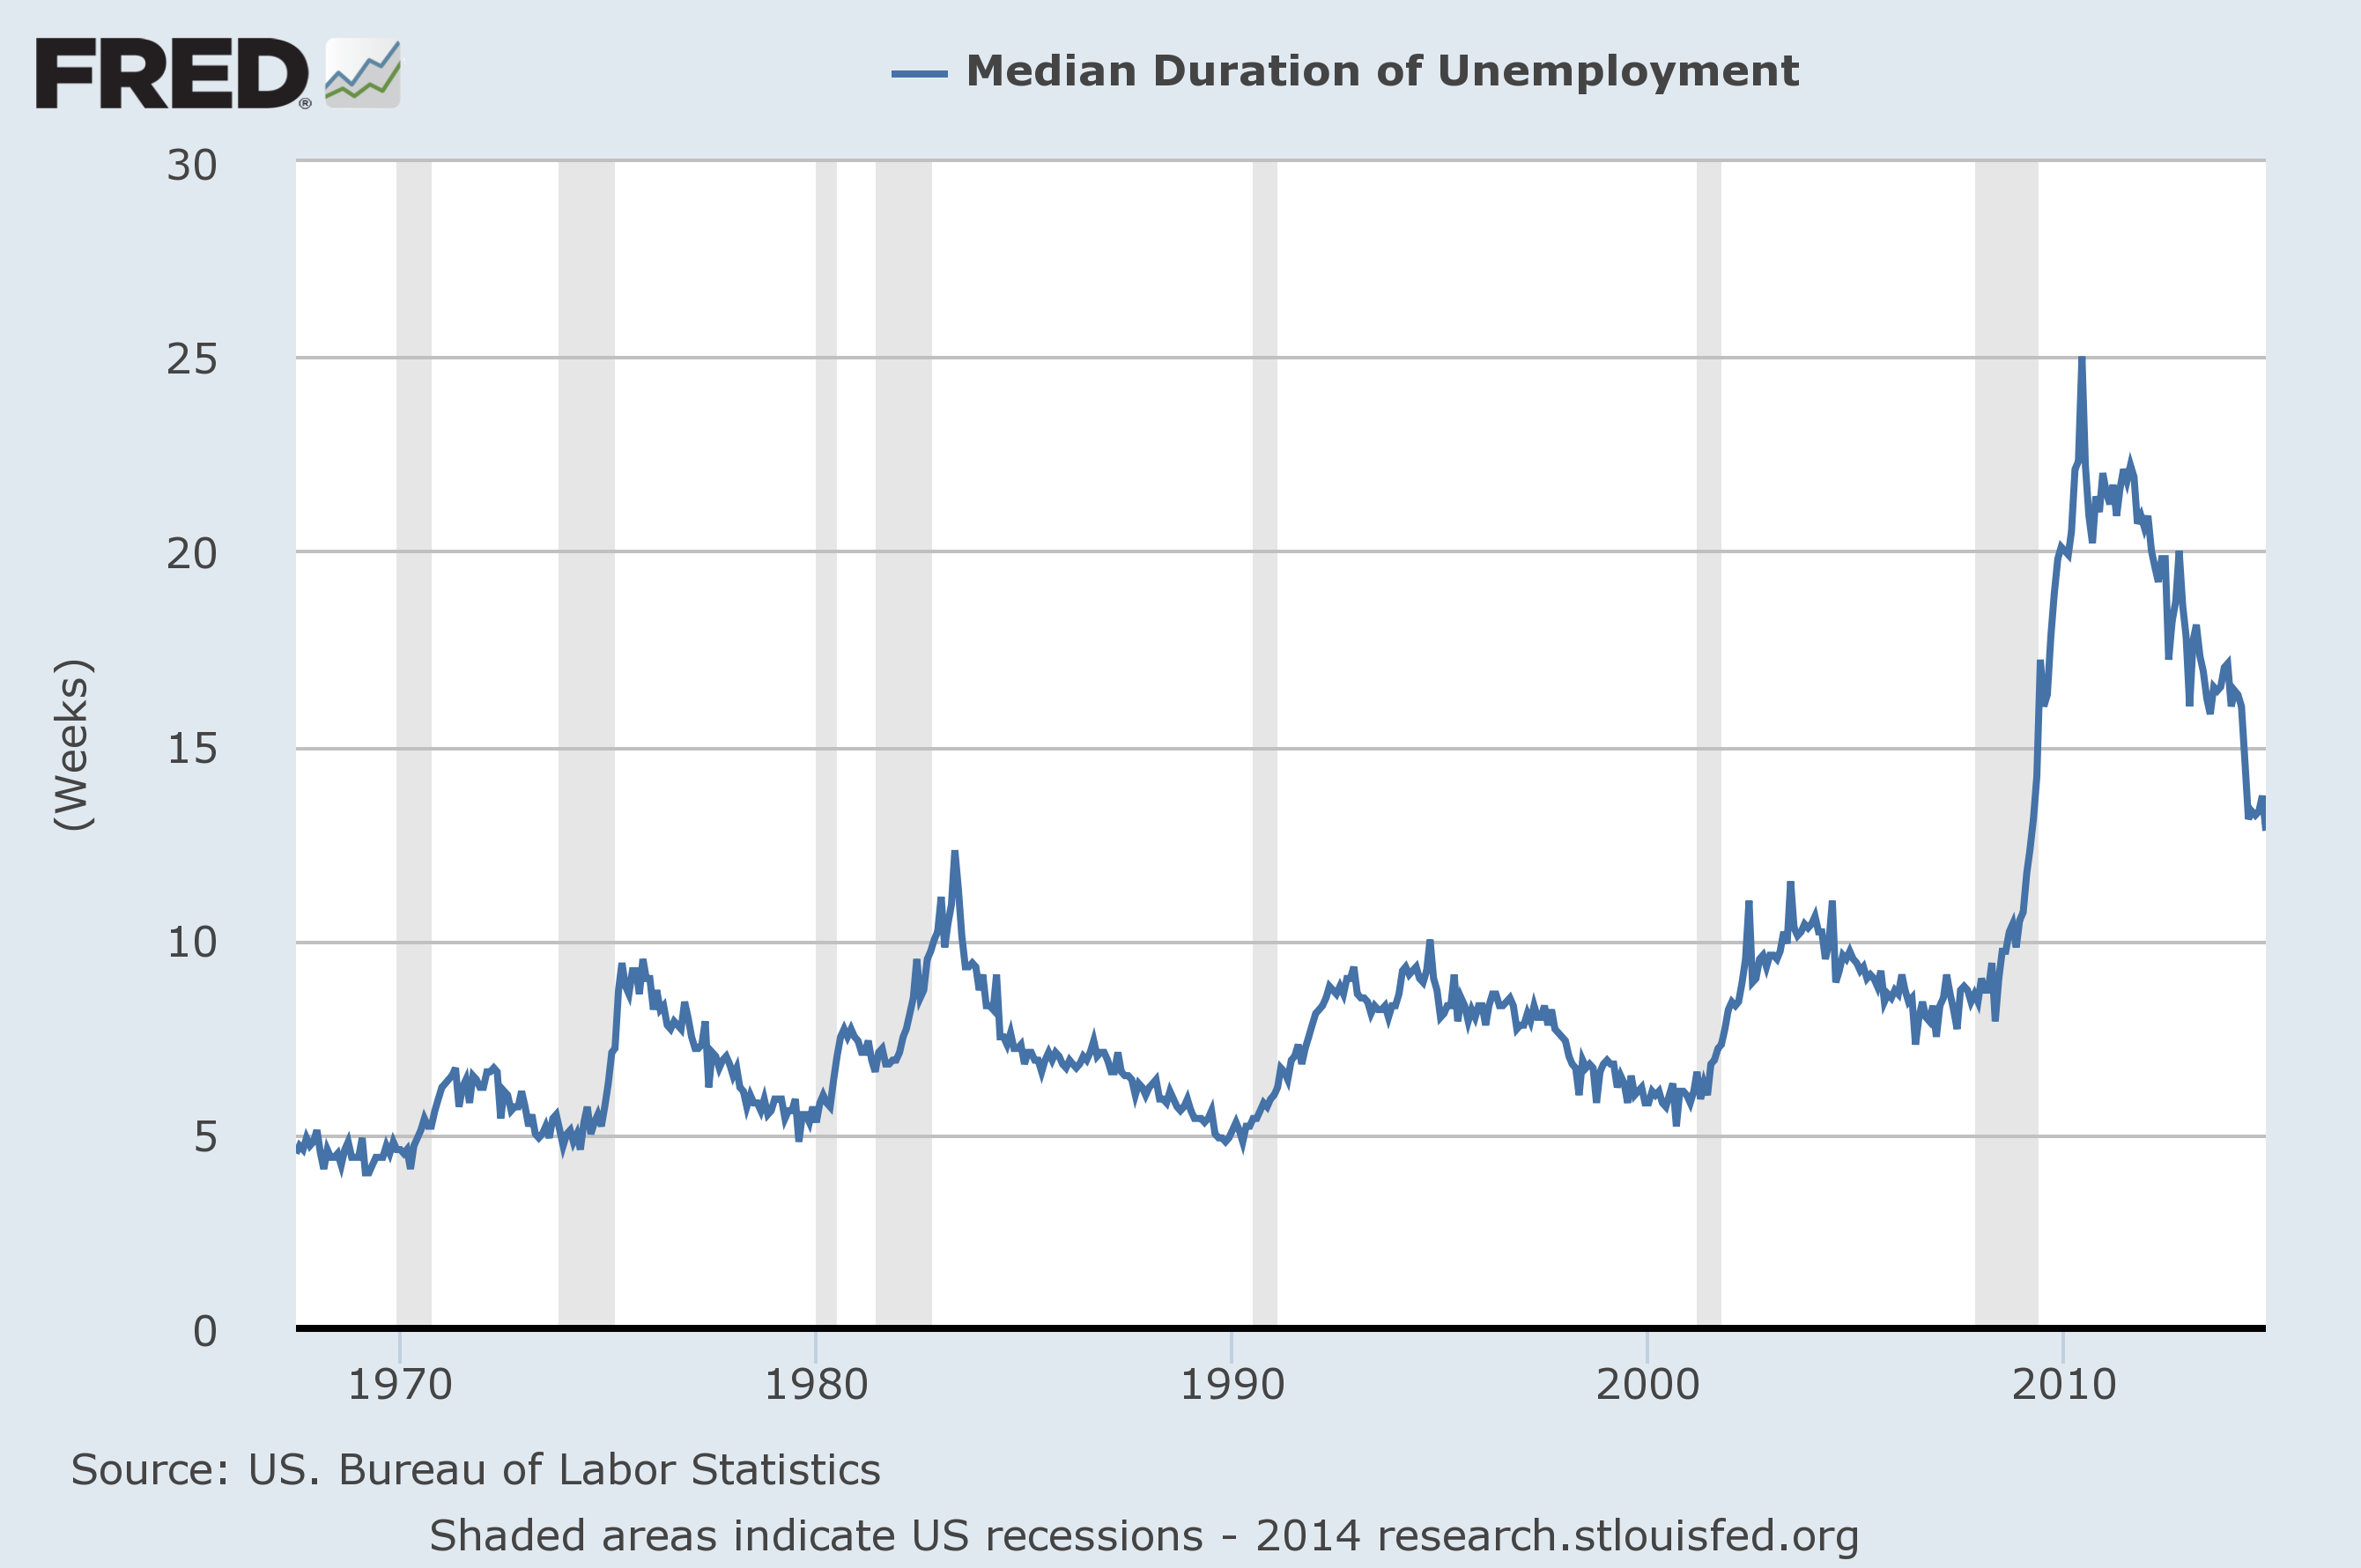
The three charts below are from the St. Louis Fed site.  Here is the Median Duration of Unemployment (current value = 12.8 weeks) :
(click on charts to enlarge images)(charts updated as of 12-5-14)
Median Duration of Unemployment
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis: Median Duration of Unemployment [UEMPMED] ; U.S. Department of Labor: Bureau of Labor Statistics; accessed December 5, 2014;
–
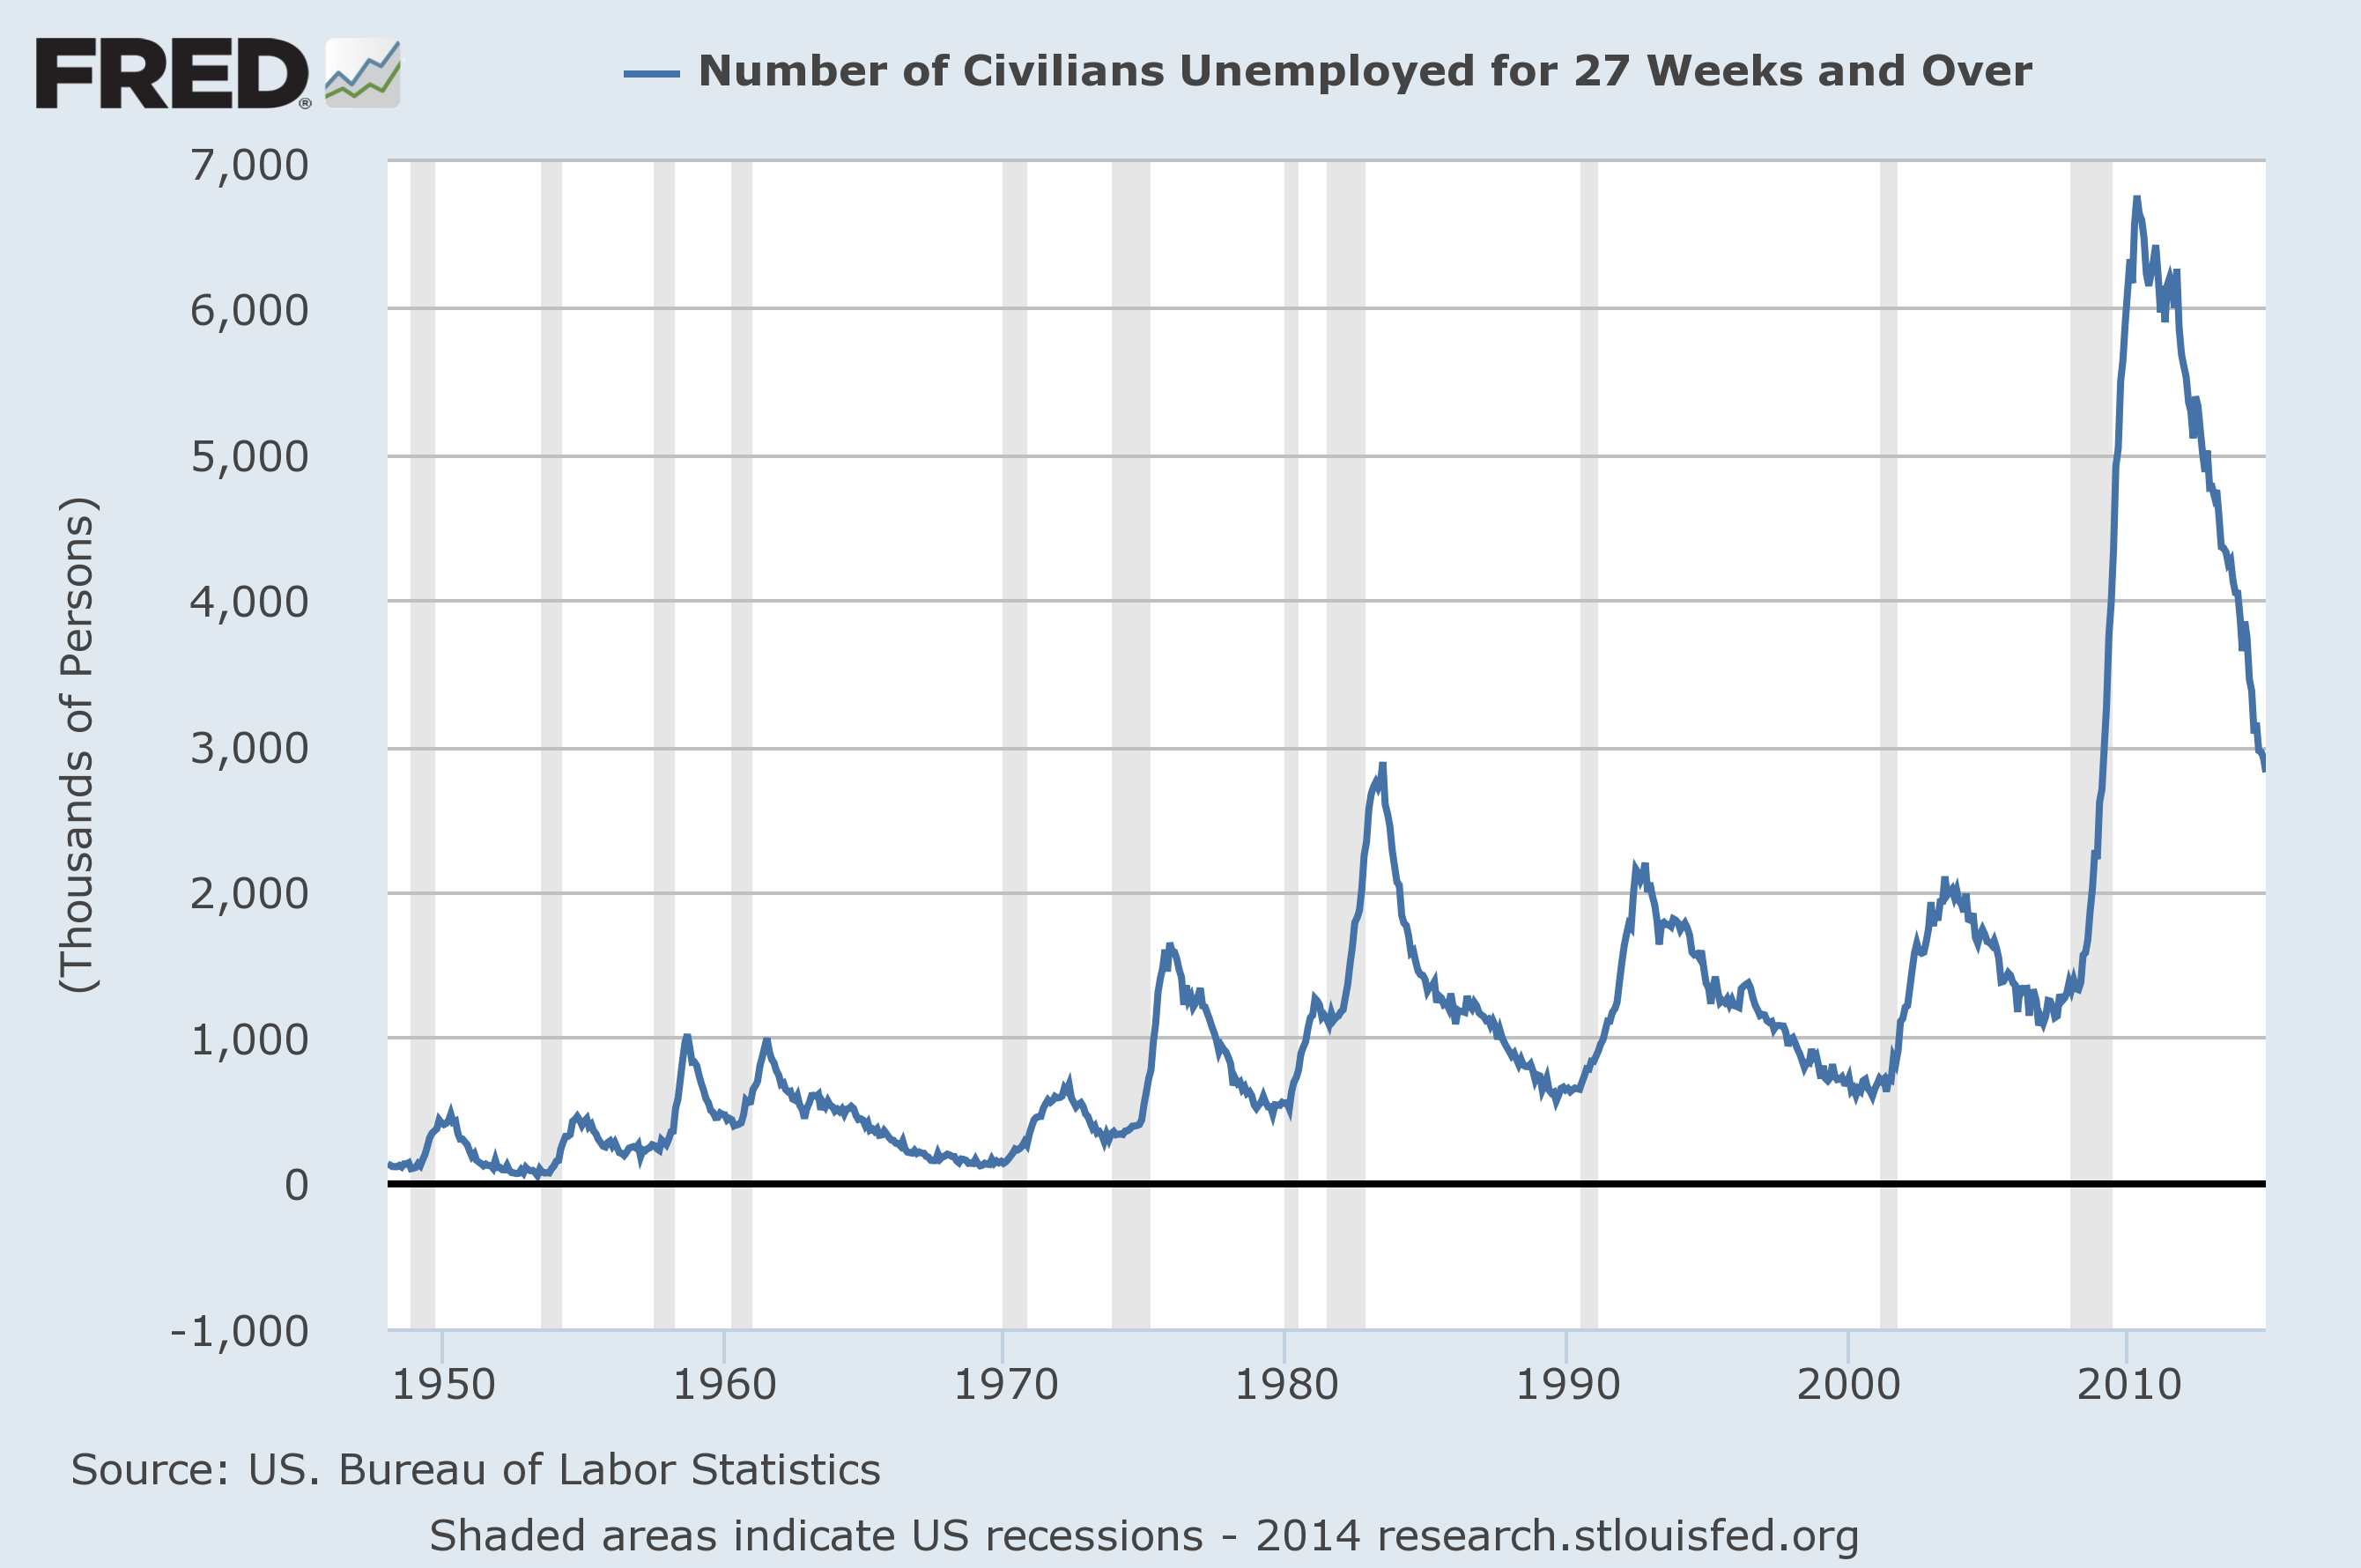
Here is the chart for Unemployed 27 Weeks and Over (current value = 2.815 million) :
Unemployed 27 weeks and over
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis: Civilians Unemployed for 27 Weeks and Over [UEMP27OV] ; U.S. Department of Labor: Bureau of Labor Statistics; accessed December 5, 2014;
–
Here is the chart for Total Nonfarm Payroll (current value = 140.045 million) :
total nonfarm payrolls
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis: All Employees: Total nonfarm [PAYEMS] ; U.S. Department of Labor: Bureau of Labor Statistics; accessed December 5, 2014;
–
As depicted by these charts, our unemployment problem is severe.  Unfortunately, there do not appear to be any “easy” solutions.
On April 24, 2012 I wrote a five-part blog post titled “The Unemployment Situation Facing The United States”, which discusses various problematical issues concerning the present and future employment situation.
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 2075.61 as this post is written

VIX Weekly And Monthly Charts Since The Year 2000 – December 5, 2014 Update

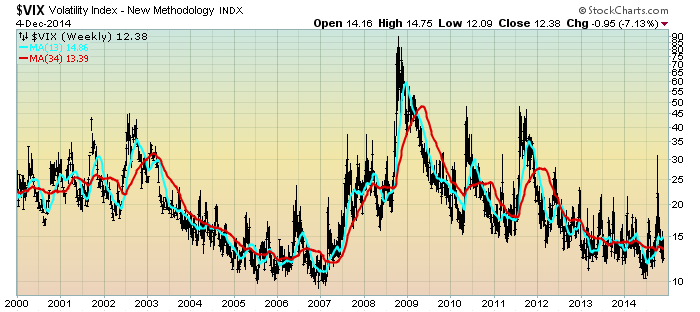
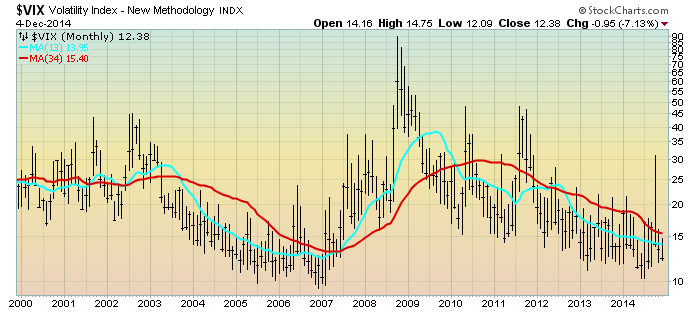
For reference purposes, below are two charts of the VIX from year 2000 through yesterday’s (December 4, 2014) close, which had a closing value of 12.38:
Below is the VIX Weekly chart, depicted on a LOG scale, with the 13- and 34-week moving averages, seen in the cyan and red lines, respectively:
(click on chart to enlarge image)(chart courtesy of StockCharts.com; chart creation and annotation by the author)
VIX Weekly chart
–
Here is the VIX Monthly chart, depicted on a LOG scale, with the 13- and 34-month moving average, seen in the cyan and red lines, respectively:
(click on chart to enlarge image)(chart courtesy of StockCharts.com; chart creation and annotation by the author)
VIX Monthly chart
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 2071.92 as this post is written

Wednesday, December 3, 2014

Chicago Fed National Financial Conditions Index (NFCI)

The St. Louis Fed’s Financial Stress Index (STLFSI) is one index that is supposed to measure stress in the financial system.  Its reading as of the November 26, 2014 update (reflecting data through November 21) is -1.088.
Of course, there are a variety of other measures and indices that are supposed to measure financial stress and other related issues, both from the Federal Reserve as well as from private sources.
Two other indices that I regularly monitor include the Chicago Fed National Financial Conditions Index (NFCI) as well as the Chicago Fed Adjusted National Financial Conditions Index (ANFCI).
Here are summary descriptions of each, as seen in FRED:
The National Financial Conditions Index (NFCI) measures risk, liquidity and leverage in money markets and debt and equity markets as well as in the traditional and “shadow” banking systems. Positive values of the NFCI indicate financial conditions that are tighter than average, while negative values indicate financial conditions that are looser than average.
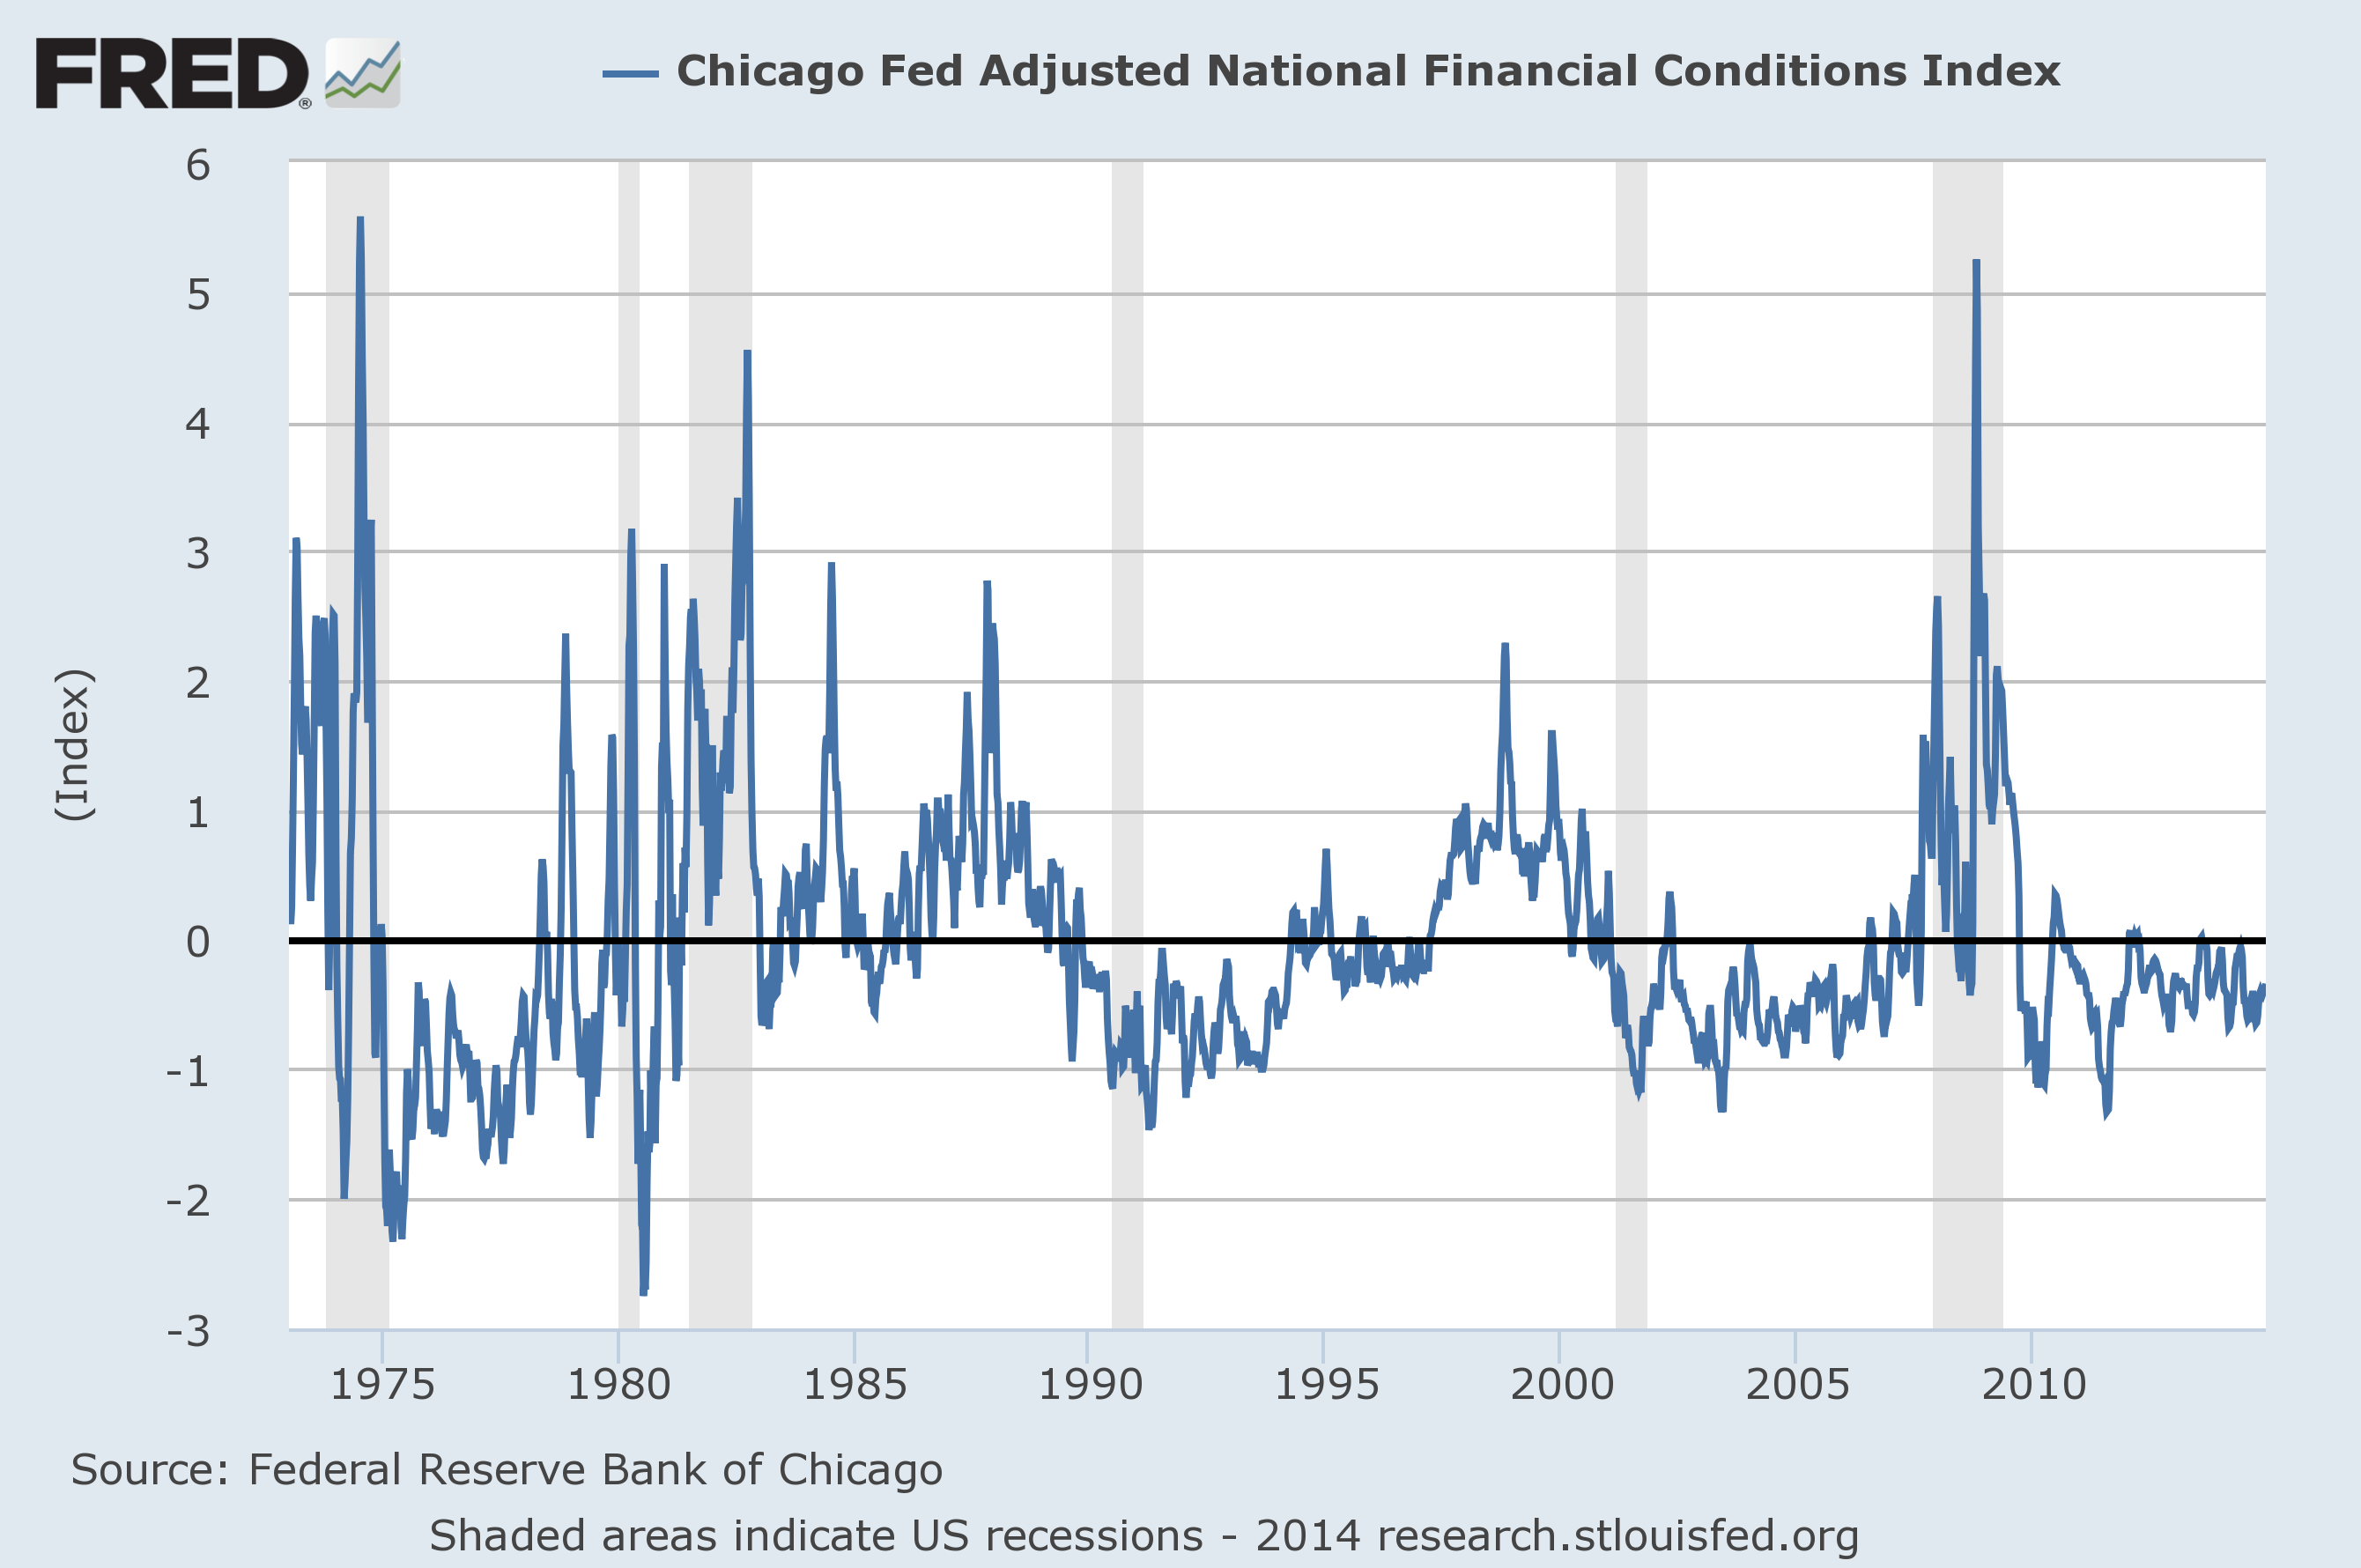
The adjusted NFCI (ANFCI). This index isolates a component of financial conditions uncorrelated with economic conditions to provide an update on how financial conditions compare with current economic conditions.
For further information, please visit the Federal Reserve Bank of Chicago’s web site:
Below are the most recently updated charts of the NFCI and ANFCI, respectively.
The NFCI chart below was last updated on December 3, incorporating data from January 5,1973 to November 28, 2014, on a weekly basis.  The November 28, 2014 value is -.84:
(click on chart to enlarge image)
NFCI chart
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis; accessed December 3, 2014:
–
The ANFCI chart below was last updated on December 3, incorporating data from January 5,1973 to November 28, 2014, on a weekly basis.  The November 28, 2014 value is -.34:
ANFCI chart
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis; accessed December 3, 2014:
_________
I post various indicators and indices because I believe they should be carefully monitored.  However, as those familiar with this blog are aware, I do not necessarily agree with what they depict or imply.
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 2070.85 as this post is written
Recession Probability Models – December 2014

There are a variety of economic models that are supposed to predict the probabilities of recession.
While I don’t agree with the methodologies employed or probabilities of impending economic weakness as depicted by the following two models, I think the results of these models should be monitored.
Please note that each of these models is updated regularly, and the results of these – as well as other recession models – can fluctuate significantly.
The first is the “Yield Curve as a Leading Indicator” from the New York Federal Reserve.  I wrote a blog post concerning this measure on March 1, 2010, titled “The Yield Curve as a Leading Indicator.”
Currently (last updated December 2, 2014 using data through November) this “Yield Curve” model shows a 2.30% probability of a recession in the United States twelve months ahead.  For comparison purposes, it showed a 2.41% probability through October, and a chart going back to 1960 is seen at the “Probability Of U.S. Recession Predicted by Treasury Spread.” (pdf)
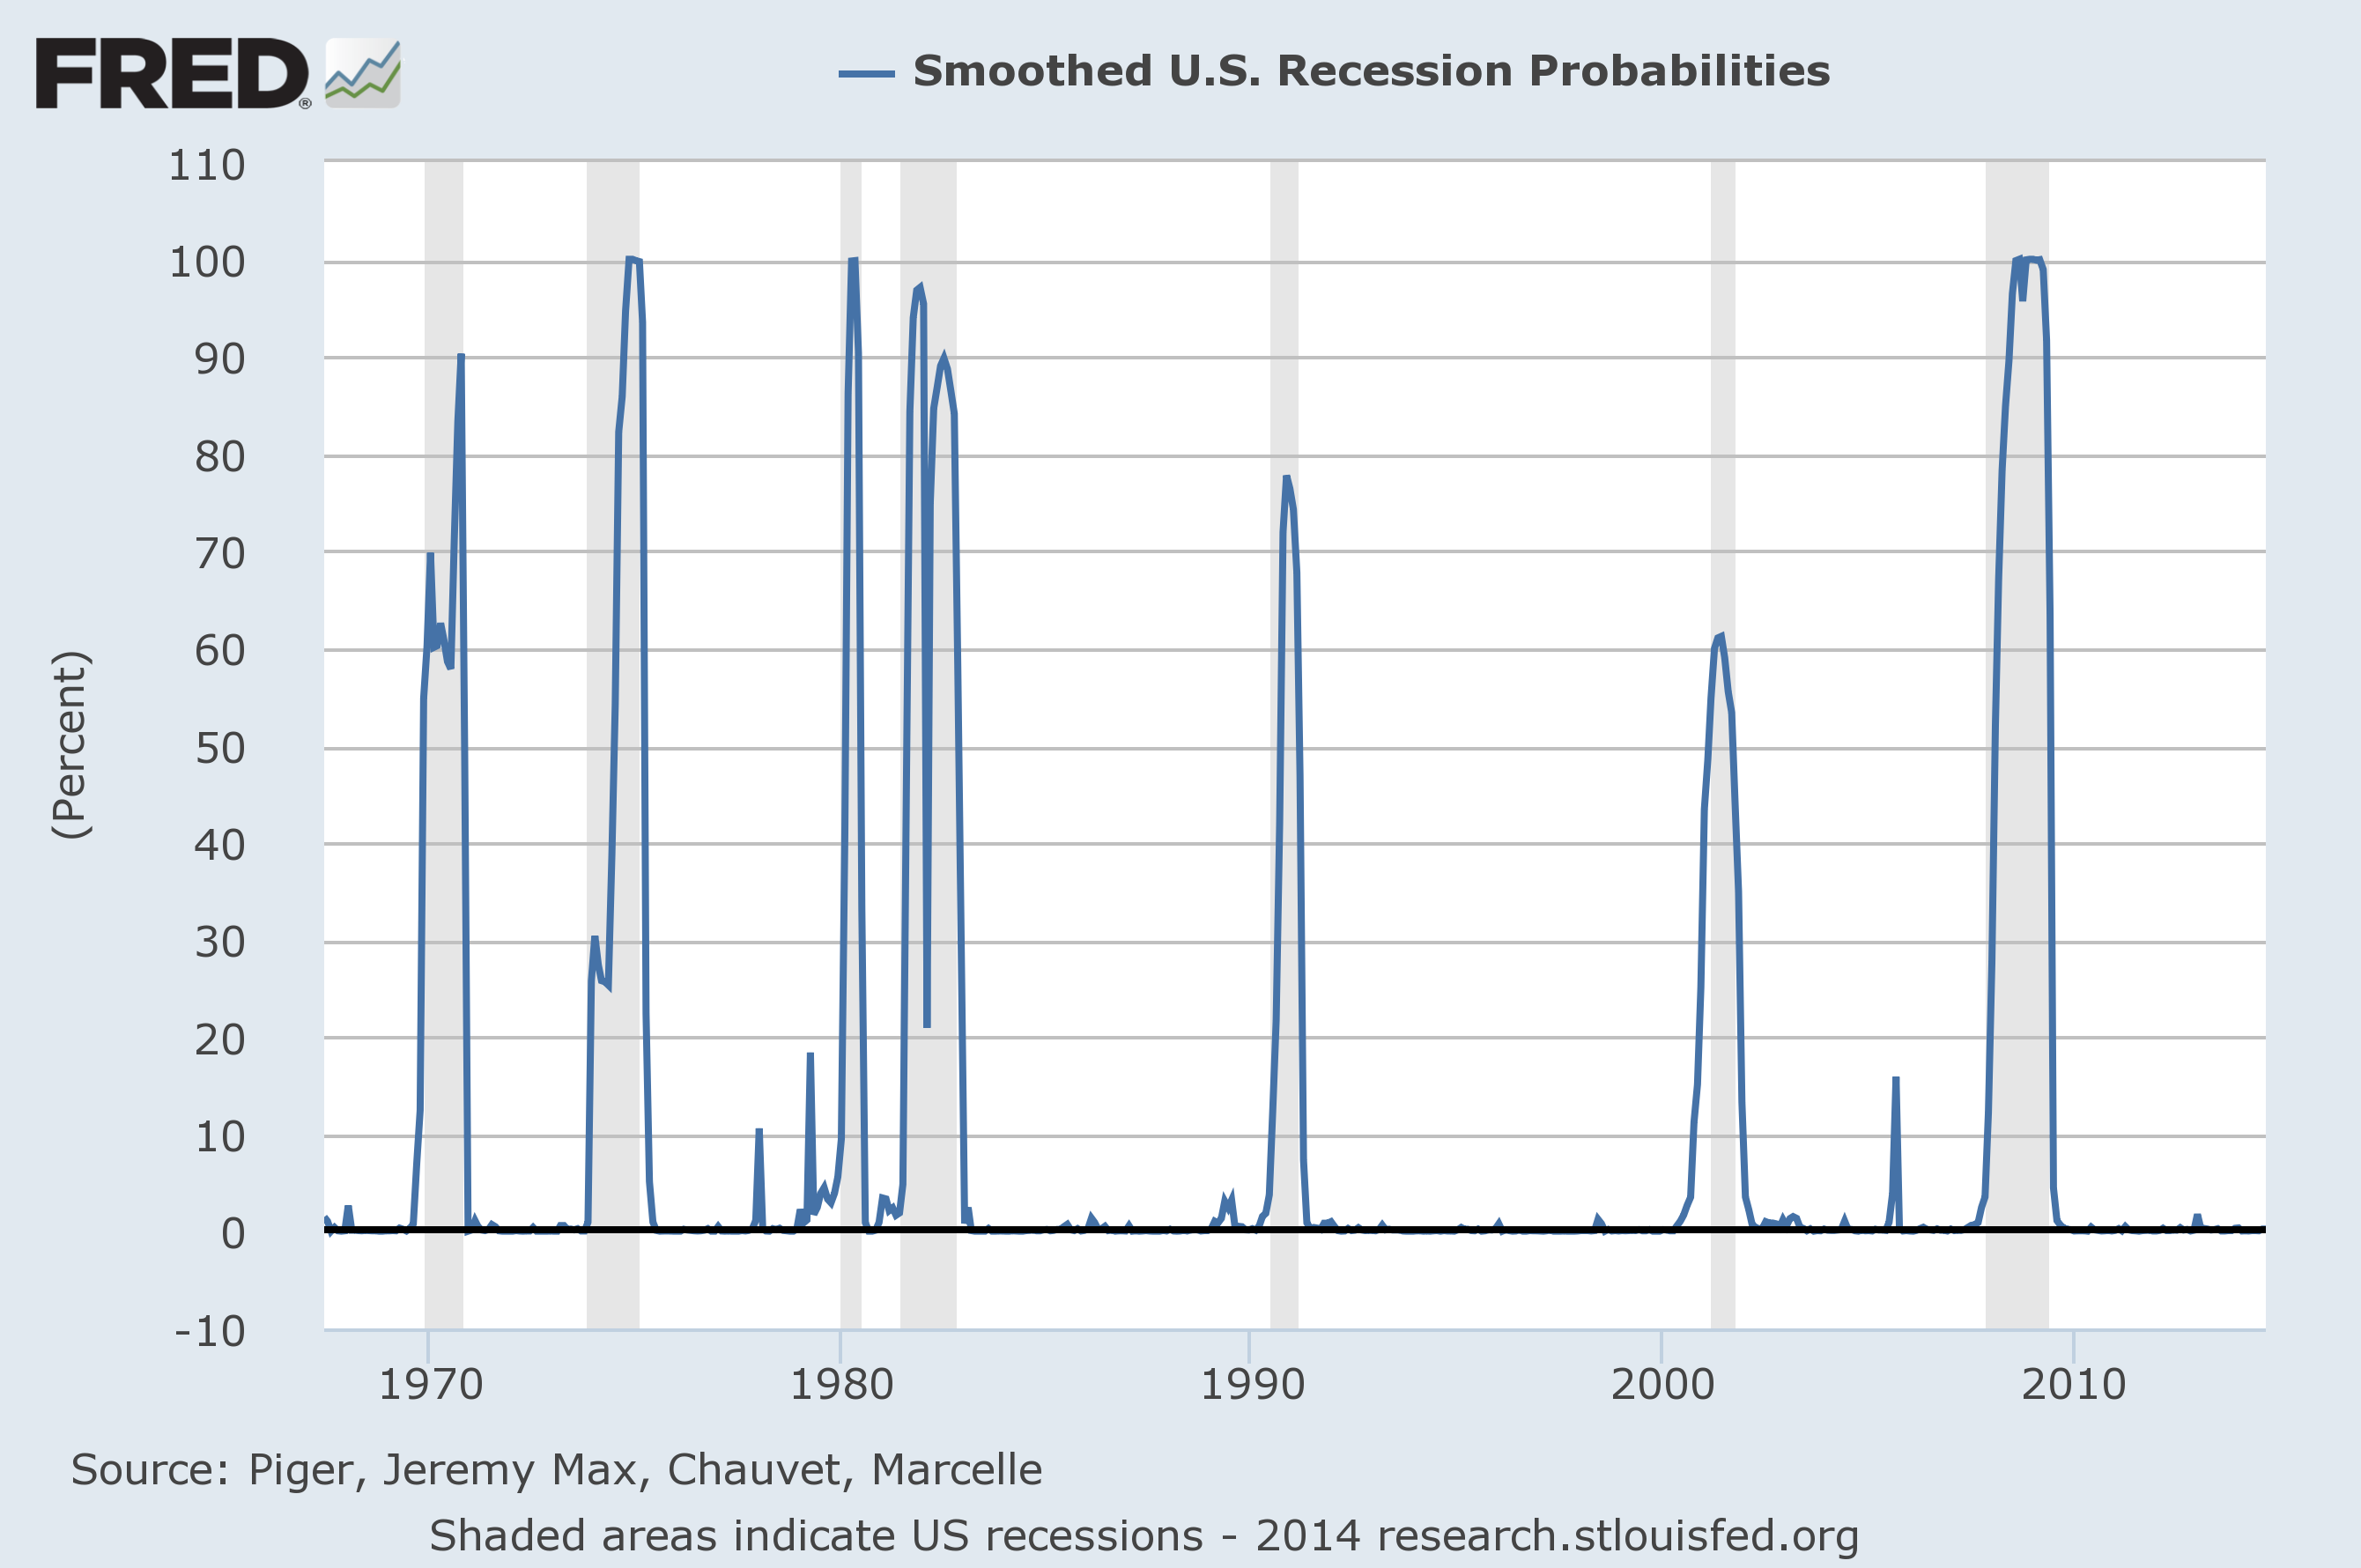
The second model is from Marcelle Chauvet and Jeremy Piger.  This model is described on the St. Louis Federal Reserve site (FRED) as follows:
Smoothed recession probabilities for the United States are obtained from a dynamic-factor markov-switching model applied to four monthly coincident variables: non-farm payroll employment, the index of industrial production, real personal income excluding transfer payments, and real manufacturing and trade sales. This model was originally developed in Chauvet, M., “An Economic Characterization of Business Cycle Dynamics with Factor Structure and Regime Switching,” International Economic Review, 1998, 39, 969-996. (http://faculty.ucr.edu/~chauvet/ier.pdf)
Additional details and explanations can be seen on the “U.S. Recession Probabilities” page.
This model, last updated on December 1, 2014, currently shows a .22% probability using data through September.
Here is the FRED chart (last updated December 1, 2014):
Probability of Recession
Data Source: Piger, Jeremy Max and Chauvet, Marcelle, Smoothed U.S. Recession Probabilities [RECPROUSM156N], retrieved from FRED, Federal Reserve Bank of St. Louis https://research.stlouisfed.org/fred2/series/RECPROUSM156N/, December 2, 2014:
–
The two models featured above can be compared against measures seen in recent blog posts.  For instance, as seen in the November 13 post titled “The November 2014 Wall Street Journal Economic Forecast Survey“ economists surveyed averaged a 11.73% probability of a U.S. recession within the next 12 months.
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 2066.55 as this post is written
Tuesday, December 2, 2014

December 2 Gallup Poll Results On Economic Confidence – Notable Excerpts

On December 2, 2014 Gallup released the poll results titled “U.S. Economic Confidence Index at 17-month High.”
Notable excerpts include:
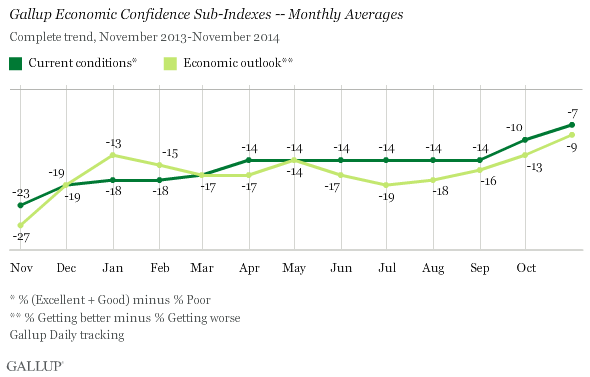
Gallup's U.S. Economic Confidence Index climbed to -8 in November, the highest monthly reading in nearly a year and a half. The index in November essentially matches the post-recession high of -7 in May 2013.
also:
Gallup's Economic Confidence Index is the average of two components: how Americans view current economic conditions, and their perceptions of whether the economy is getting better or worse. In November, 24% said the economy is "excellent" or "good," while 30% said it is "poor," resulting in a current conditions score of -7, the highest current conditions score since January 2008.
Meanwhile, 43% of Americans said the economy is "getting better," while 52% said it is "getting worse." This resulted in an economic outlook score of -9 -- the best outlook score since July 2013.
Here is an accompanying chart of the two components (Sub-Indexes) of the Gallup Economic Confidence Index, discussed above:
Gallup Economic Confidence Sub-Indexes
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 2061.04 as this post is written

Ultra Long-Term Charts Of The DJIA, Transports, S&P500, And Nasdaq

StockCharts.com maintains long-term historical charts of various major stock market indices, interest rates, currencies, commodities, and economic indicators.
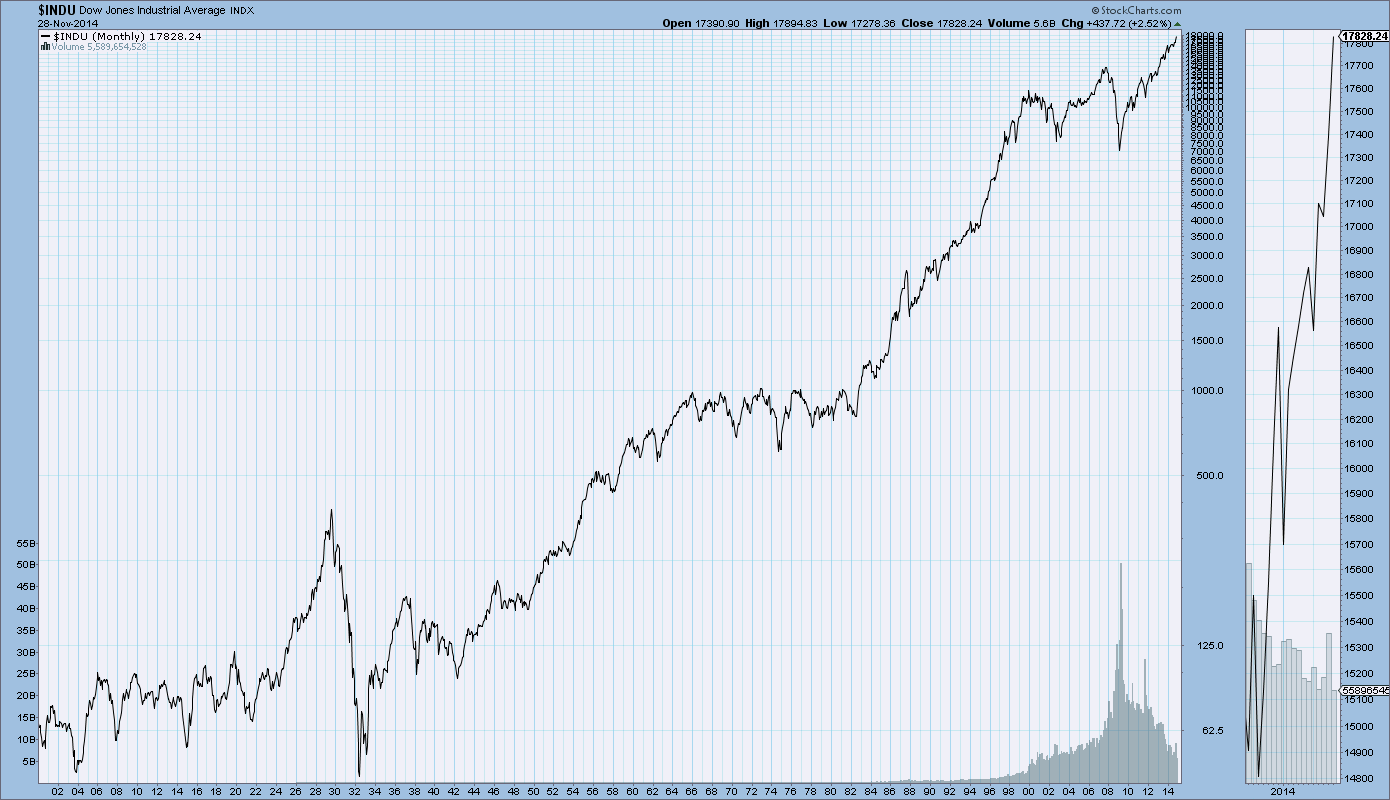
As a long-term reference, below are charts depicting various stock market indices for the dates shown.  All charts are depicted on a monthly basis using a LOG scale.
(click on charts to enlarge images)(charts courtesy of StockCharts.com)
The DJIA, from 1900-November 28, 2014:
DJIA chart 1900-November 2014
–
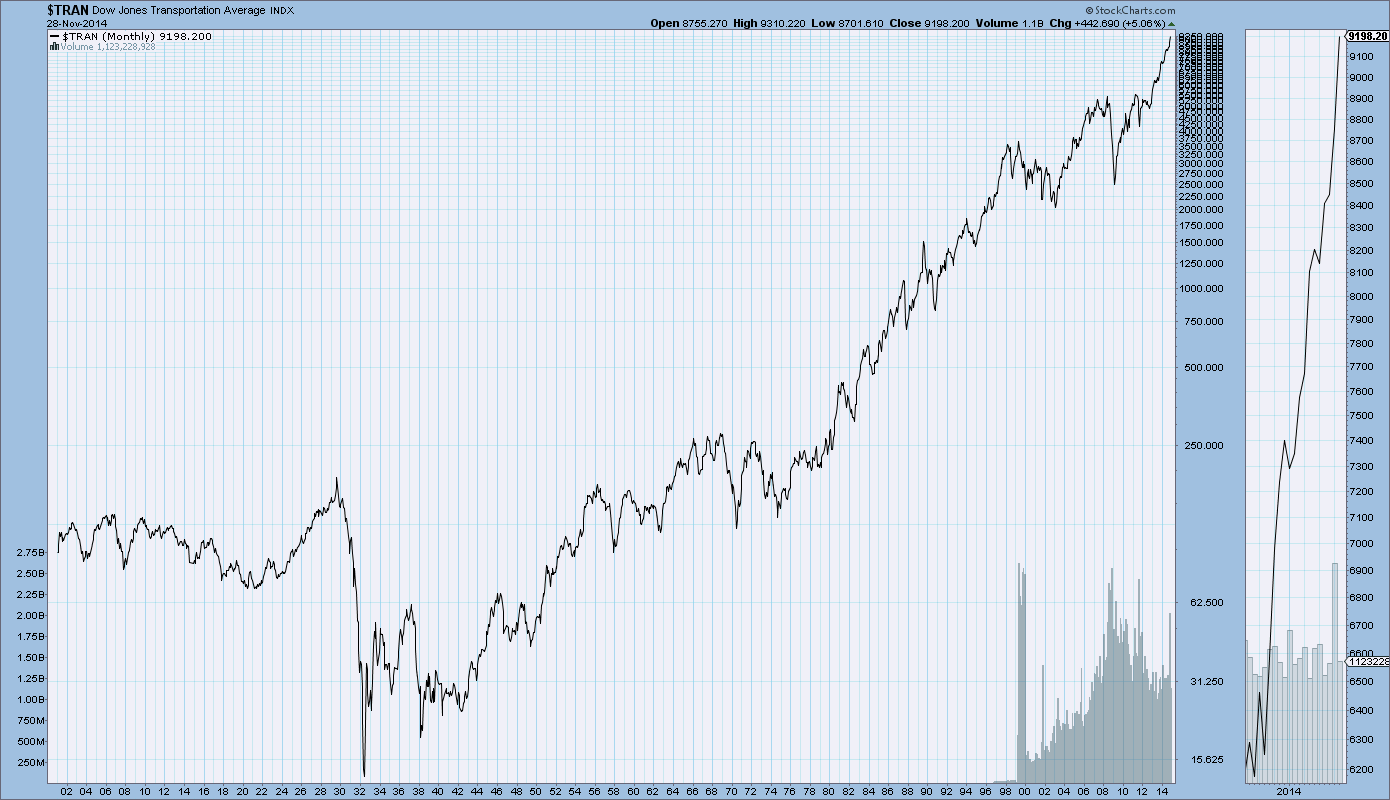
The Dow Jones Transportation Average, from 1900-November 28, 2014:
Dow Jones Transportation Average 1900-November 2014
–
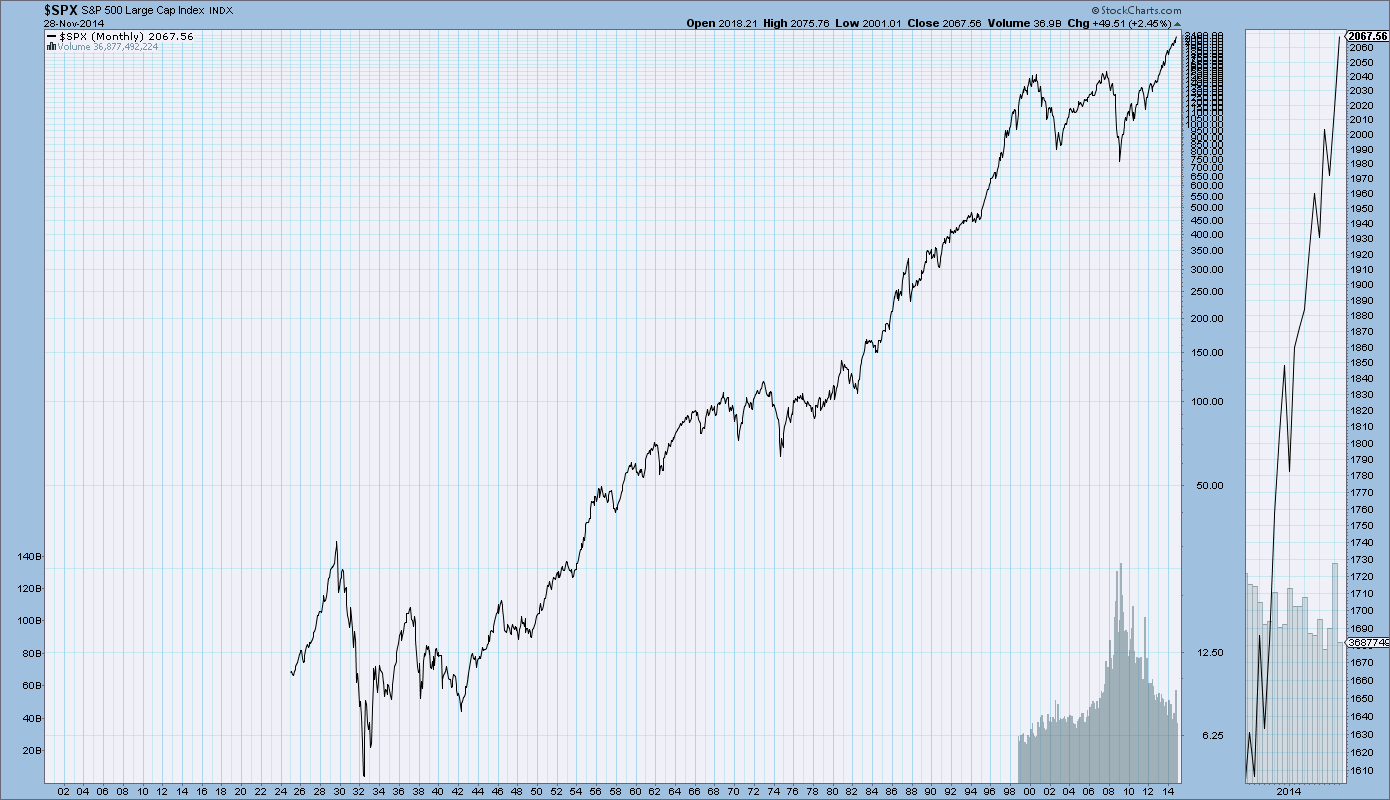
The S&P500, from 1925-November 28, 2014:
S&P500 1925-November 2014
–
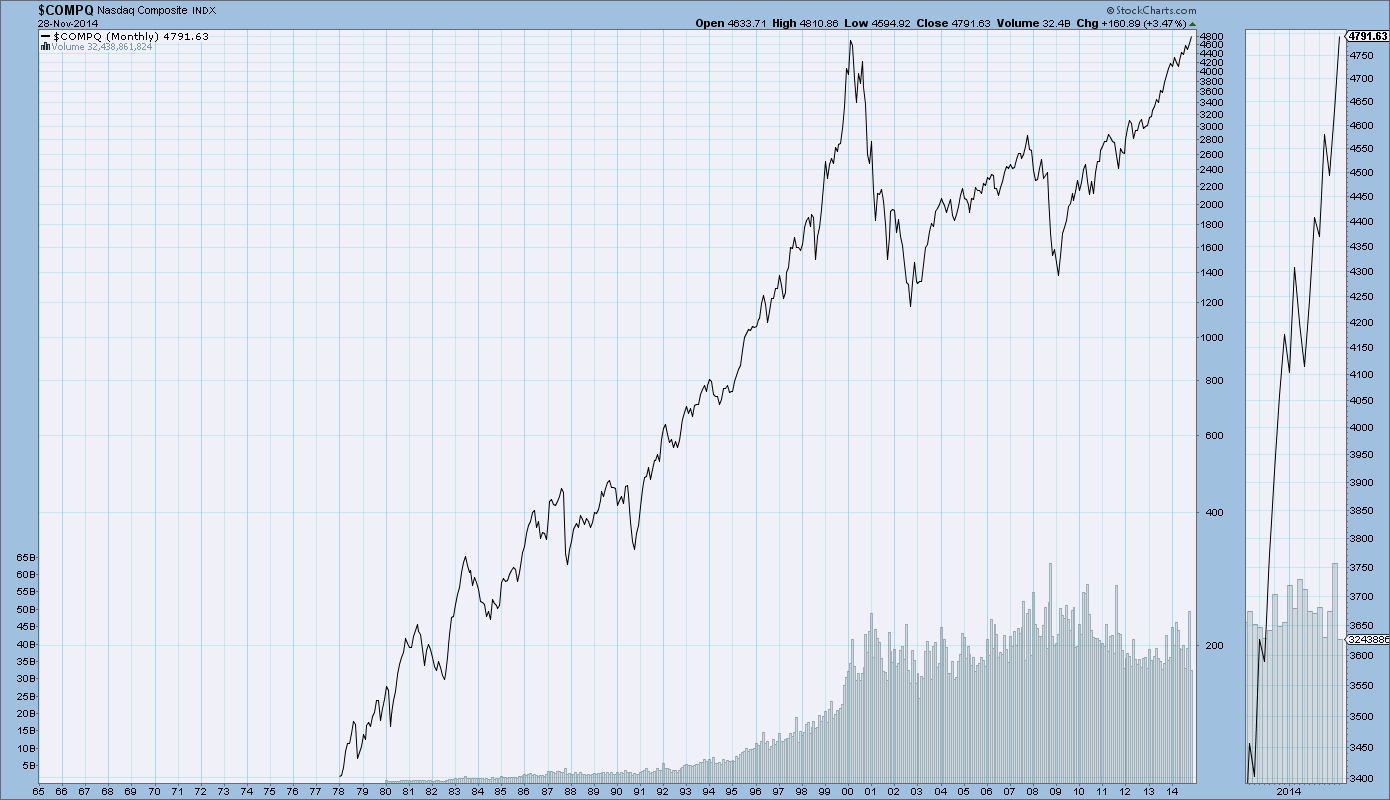
The Nasdaq Composite, from 1978-November 28, 2014:
Nasdaq Composite 1978-November 2014
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 2053.44 as this post is written
Monday, December 1, 2014

U.S. Dollar Decline – December 1, 2014 Update

U.S. Dollar weakness is a foremost concern of mine.  As such, I have extensively written about it.  I am very concerned that the actions being taken to “improve” our economic situation will dramatically weaken the Dollar.  Should the Dollar substantially decline from here, as I expect, the negative consequences will far outweigh any benefits.  The negative impact of a substantial Dollar decline can’t be overstated, in my opinion.
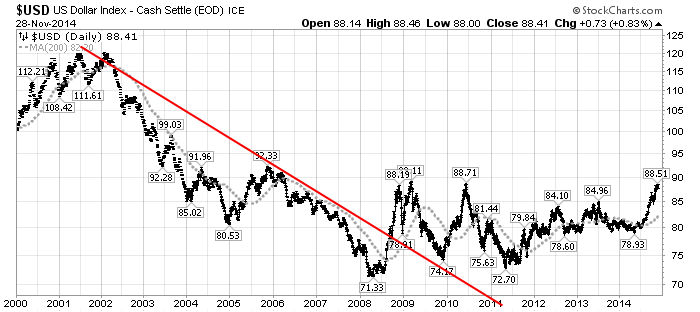
The following three charts illustrate various technical analysis aspects of the U.S. Dollar, as depicted by the U.S. Dollar Index.
First, a look at the monthly U.S. Dollar from 1983.  This clearly shows a long-term weakness, with the blue line showing technical support until 2007:
(charts courtesy of StockCharts.com; annotations by the author)
(click on charts to enlarge images)
U.S. Dollar monthly
–
Next, another chart, this one focused on the daily U.S. Dollar since 2000 on a LOG scale.  The red line represents a (past) trendline.  The gray dotted line is the 200-day M.A. (moving average):
U.S. Dollar daily
–
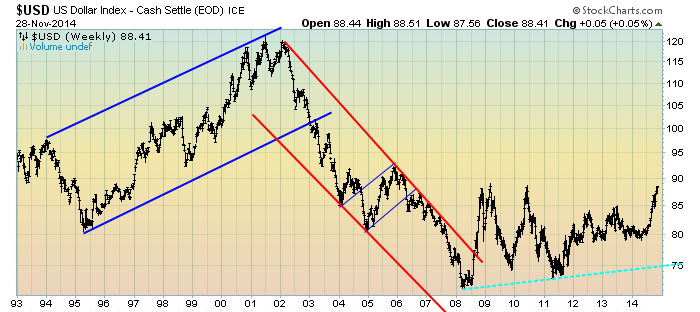
Lastly, a chart of the Dollar on a weekly LOG scale.  There are some clearly marked channels, with possible technical support depicted by the dashed light blue line:
U.S. Dollar weekly
–
I will continue providing updates on this U.S. Dollar situation regularly as it deserves very close monitoring…
_____
The Special Note summarizes my overall thoughts about our economic situation
SPX at 2067.56 as this post is written