“Stock market capitalization to GDP” is a notable and important metric regarding stock market valuation. In February of 2009 I wrote of it in “Does Warren Buffett’s Market Metric Still Apply?”
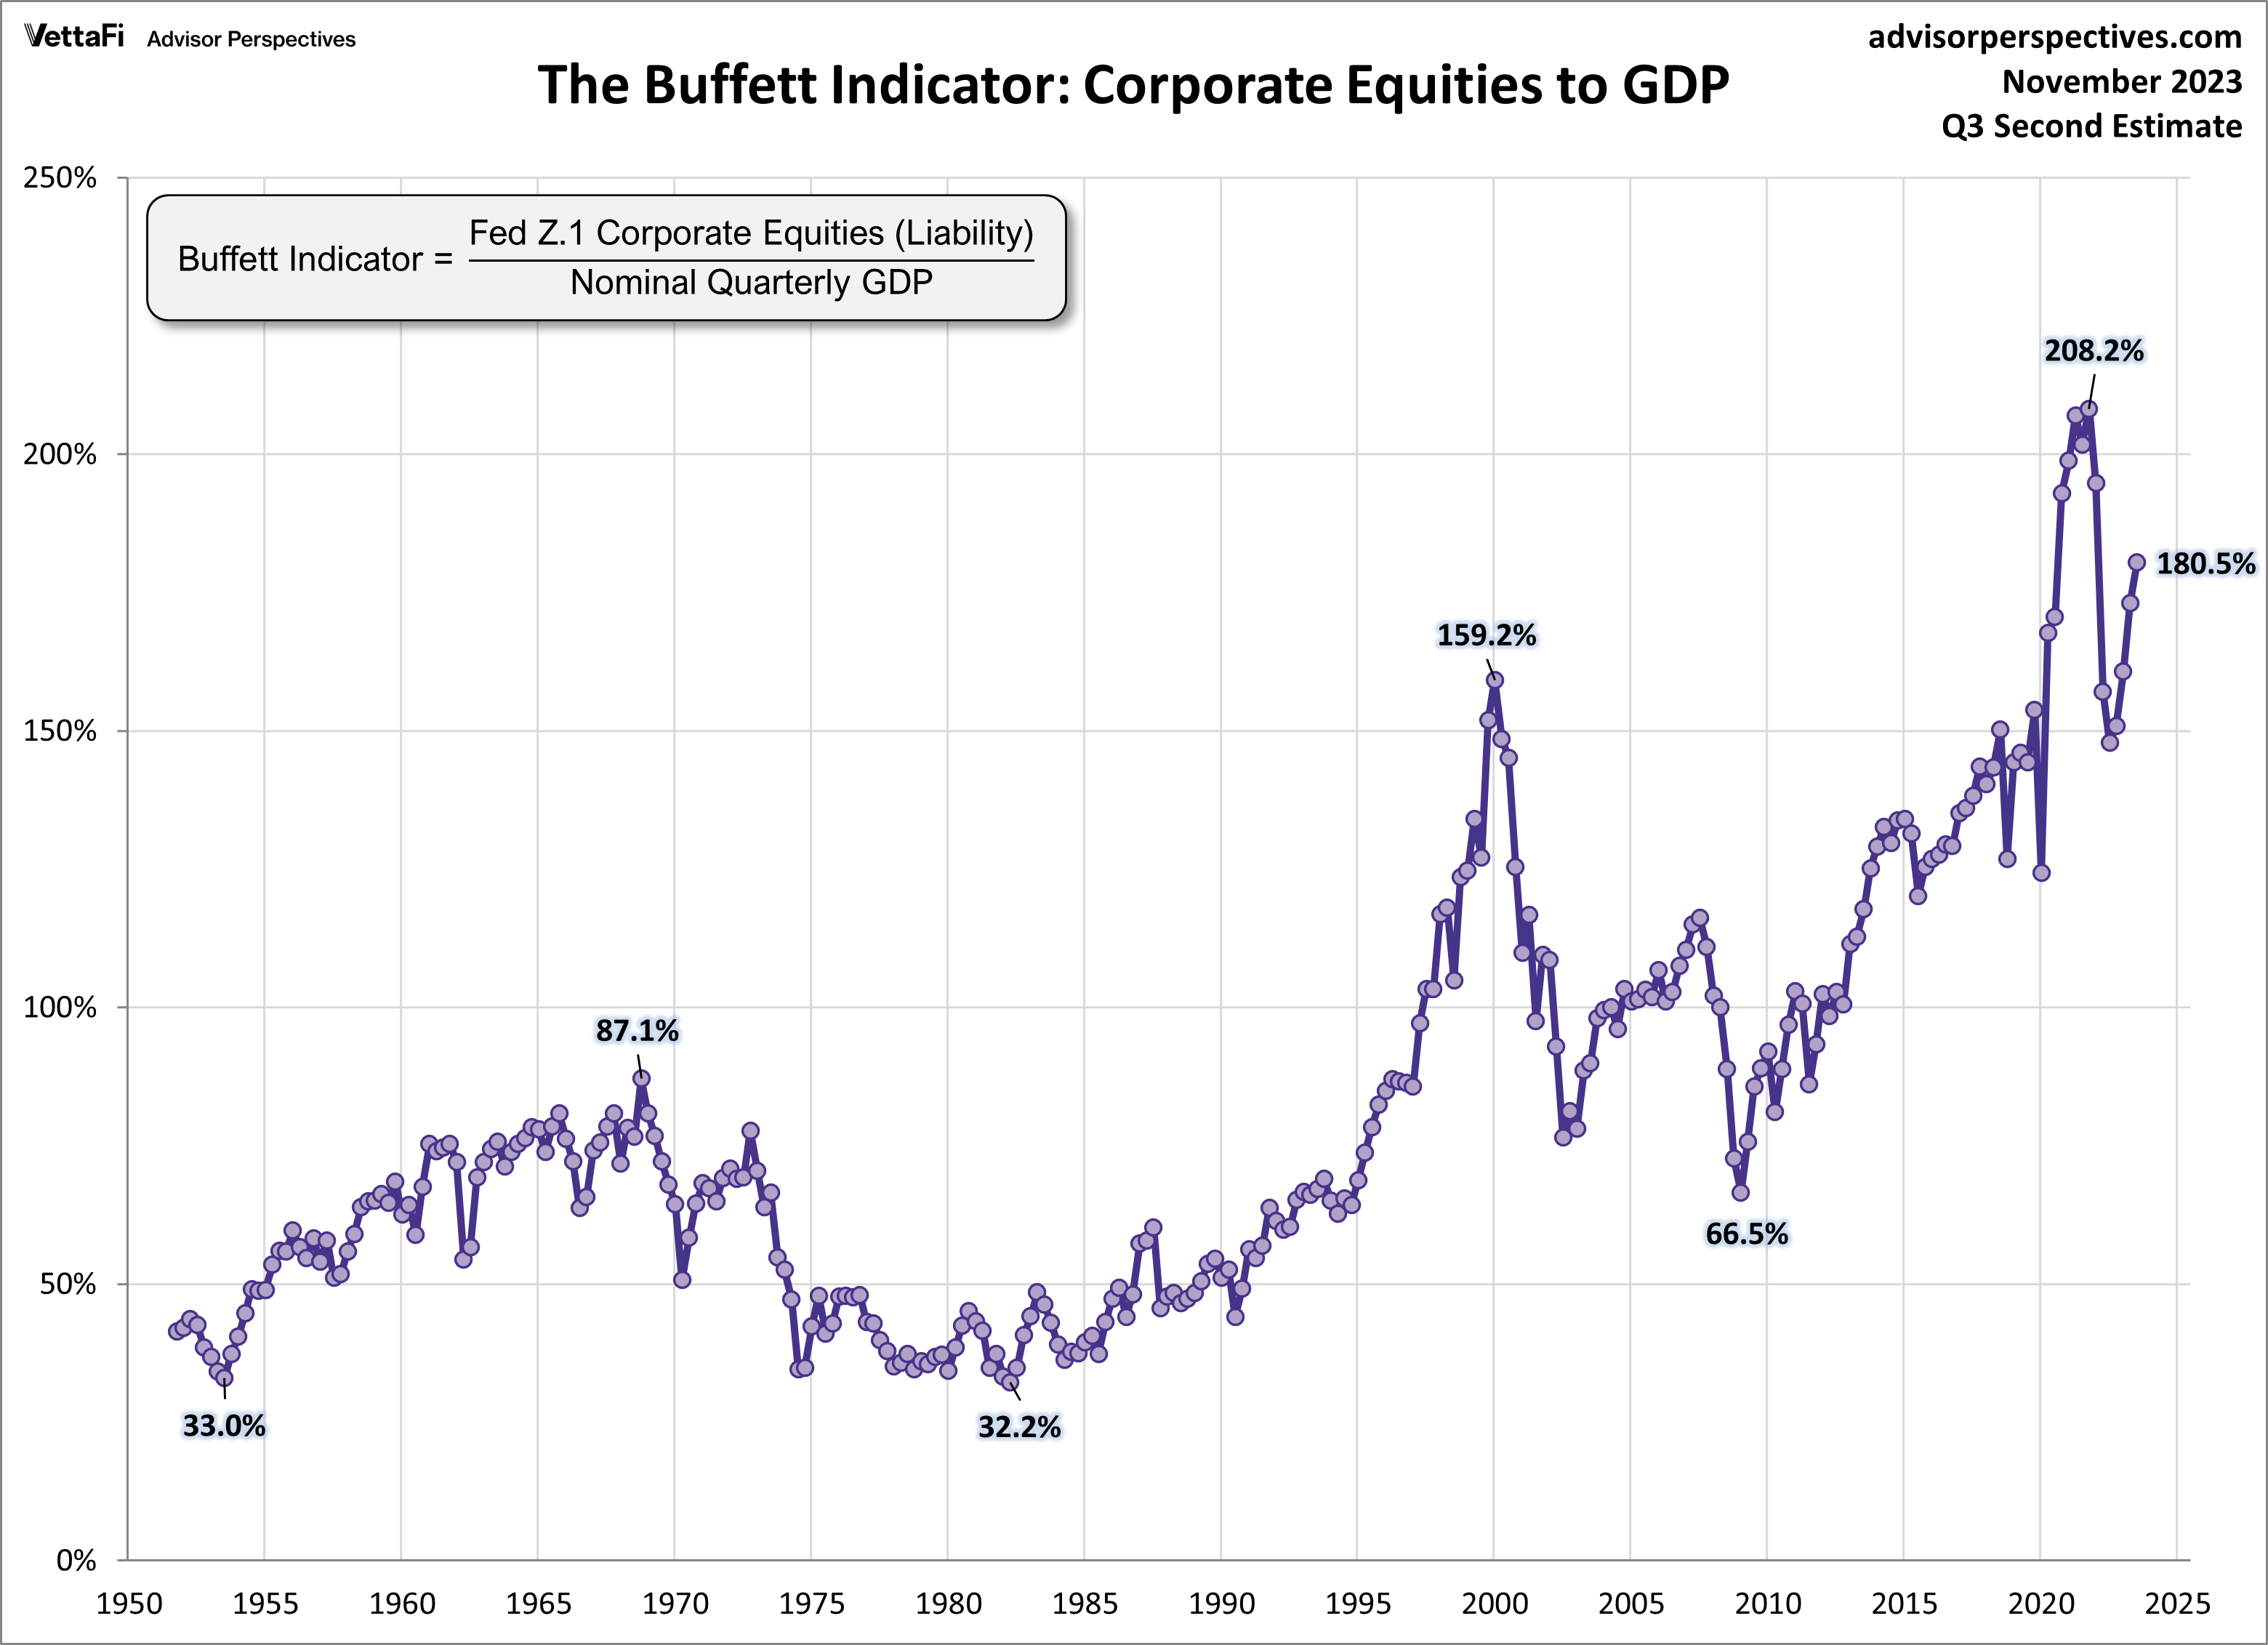
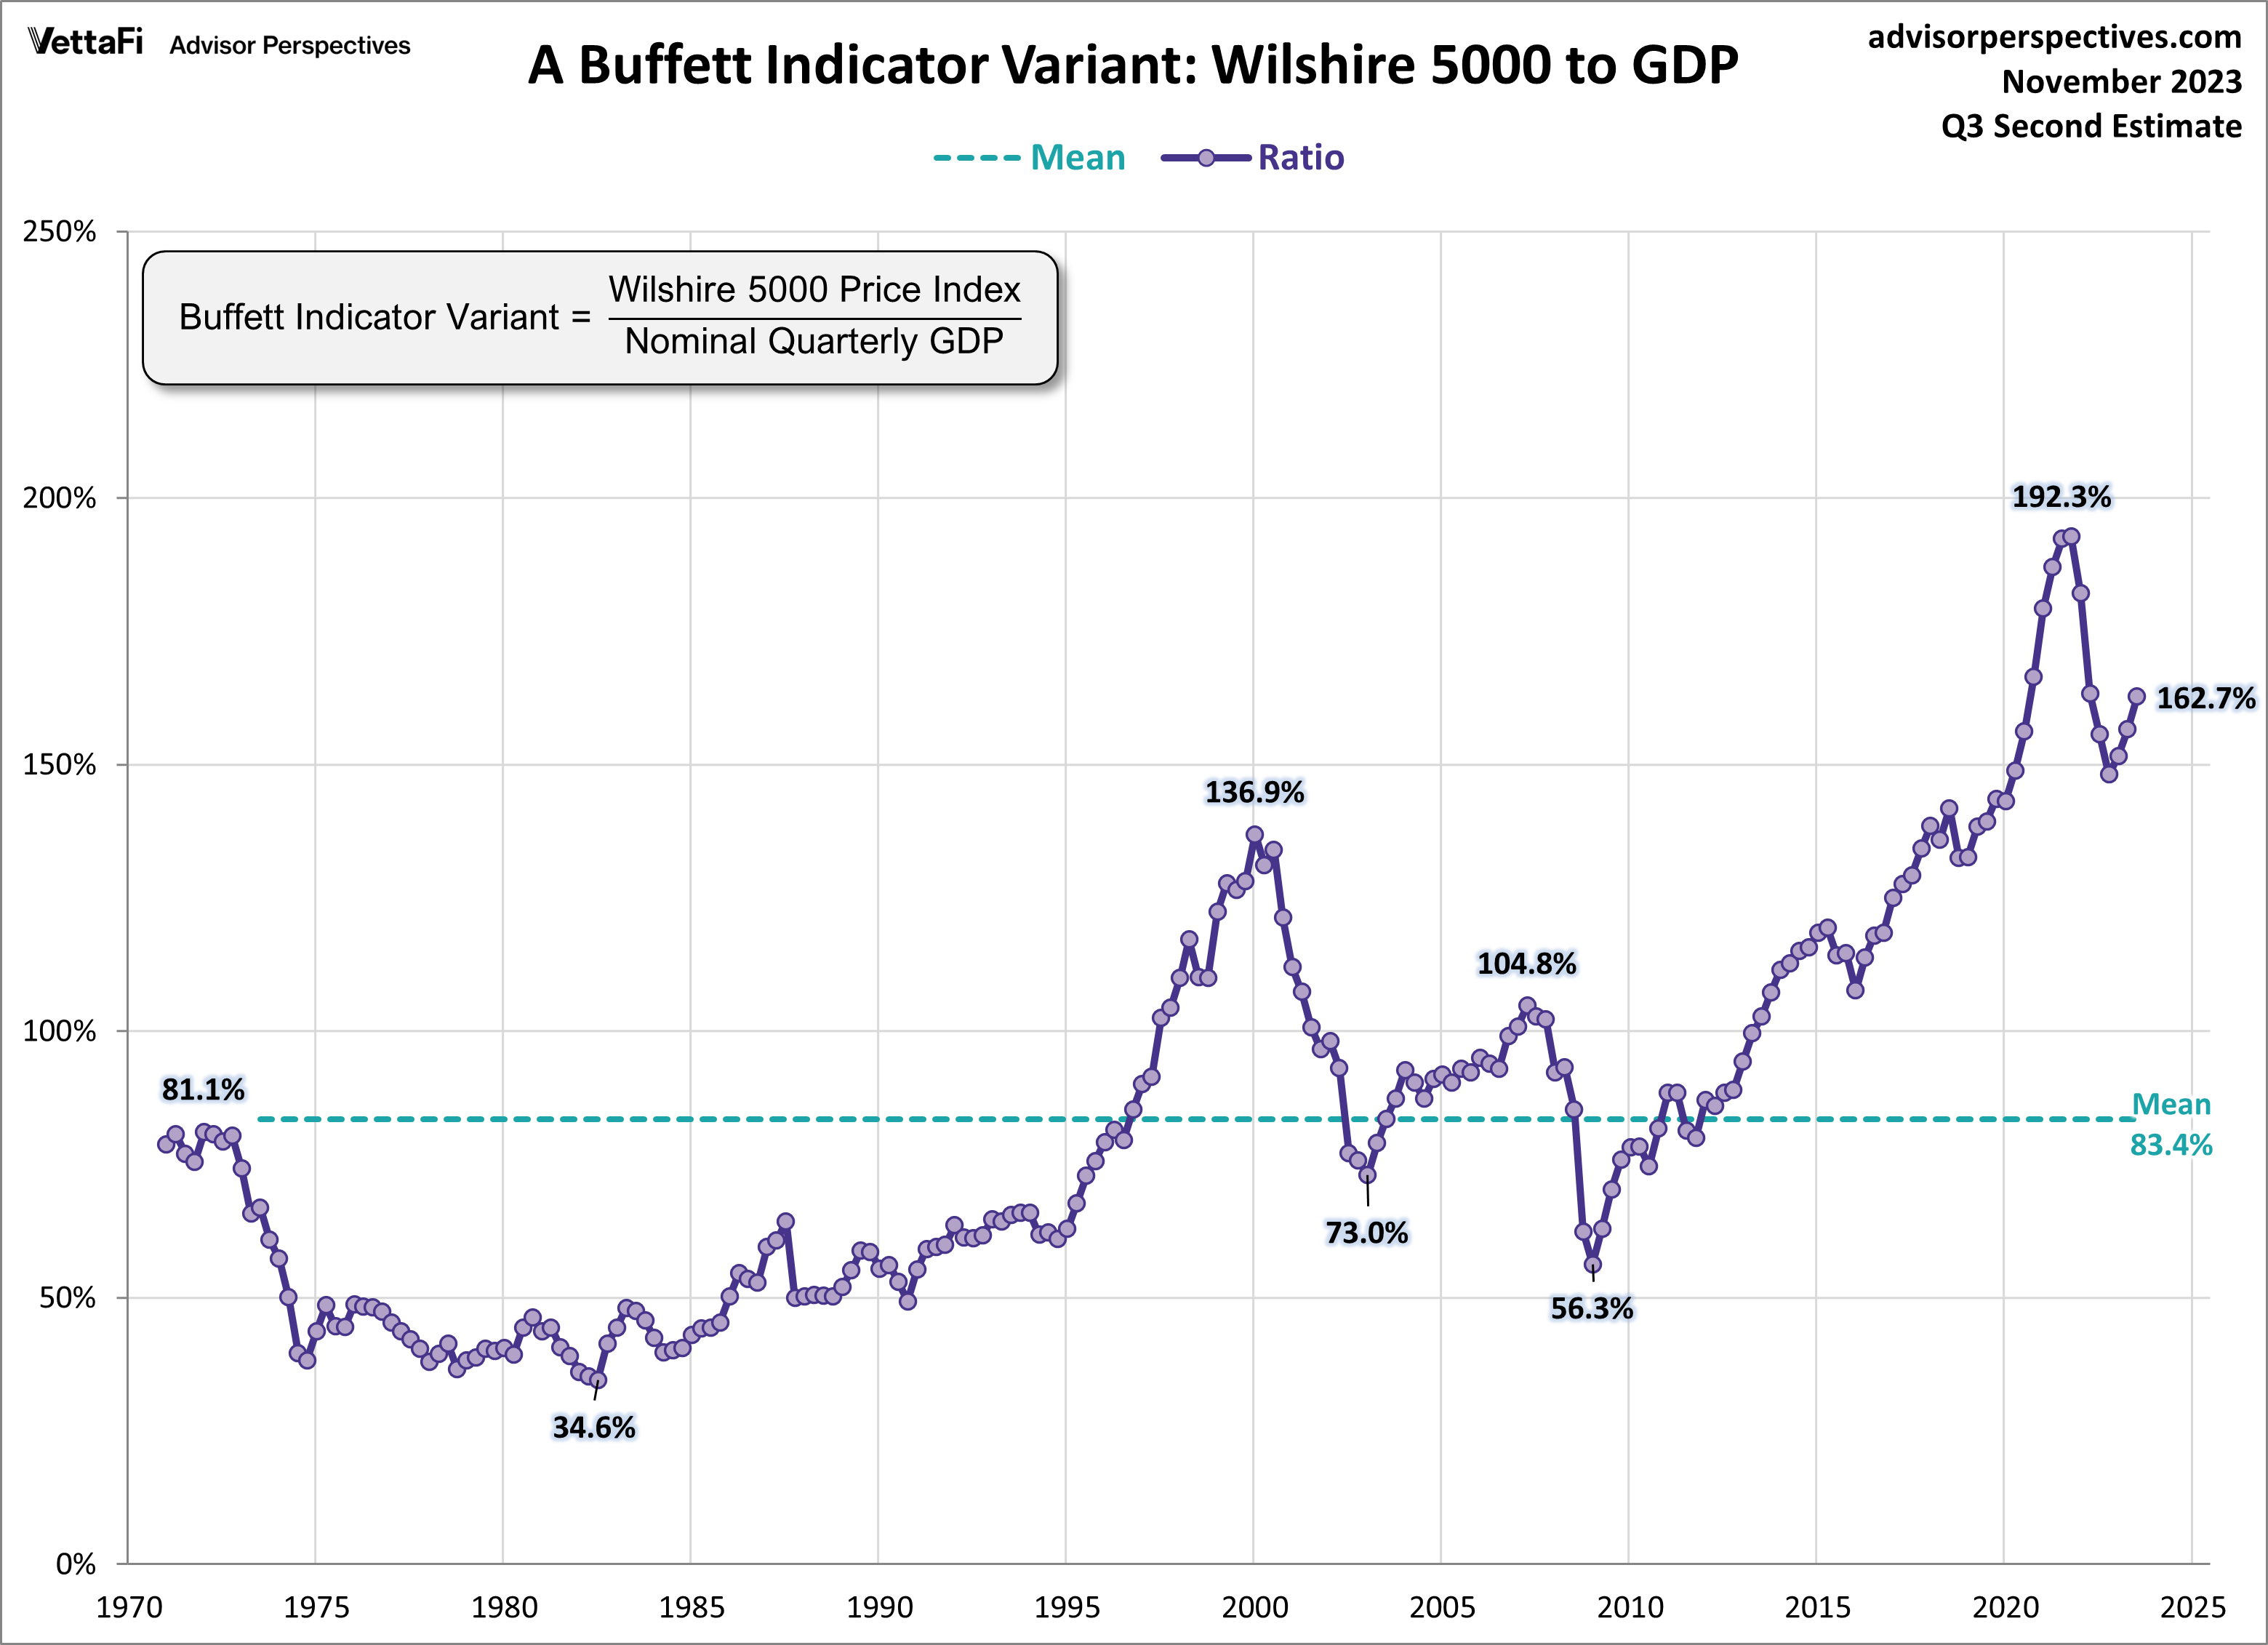
On the Advisor Perspectives’ site there is an update depicting this “stock market capitalization to GDP” metric.
As seen in the December 5, 2023 post titled “Buffett Valuation Indicator: November 2023 Update” two different versions are displayed, varying by the definition of stock market capitalization. (note: additional explanation is provided in the post.)
For reference purposes, here is the first chart, with the stock market capitalization as defined by the Federal Reserve:
(click on charts to enlarge images)
–
Here is the second chart, with the stock market capitalization as defined by the Wilshire 5000:
–
As one can see in both measures depicted above, “stock market capitalization to GDP” continues to be at notably high levels from a long-term historical perspective.
_____
The Special Note summarizes my overall thoughts about our economic situation
There are a variety of economic models that are supposed to predict the probabilities of recession.
While I don’t agree with the methodologies employed or probabilities of impending economic weakness as depicted by the following two models, I think the results of these models should be monitored.
Please note that each of these models is updated regularly, and the results of these – as well as other recession models – can fluctuate significantly.
Currently (last updated December 4, 2023 using data through November 2023) this “Yield Curve” model shows a 51.8387% probability of a recession in the United States twelve months ahead. For comparison purposes, it showed a 46.111% probability through October 2023, and a chart going back to 1960 is seen at the “Probability Of U.S. Recession Predicted by Treasury Spread.” (pdf)
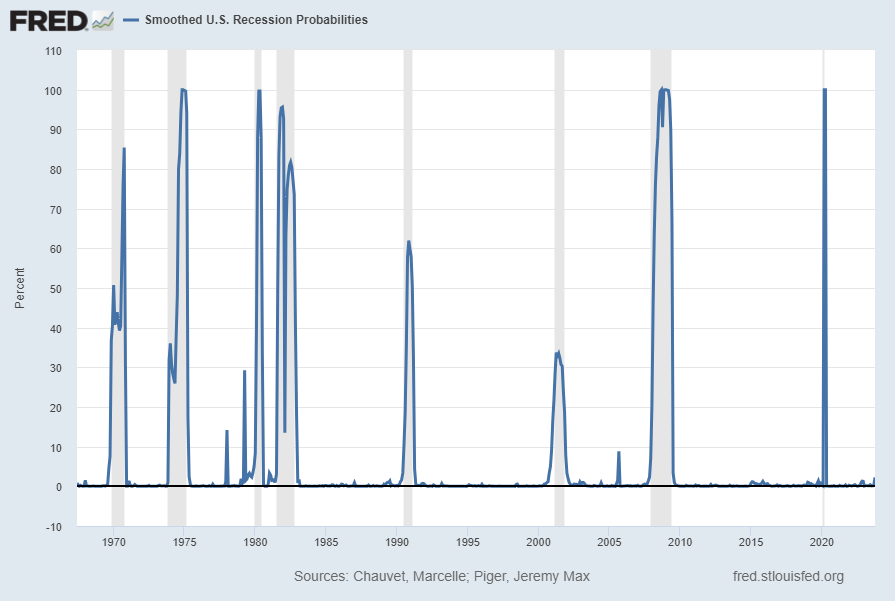
Smoothed recession probabilities for the United States are obtained from a dynamic-factor markov-switching model applied to four monthly coincident variables: non-farm payroll employment, the index of industrial production, real personal income excluding transfer payments, and real manufacturing and trade sales. This model was originally developed in Chauvet, M., “An Economic Characterization of Business Cycle Dynamics with Factor Structure and Regime Switching,” International Economic Review, 1998, 39, 969-996. (http://faculty.ucr.edu/~chauvet/ier.pdf)
This model, last updated on December 1, 2023 currently shows a 2.22% probability using data through October 2023.
Here is the FRED chart:
Data Source: Piger, Jeremy Max and Chauvet, Marcelle, Smoothed U.S. Recession Probabilities [RECPROUSM156N], retrieved from FRED, Federal Reserve Bank of St. Louis, accessed December 5, 2023: http://research.stlouisfed.org/fred2/series/RECPROUSM156N
–
The two models featured above can be compared against measures seen in recent posts. For instance, as seen in the October 15, 2023 post titled “The October 2023 Wall Street Journal Economic Forecast Survey“ economists surveyed averaged a 48% probability of a U.S. recession within the next 12 months.
_____
The Special Note summarizes my overall thoughts about our economic situation
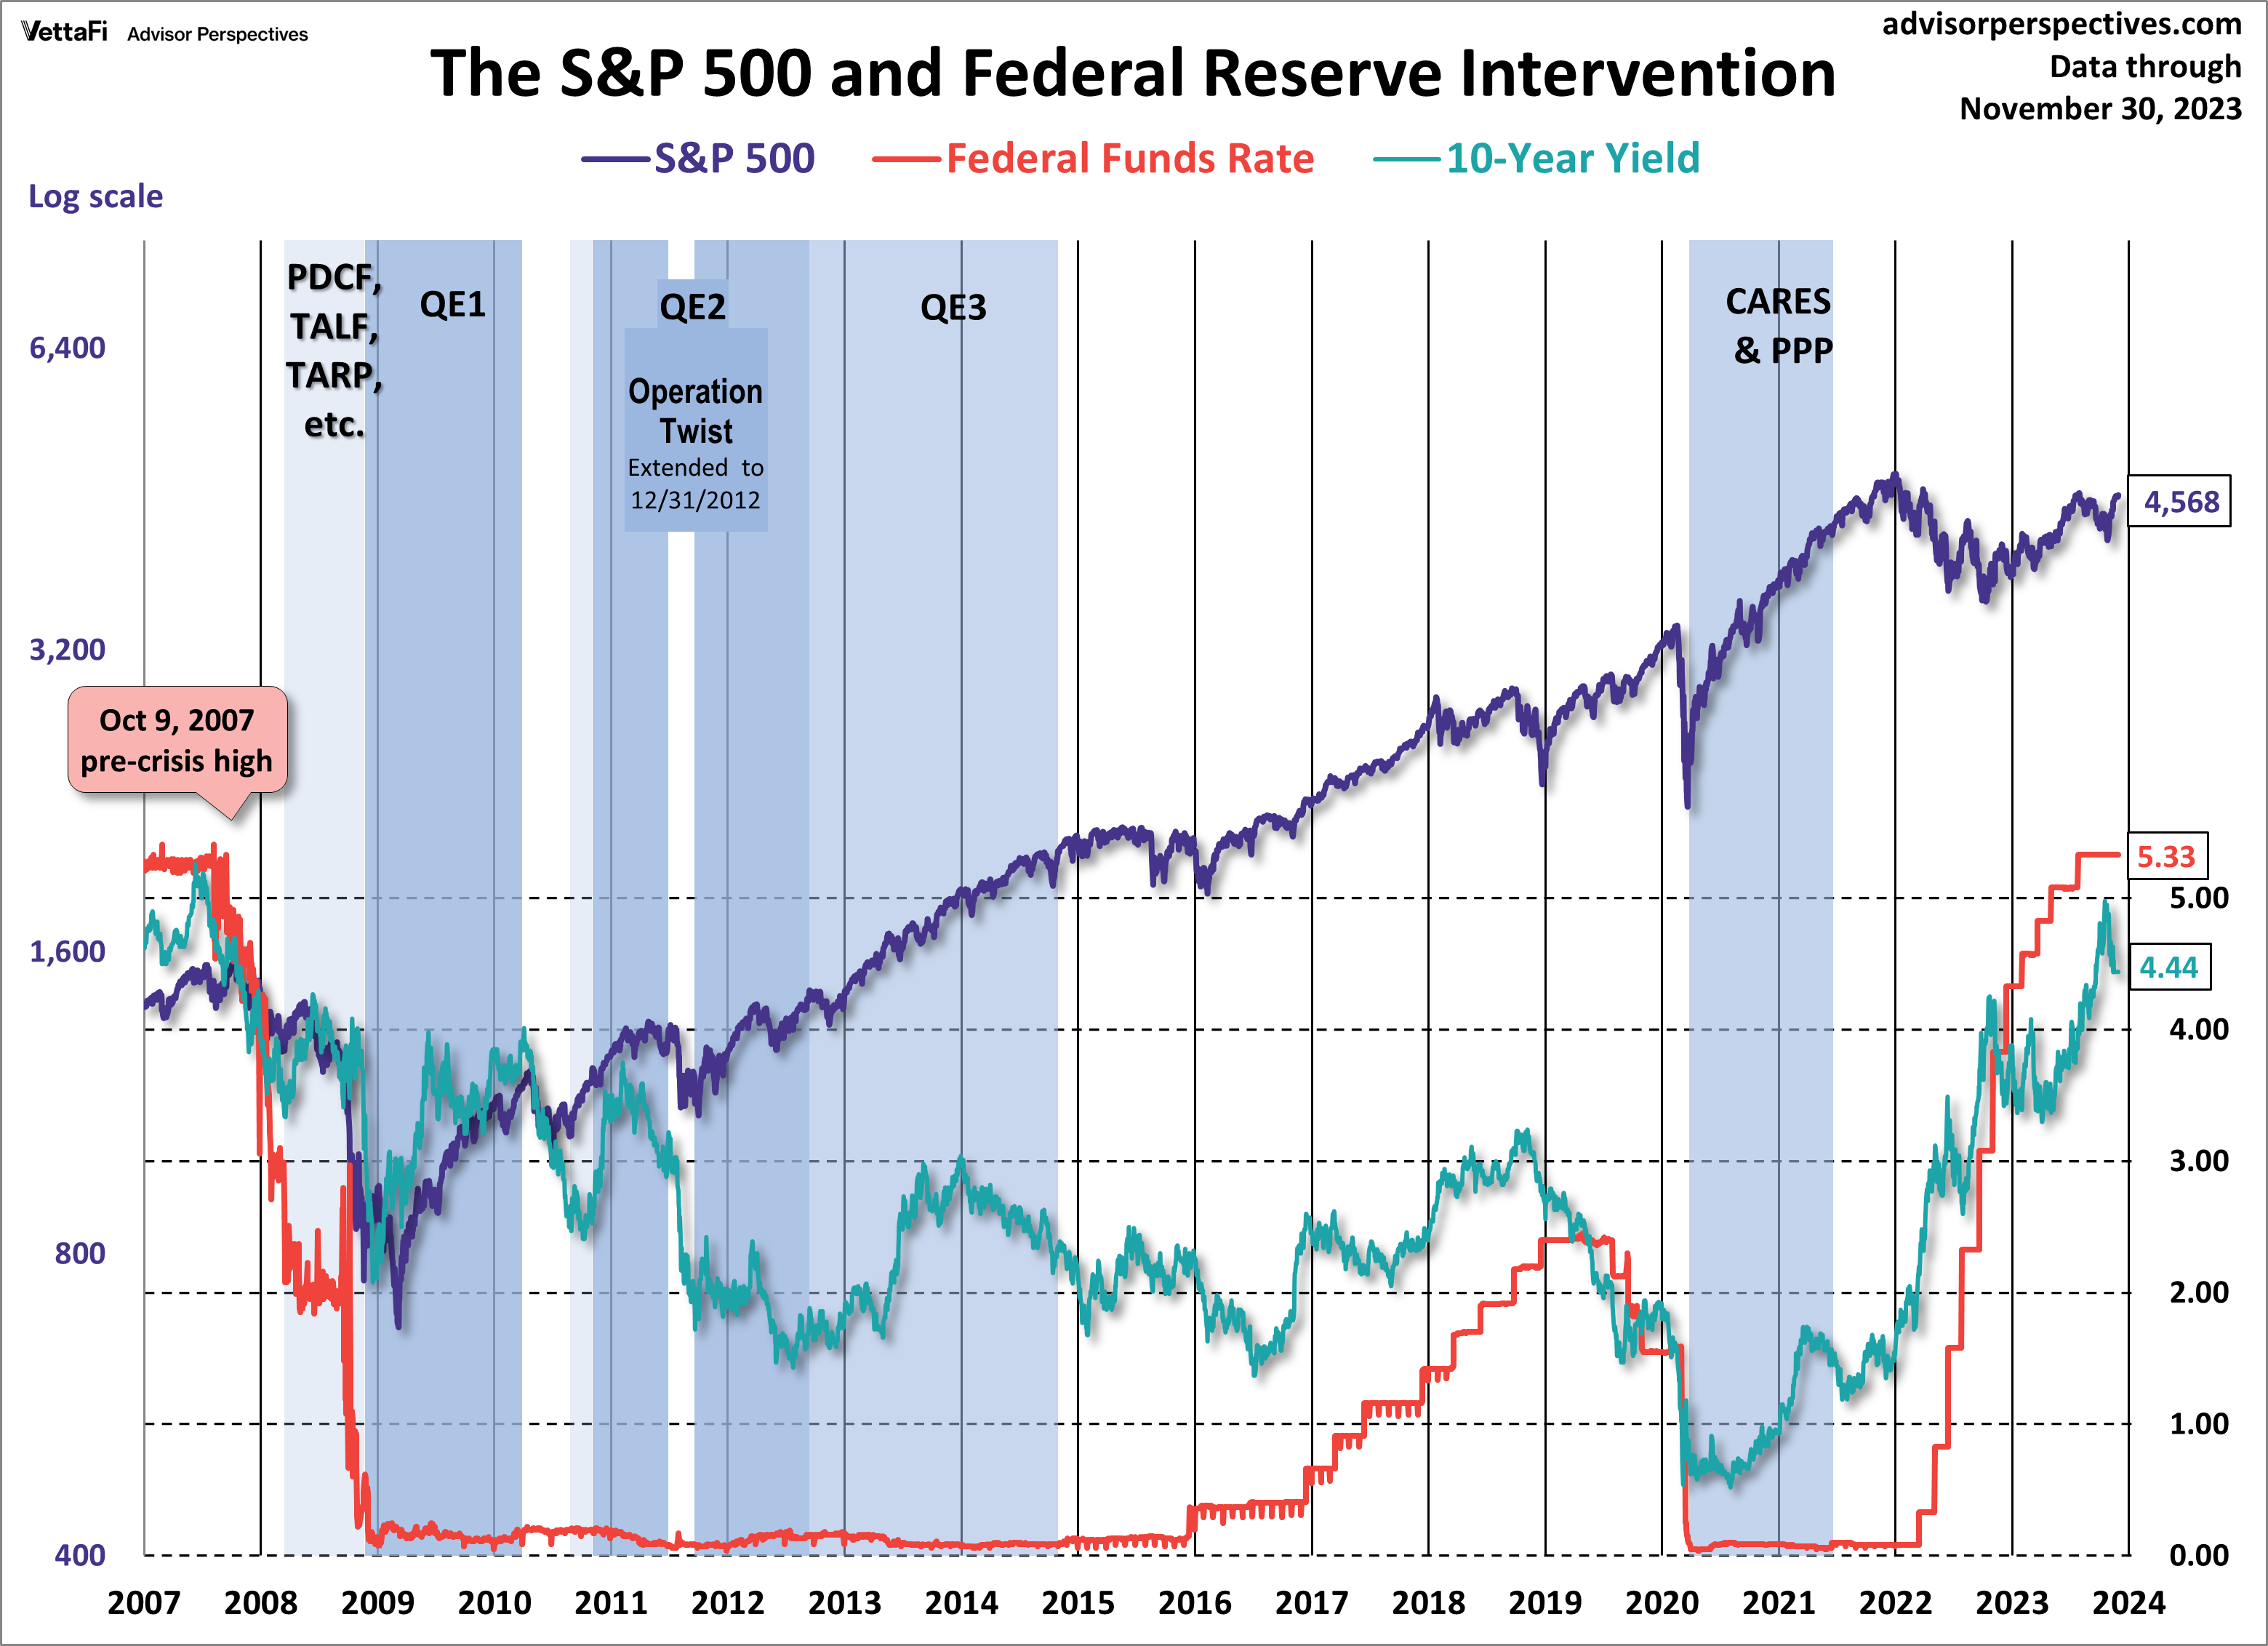
In the August 9, 2011 post (“QE3 – Various Thoughts“) I posted a chart that depicted the movements of the S&P500, 10-Year Treasury Yield and the Fed Funds rate spanning the periods of various Federal Reserve interventions since 2007.
For reference purposes, here is an updated chart (through November 30, 2023) from the Advisor Perspectives’ site post of December 1, 2023 (“Treasury Yields: A Long-Term Perspective“):
_____
The Special Note summarizes my overall thoughts about our economic situation
Below are those two charts, updated through the latest daily closing price.
The first is a daily chart of the S&P500 (shown in green), as well as five prominent (AAPL, IBM, AMZN, SBUX, CAT) individual stocks, since 2005. There is a blue vertical line that is very close to the March 6, 2009 low. As one can see, both the S&P500 performance, as well as many stocks including the five shown, have performed strongly since the March 6, 2009 low:
(click on chart to enlarge image)(chart courtesy of StockCharts.com; chart creation and annotation by the author)
–
This next chart shows, on a monthly LOG basis, the S&P500 since 1980. I find this chart notable as it provides an interesting long-term perspective on the S&P500′s performance. The 20, 50, and 200-month moving averages are shown in blue, red, and green lines, respectively:
(click on chart to enlarge image)(chart courtesy of StockCharts.com; chart creation and annotation by the author)
_____
The Special Note summarizes my overall thoughts about our economic situation
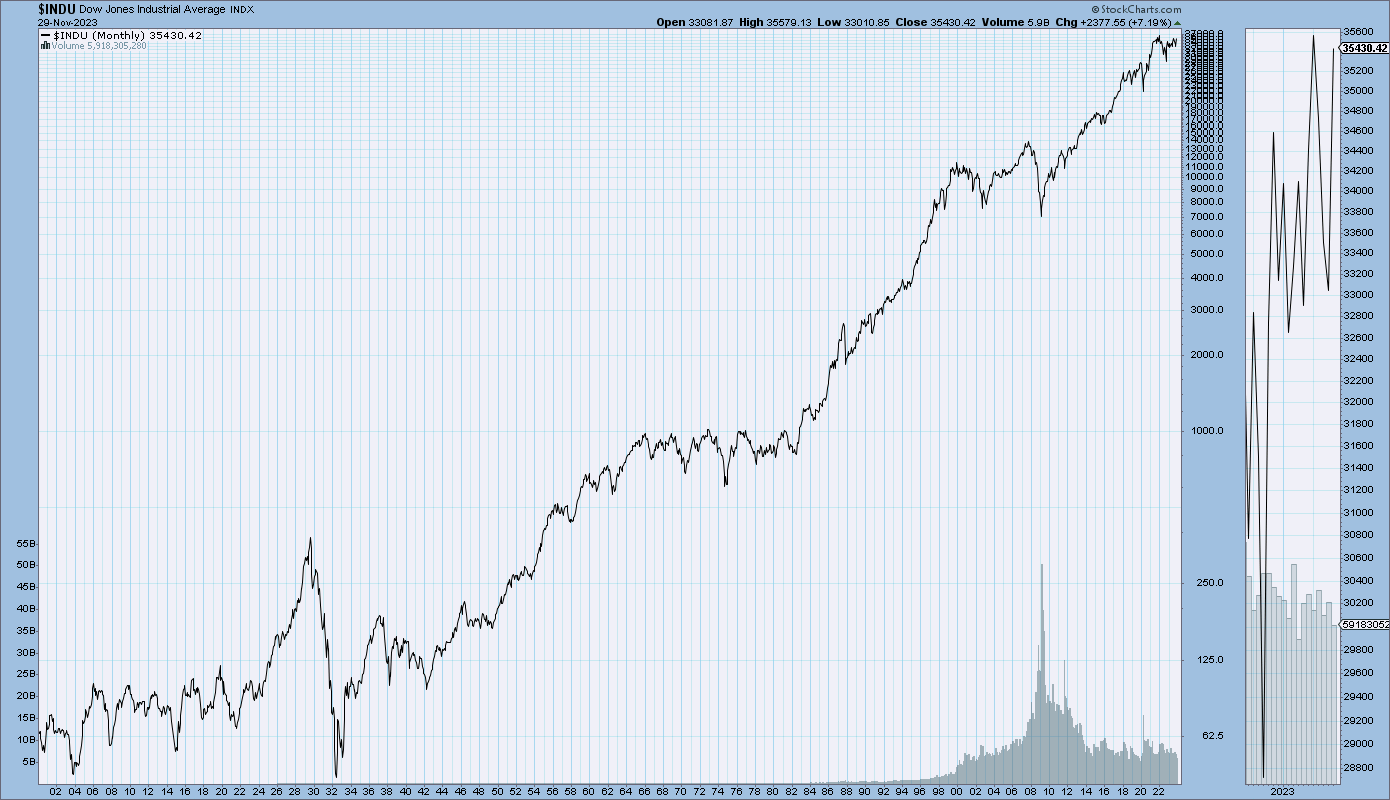
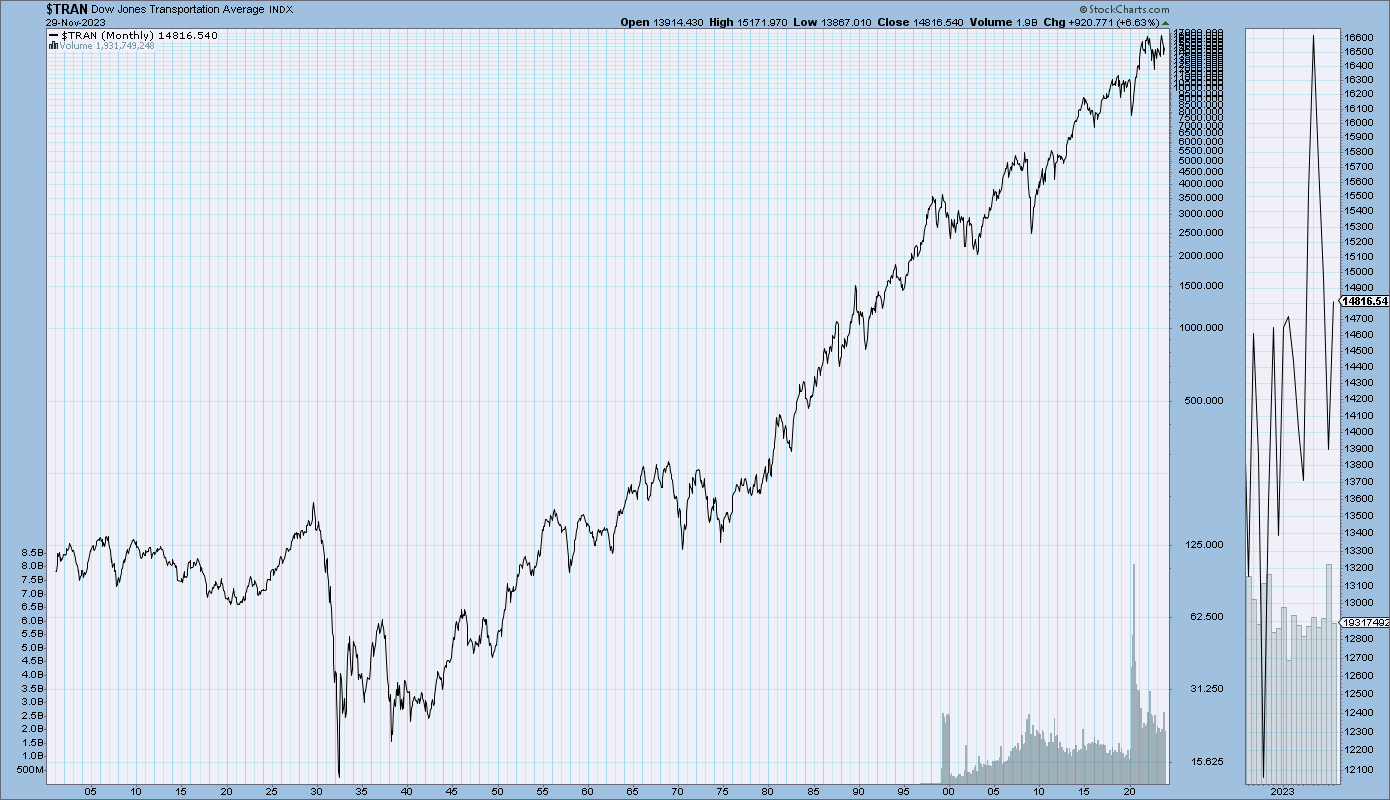
StockCharts.com maintains long-term historical charts of various major stock market indices, interest rates, currencies, commodities, and economic indicators.
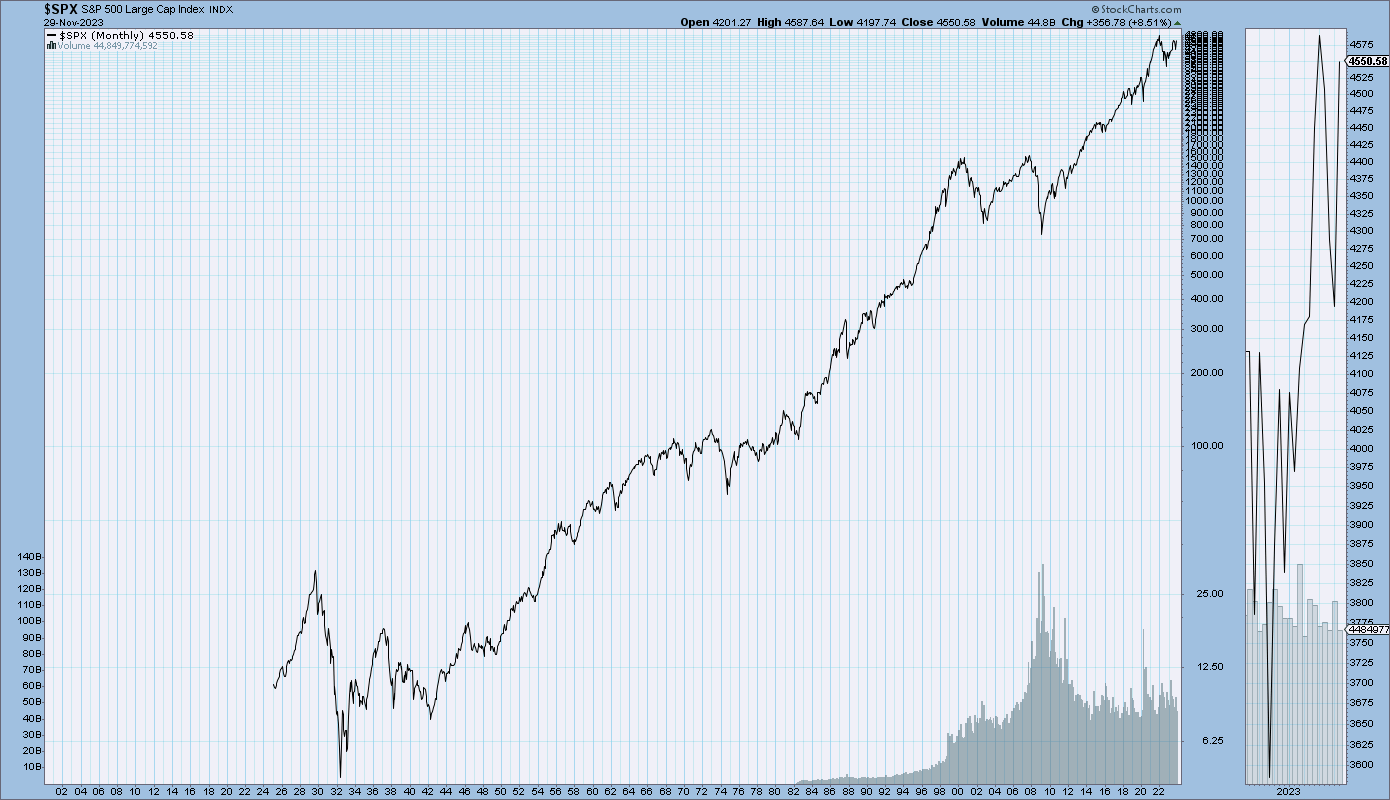
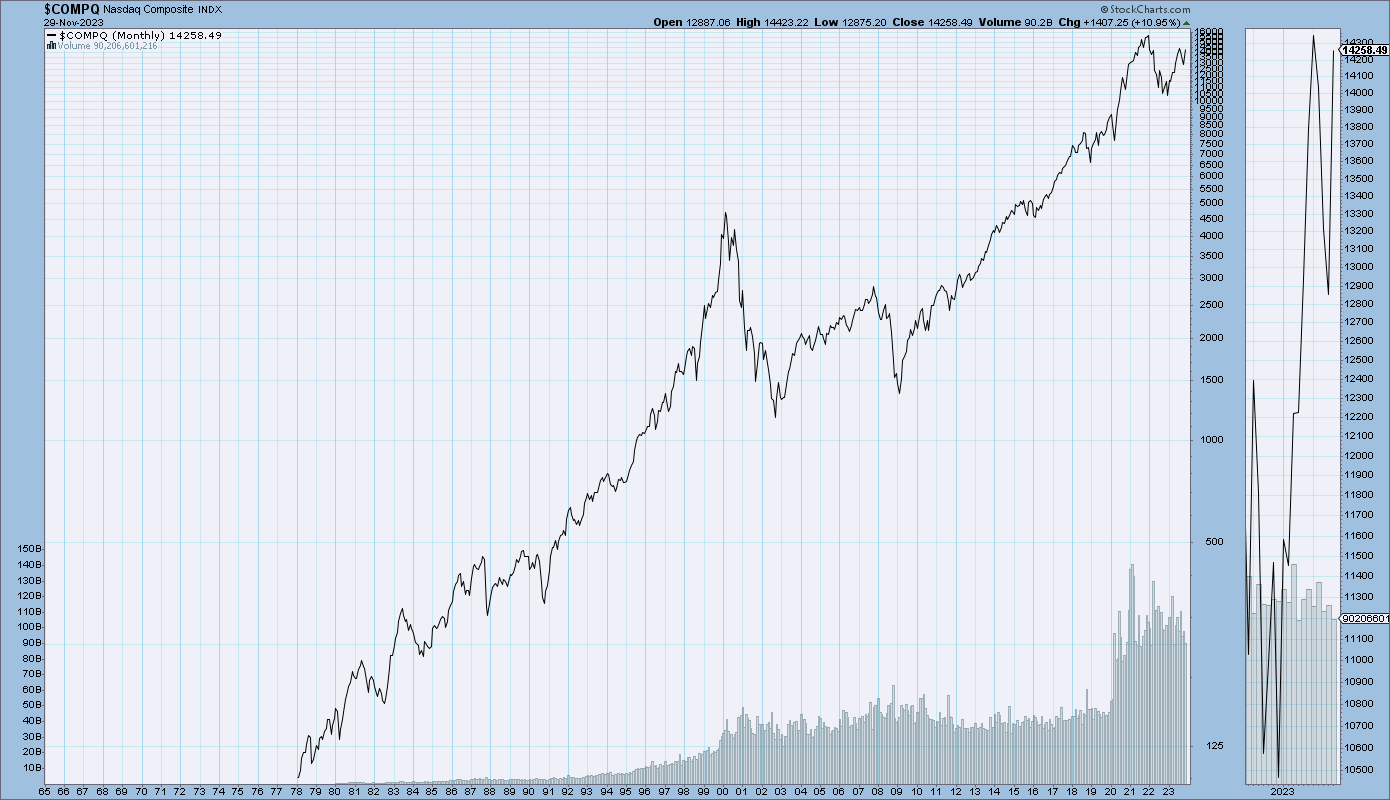
As a long-term reference, below are charts depicting various stock market indices for the dates shown. All charts are depicted on a monthly basis using a LOG scale.
(click on charts to enlarge images)(charts courtesy of StockCharts.com)
The Dow Jones Industrial Average, from 1900 – November 29, 2023:
–
The Dow Jones Transportation Average, from 1900 – November 29, 2023:
–
The S&P500, from 1925 – November 29, 2023:
–
The Nasdaq Composite, from 1978 – November 29, 2023:
_____
The Special Note summarizes my overall thoughts about our economic situation
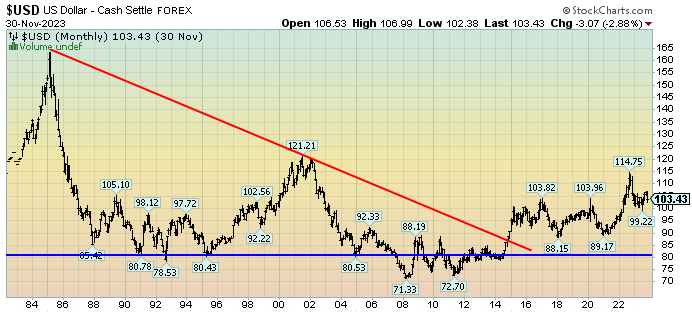
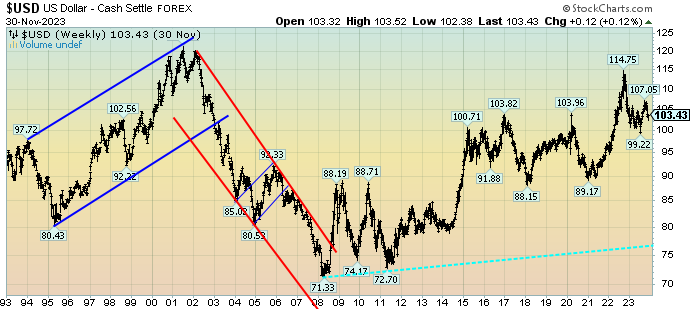
U.S. Dollar weakness is a foremost concern of mine. As such, I have extensively written about it, including commentary on the “A Substantial U.S. Dollar Decline And Consequences” page. I am very concerned that the actions being taken to “improve” our economic situation will dramatically weaken the Dollar. Should the Dollar substantially decline from here, as I expect, the negative consequences will far outweigh any benefits. The negative impact of a substantial Dollar decline can’t, in my opinion, be overstated.
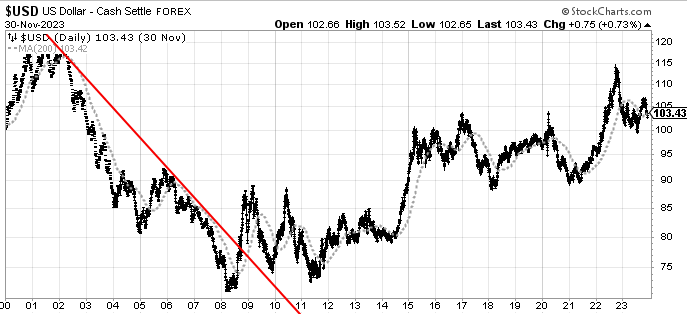
The following three charts illustrate various technical analysis aspects of the U.S. Dollar, as depicted by the U.S. Dollar Index.
First, a look at the monthly U.S. Dollar from 1983. This clearly shows a long-term weakness, with the blue line showing technical support until 2007, and the red line representing a (past) trendline:
(charts courtesy of StockCharts.com; annotations by the author)
(click on charts to enlarge images)
–
Next, another chart, this one focused on the daily U.S. Dollar since 2000 on a LOG scale. The red line represents a (past) trendline. The gray dotted line is the 200-day M.A. (moving average):
–
Lastly, a chart of the Dollar on a weekly LOG scale. There are two clearly marked past channels, with possible technical support depicted by the dashed light blue line:
–
I will continue providing updates on this U.S. Dollar situation regularly as it deserves very close monitoring…
_____
The Special Note summarizes my overall thoughts about our economic situation
Various surveys, economic growth projections, and market risk indicators indicate sustained economic growth and financial stability for the foreseeable future.
However, there are various indications – many of which have been discussed on this site – that this very widely-held consensus is in many ways incorrect. There are many exceedingly problematical financial conditions that have existed prior to 2020, and continue to exist. As well, numerous economic dynamics continue to be exceedingly worrisome and many economic indicators have portrayed facets of weak growth or outright decline currently as well as prior to 2020.
Of paramount importance is the resulting level of risk and the future economic implications.
From an “all things considered” standpoint, I continue to believe the overall level of risk remains at a fantastic level – one that is far greater than that experienced at any time in the history of the United States.
Cumulatively, these highly problematical conditions will lead to future upheaval. The extent of the resolution of these problematical conditions will determine the ongoing viability of the financial system and economy as well as the resultant quality of living.
My analyses continues to indicate that the growing level of financial danger will lead to the next stock market crash that will also involve (as seen in 2008) various other markets as well. Key attributes of this next crash is its outsized magnitude (when viewed from an ultra-long term historical perspective) and the resulting economic impact. This next financial crash is of tremendous concern, as my analyses indicate it will lead to a Super Depression – i.e. an economy characterized by deeply embedded, highly complex, and difficult-to-solve problems.
_____
The Special Note summarizes my overall thoughts about our economic situation