FactSet publishes a report titled “Earnings Insight” that contains a variety of information including the trends and expectations of S&P500 earnings.
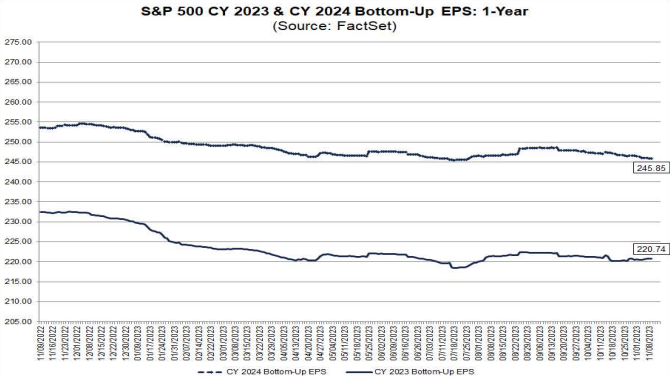
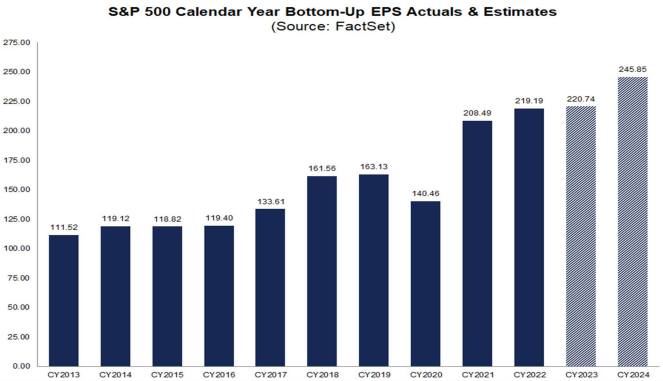
For reference purposes, here are two charts as seen in the “Earnings Insight” report of November 10, 2023:
from page 29:
(click on charts to enlarge images)
from page 30:
_____
I post various economic forecasts because I believe they should be carefully monitored. However, as those familiar with this site are aware, I do not agree with many of the consensus estimates and much of the commentary in these forecast surveys.
_____
The Special Note summarizes my overall thoughts about our economic situation
As many are aware, Refinitiv publishes earnings estimates for the S&P500. (My other posts concerning S&P earnings estimates can be found under the S&P500 Earnings label)
The following estimates are from Exhibit 24 of the “S&P500 Earnings Scorecard” (pdf) of November 10, 2023, and represent an aggregation of individual S&P500 component “bottom up” analyst forecasts. For reference, the Year 2014 value is $118.78/share; the Year 2015 value is $117.46/share; the Year 2016 value is $118.10/share; the Year 2017 value is $132.00/share; the Year 2018 value is $161.93/share; the Year 2019 value is $162.93/share; the Year 2020 value is $139.72/share; the year 2021 value is $208.12/share; and the year 2022 value is $218.09/share:
Year 2023 estimate:
$220.62/share
Year 2024 estimate:
$245.31/share
Year 2025 estimate:
$275.12/share
_____
I post various economic forecasts because I believe they should be carefully monitored. However, as those familiar with this site are aware, I do not agree with many of the consensus estimates and much of the commentary in these forecast surveys.
_____
The Special Note summarizes my overall thoughts about our economic situation
As many are aware, Standard & Poor’s publishes earnings estimates for the S&P500. (My posts concerning their estimates can be found under the S&P500 Earnings label)
For reference purposes, the most current estimates are reflected below, and are as of November 8, 2023:
Year 2023 estimates add to the following:
-From a “bottom up” perspective, operating earnings of $215.17/share
-From a “bottom up” perspective, “as reported” earnings of $196.02/share
Year 2024 estimates add to the following:
-From a “bottom up” perspective, operating earnings of $243.32/share
-From a “bottom up” perspective, “as reported” earnings of $220.70/share
_____
I post various economic forecasts because I believe they should be carefully monitored. However, as those familiar with this site are aware, I do not agree with many of the consensus estimates and much of the commentary in these forecast surveys.
_____
The Special Note summarizes my overall thoughts about our economic situation
There are a variety of economic models that are supposed to predict the probabilities of recession.
While I don’t agree with the methodologies employed or probabilities of impending economic weakness as depicted by the following two models, I think the results of these models should be monitored.
Please note that each of these models is updated regularly, and the results of these – as well as other recession models – can fluctuate significantly.
Currently (last updated November 12, 2023 using data through October 2023) this “Yield Curve” model shows a 46.111% probability of a recession in the United States twelve months ahead. For comparison purposes, it showed a 56.1602% probability through September 2023, and a chart going back to 1960 is seen at the “Probability Of U.S. Recession Predicted by Treasury Spread.” (pdf)
Smoothed recession probabilities for the United States are obtained from a dynamic-factor markov-switching model applied to four monthly coincident variables: non-farm payroll employment, the index of industrial production, real personal income excluding transfer payments, and real manufacturing and trade sales. This model was originally developed in Chauvet, M., “An Economic Characterization of Business Cycle Dynamics with Factor Structure and Regime Switching,” International Economic Review, 1998, 39, 969-996. (http://faculty.ucr.edu/~chauvet/ier.pdf)
This model, last updated on November 1, 2023 currently shows a .14% probability using data through September 2023.
Here is the FRED chart:
Data Source: Piger, Jeremy Max and Chauvet, Marcelle, Smoothed U.S. Recession Probabilities [RECPROUSM156N], retrieved from FRED, Federal Reserve Bank of St. Louis, accessed November 13, 2023: http://research.stlouisfed.org/fred2/series/RECPROUSM156N
–
The two models featured above can be compared against measures seen in recent posts. For instance, as seen in the October 15, 2023 post titled “The October 2023 Wall Street Journal Economic Forecast Survey“ economists surveyed averaged a 48% probability of a U.S. recession within the next 12 months.
_____
The Special Note summarizes my overall thoughts about our economic situation
The survey shows, among many measures, the following median expectations:
Real GDP: (annual average level)
full-year 2023: 2.4%
full-year 2024: 1.7%
full-year 2025: 1.8%
full-year 2026: 2.1%
Unemployment Rate: (annual average level)
for 2023: 3.7%
for 2024: 4.1%
for 2025: 4.2%
for 2026: 4.0%
–
Regarding the risk of a negative quarter in real GDP in any of the next few quarters, mean estimates are 31.8%, 40.9%, 40.2%, 36.8%, and 34.7% for each of the quarters from Q4 2023 through Q4 2024, respectively.
As well, there are also a variety of time frames shown (present quarter through the year 2032) with the median expected inflation (annualized) of each. Inflation is measured in Headline and Core CPI and Headline and Core PCE. Over all time frames expectations are shown to be in the 2.1% to 3.9% range.
_____
I post various economic forecasts because I believe they should be carefully monitored. However, as those familiar with this site are aware, I do not agree with many of the consensus estimates and much of the commentary in these forecast surveys.
_____
The Special Note summarizes my overall thoughts about our economic situation
My overall analysis indicates a continuing elevated and growing level of financial danger which contains many worldwide and U.S.-specific “stresses” of a very complex nature. I have written numerous posts on this site concerning both ongoing and recent “negative developments.” These developments, as well as other exceedingly problematical conditions, have presented a highly perilous economic environment that endangers the overall financial system.
Also of ongoing immense importance is the existence of various immensely large asset bubbles, a subject of which I have extensively written. While all of these asset bubbles are wildly pernicious and will have profound adverse future implications, hazards presented by the bond market bubble are especially notable.
Predicting the specific timing and extent of a stock market crash is always difficult, and the immense complexity of today’s economic situation makes such a prediction even more challenging. With that being said, my analyses continue to indicate that a near-term exceedingly large (from an ultra long-term perspective) stock market crash – that would also involve (as seen in 2008) various other markets – will occur. [note: the “next crash” and its aftermath has paramount significance and implications, as discussed in the post of January 6, 2012 titled “The Next Crash And Its Significance“ and various subsequent posts in the “Economic Depression” label]
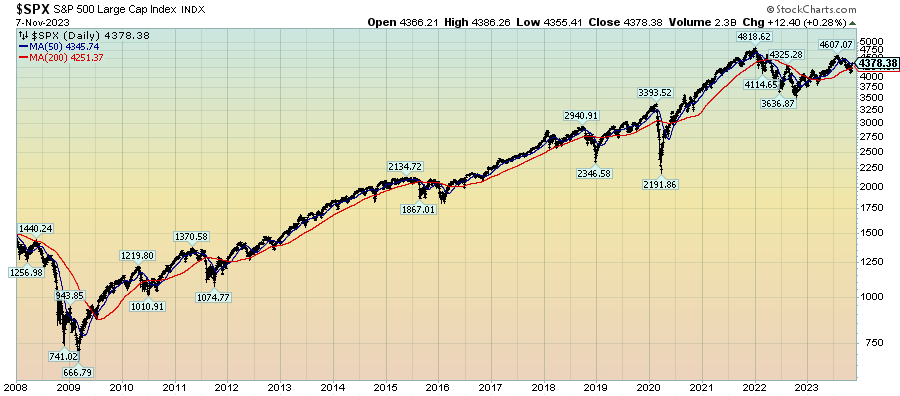
As reference, below is a daily chart since 2008 of the S&P500 (through November 7, 2023 with a last price of 4378.38), depicted on a LOG scale, indicating both the 50dma and 200dma as well as price labels:
(click on chart to enlarge image)(chart courtesy of StockCharts.com; chart creation and annotation by the author)
_____
The Special Note summarizes my overall thoughts about our economic situation
Throughout this site there are many discussions of economic indicators. This post is the latest in a series of posts indicating facets of U.S. economic weakness or a notably low growth rate.
The level and trend of economic growth is especially notable at this time. As seen in various sources, recession estimates have been at high levels.
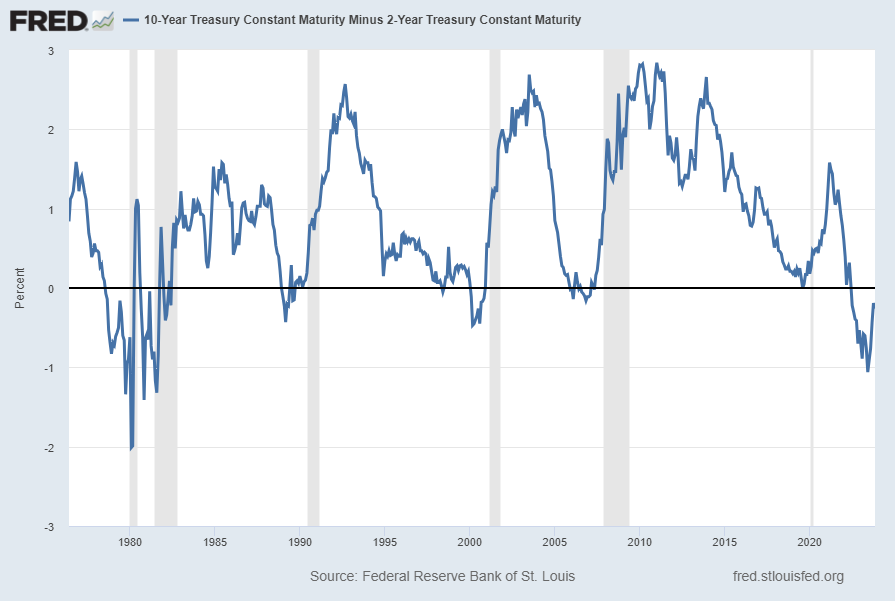
While I continue to have the stated reservations regarding the “Yield Curve” as an indicator, I do believe that it should be monitored.
The U.S. Yield Curve (one proxy seen below) is (all things considered) notably negative when viewed from a long-term perspective. Below is the spread between the 10-Year Treasury Constant Maturity and the 2-Year Treasury Constant Maturity from June 1976 through the November 3, 2023 update, showing a value of -.26% [10-Year Treasury Yield (FRED DGS10) of 4.67% as of the November 2 update, 2-Year Treasury Yield (FRED DGS2) of 4.98% as of the November 3 update]:
source: Federal Reserve Bank of St. Louis, 10-Year Treasury Constant Maturity Minus 2-Year Treasury Constant Maturity [T10Y2Y], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed November 6, 2023: https://fred.stlouisfed.org/series/T10Y2Y
__
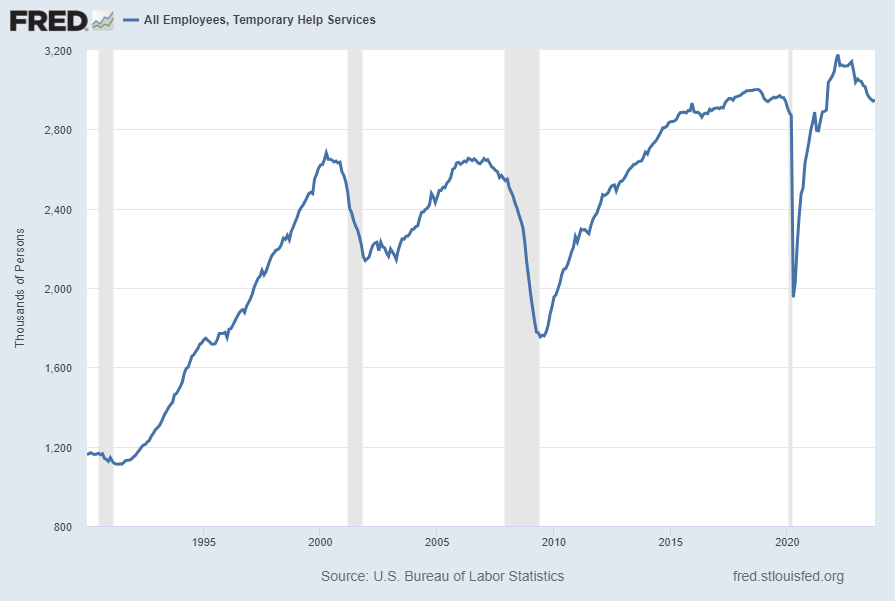
All Employees, Temporary Help Services (TEMPHELPS)
I have written extensively about many facets of employment and unemployment, as the current and future unemployment issue is of tremendous importance yet is in many ways misunderstood.
One theory regarding employment is that hiring cycles typically begin with an uptake in temporary employment. Conversely, due to various factors a reduction in temporary employees can be an (early) indicator of lessening labor demand.
Shown below is this measure with last value of 2,948.5 (Thousands) through October, last updated November 3, 2023:
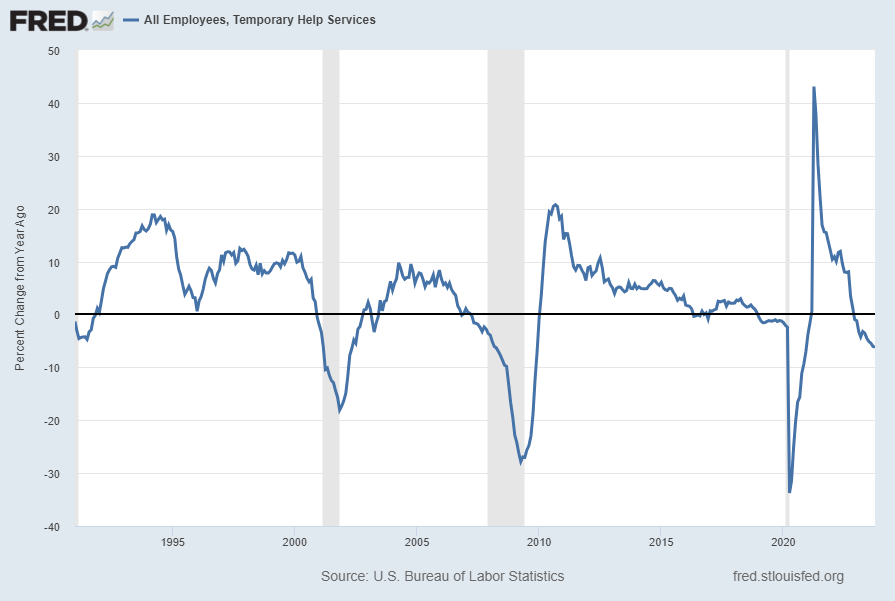
Below is this measure displayed on a “Percent Change From Year Ago” basis with value -6.1%:
source: U.S. Bureau of Labor Statistics, All Employees, Temporary Help Services [TEMPHELPS], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed November 3, 2023: https://fred.stlouisfed.org/series/TEMPHELPS
__
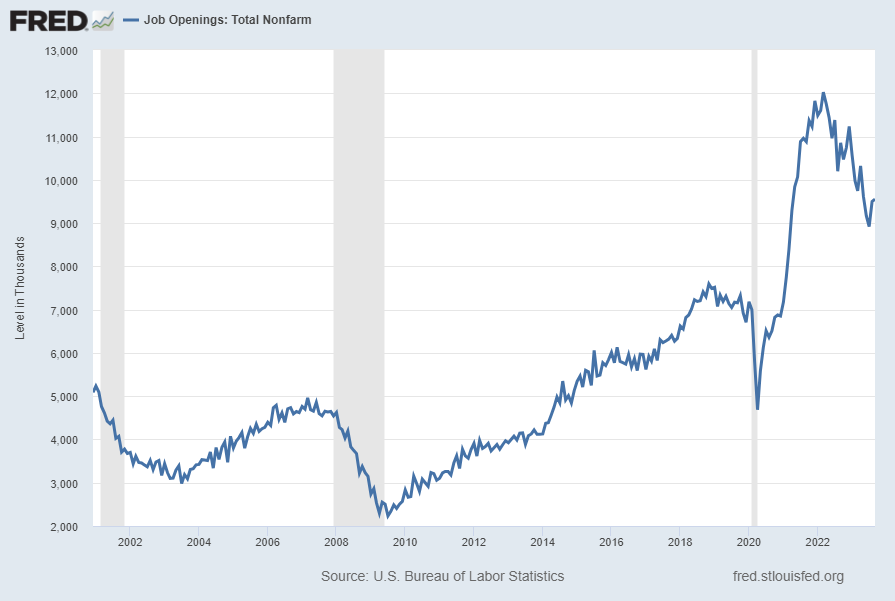
Job Openings (JTSJOL)
Job openings (Job Openings: Total Nonfarm [JTSJOL]), although still at a (very) high level, have recently declined significantly. This “Job Openings” measure had a value of 9.553 (Thousands) through September 2023 as of the November 1, 2023 update, as shown below:
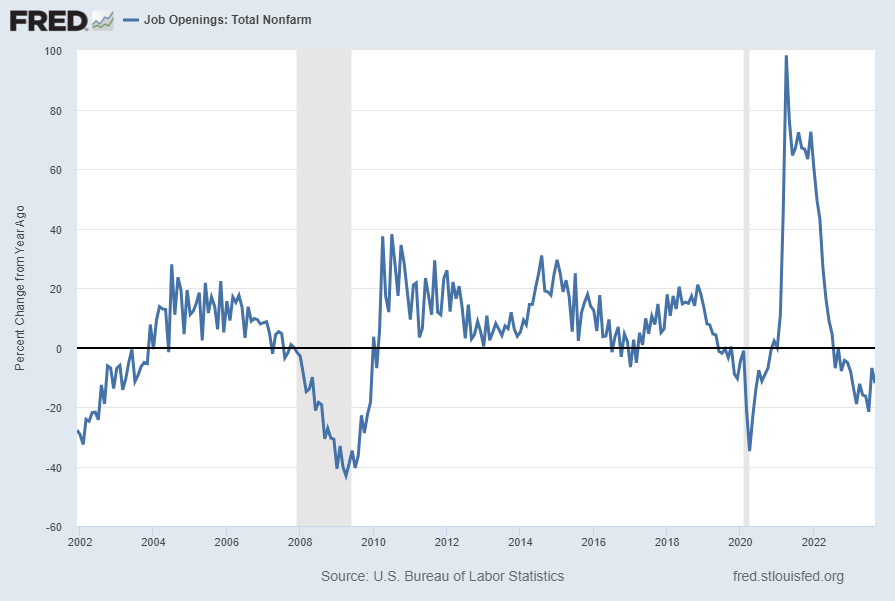
Below is this measure displayed on a “Percent Change From Year Ago” basis with value -12.0%:
source: U.S. Bureau of Labor Statistics, Job Openings: Total Nonfarm [JTSJOL], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed November 6, 2023: https://fred.stlouisfed.org/series/JTSJOL
__
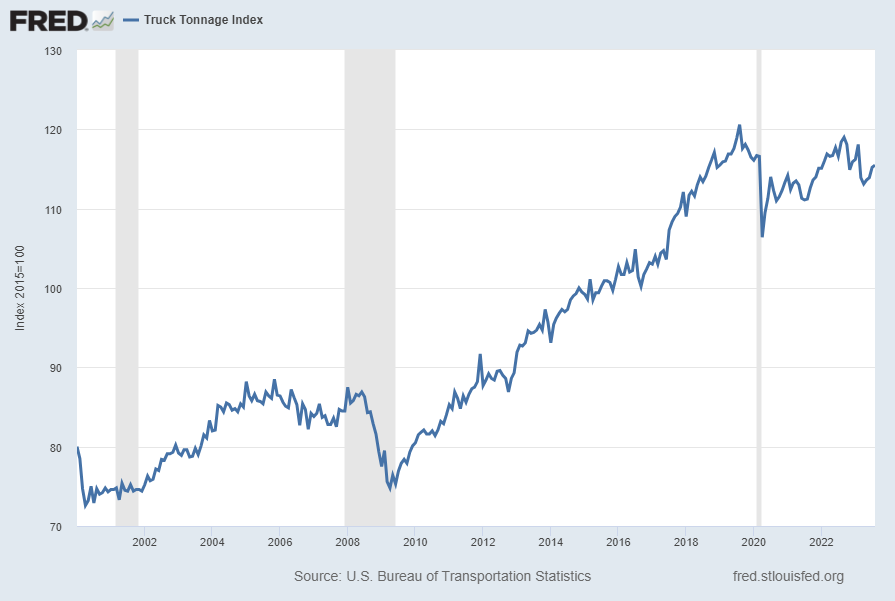
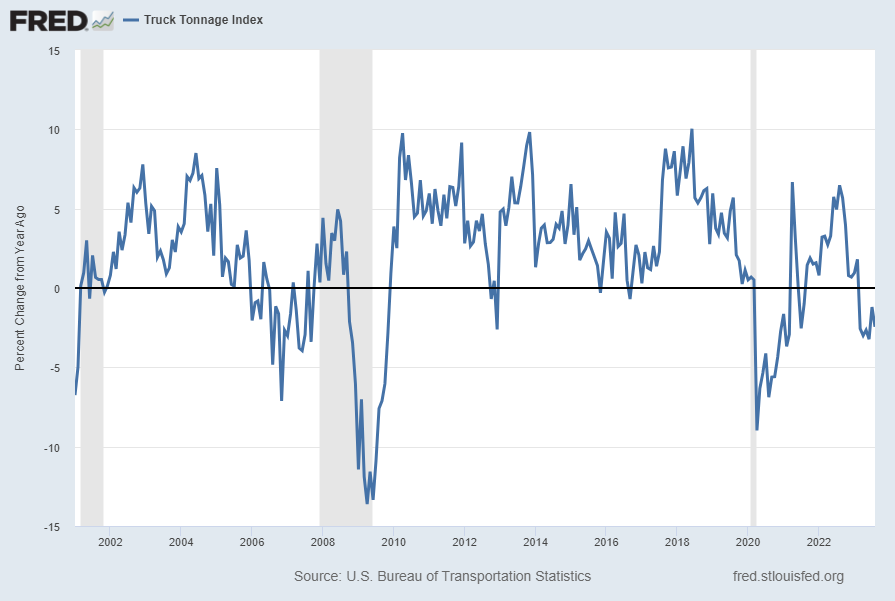
Truck Tonnage (TRUCKD11)
“Truck Tonnage” (TRUCKD11) has yet to reach its pre-pandemic peak, and has recently been faltering. Shown below is this measure with last value of 115.5 through August, last updated October 12, 2023:
Below is this measure displayed on a “Percent Change From Year Ago” basis with value -2.4%:
source: U.S. Bureau of Transportation Statistics, Truck Tonnage Index [TRUCKD11], retrieved from FRED, Federal Reserve Bank of St. Louis; accessed November 6, 2023: https://fred.stlouisfed.org/series/TRUCKD11
__
Other Indicators
As mentioned previously, many other indicators discussed on this site indicate weak economic growth or economic contraction, if not outright (gravely) problematical economic conditions.
_____
The Special Note summarizes my overall thoughts about our economic situation
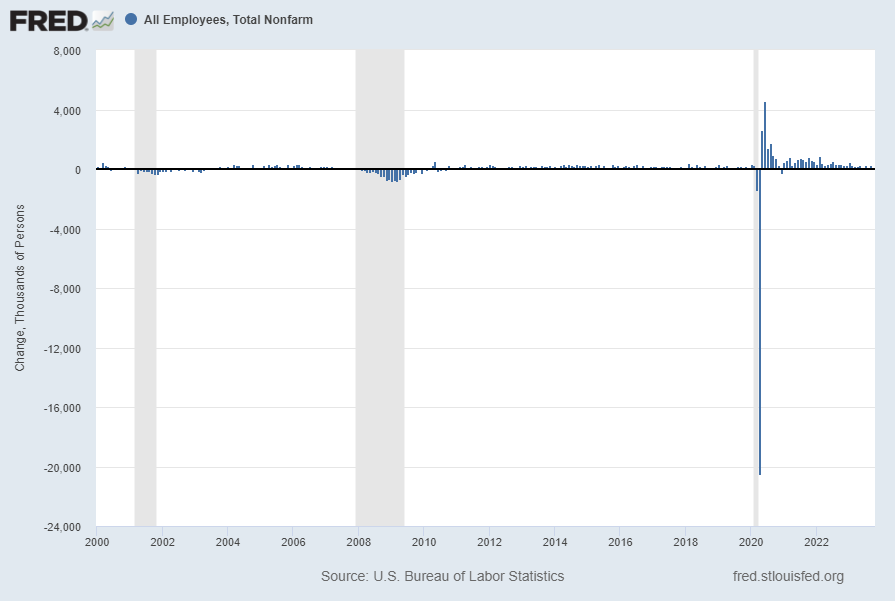
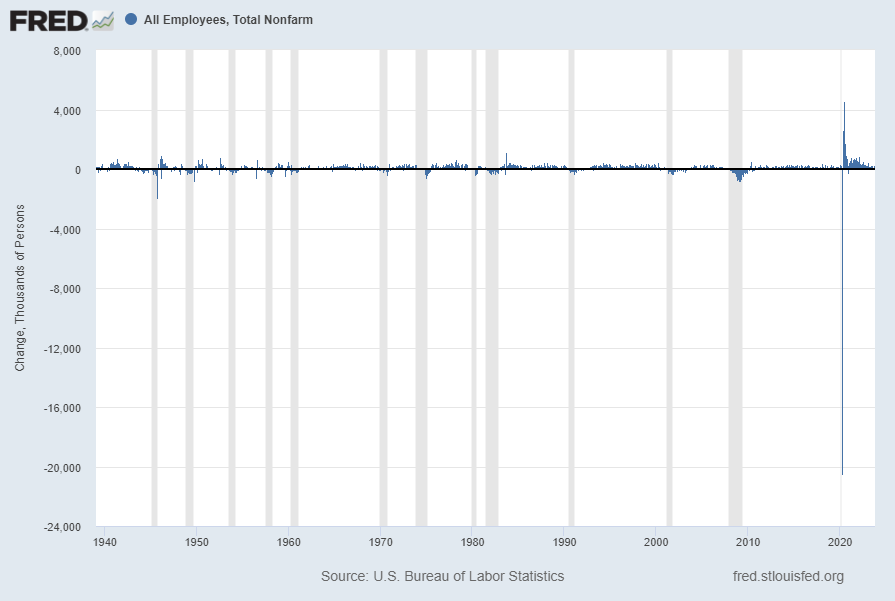
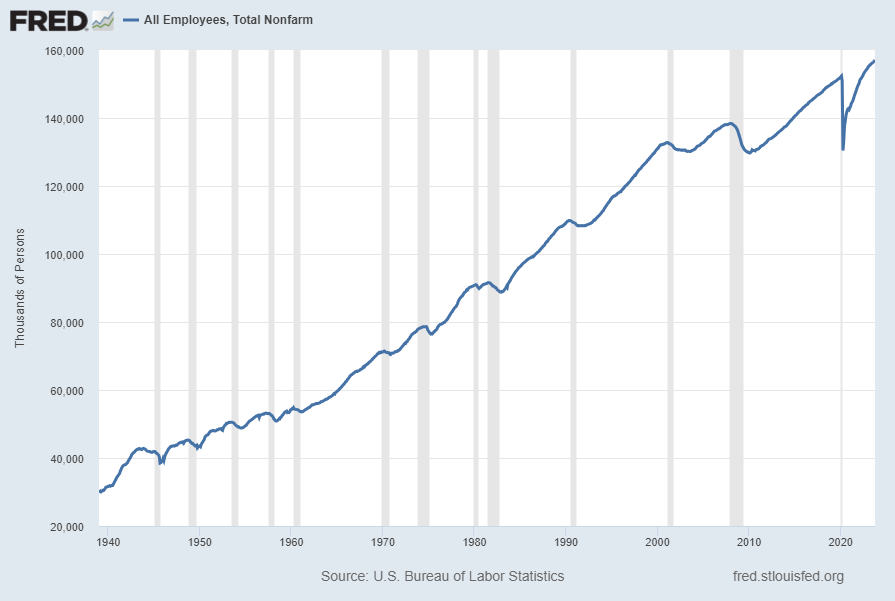
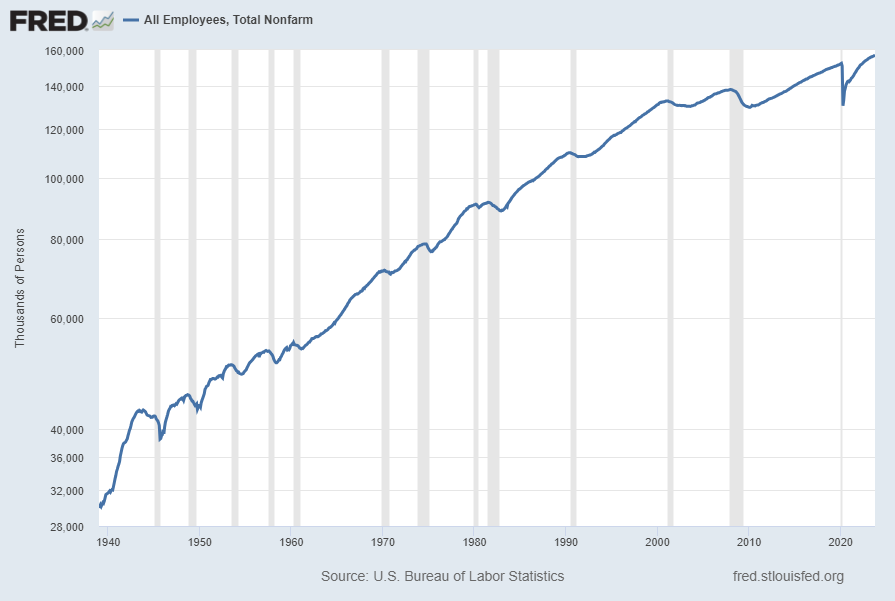
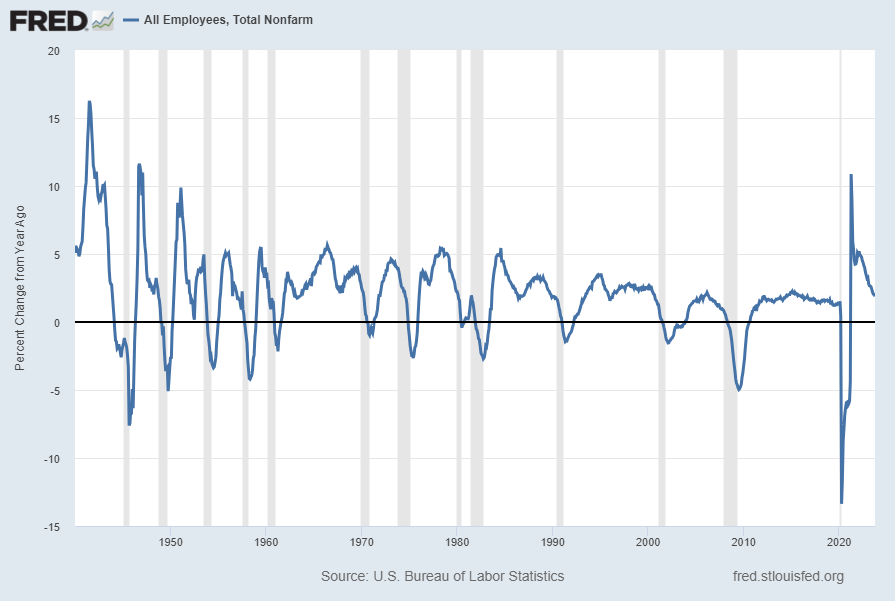
For reference purposes, below are five charts that display growth in payroll employment, as depicted by the Total Nonfarm Payroll measures (FRED data series PAYEMS).
PAYEMS, which is seasonally adjusted, is defined in Financial Reserve Economic Data [FRED] as:
All Employees: Total Nonfarm, commonly known as Total Nonfarm Payroll, is a measure of the number of U.S. workers in the economy that excludes proprietors, private household employees, unpaid volunteers, farm employees, and the unincorporated self-employed. This measure accounts for approximately 80 percent of the workers who contribute to Gross Domestic Product (GDP).
This measure provides useful insights into the current economic situation because it can represent the number of jobs added or lost in an economy. Increases in employment might indicate that businesses are hiring which might also suggest that businesses are growing. Additionally, those who are newly employed have increased their personal incomes, which means (all else constant) their disposable incomes have also increased, thus fostering further economic expansion.
Generally, the U.S. labor force and levels of employment and unemployment are subject to fluctuations due to seasonal changes in weather, major holidays, and the opening and closing of schools. The Bureau of Labor Statistics (BLS) adjusts the data to offset the seasonal effects to show non-seasonal changes: for example, women’s participation in the labor force; or a general decline in the number of employees, a possible indication of a downturn in the economy. To closely examine seasonal and non-seasonal changes, the BLS releases two monthly statistical measures: the seasonally adjusted All Employees: Total Nonfarm (PAYEMS) and All Employees: Total Nonfarm (PAYNSA), which is not seasonally adjusted.
The series comes from the ‘Current Employment Statistics (Establishment Survey).’
The source code is: CES0000000001
The first chart shows the monthly change in Total Nonfarm Payroll from the year 2000 through the current October 2023 report (October 2023 value of 150 (Thousands)):
(click on charts to enlarge images)
Data Source: FRED, Federal Reserve Economic Data, Federal Reserve Bank of St. Louis: All Employees: Total Nonfarm [PAYEMS] ; U.S. Department of Labor: Bureau of Labor Statistics; accessed November 3, 2023; https://fred.stlouisfed.org/series/PAYEMS
The second chart shows a longer-term chart of the same month-over-month change in Total Nonfarm Payroll (reports of February 1939 through the present report of October 2023):
The third chart shows the aggregate number of Total Nonfarm Payroll, from the reports of January 1939 – October 2023 (October 2023 value of 156.923 million):
The fourth chart shows this same measure of aggregate number of Total Nonfarm Payroll as seen above but presented on a LOG scale:
Lastly, the fifth chart shows the Total Nonfarm Payroll number on a “Percent Change from Year Ago” basis from January 1940 – October 2023: (October 2023 value of 1.9%)
_________
I post various indicators and indices because I believe they should be carefully monitored. However, as those familiar with this site are aware, I do not necessarily agree with what they depict or imply.
_____
The Special Note summarizes my overall thoughts about our economic situation